UN Officially Designates 1 October as International Coffee Day

Dubai – Qahwa World

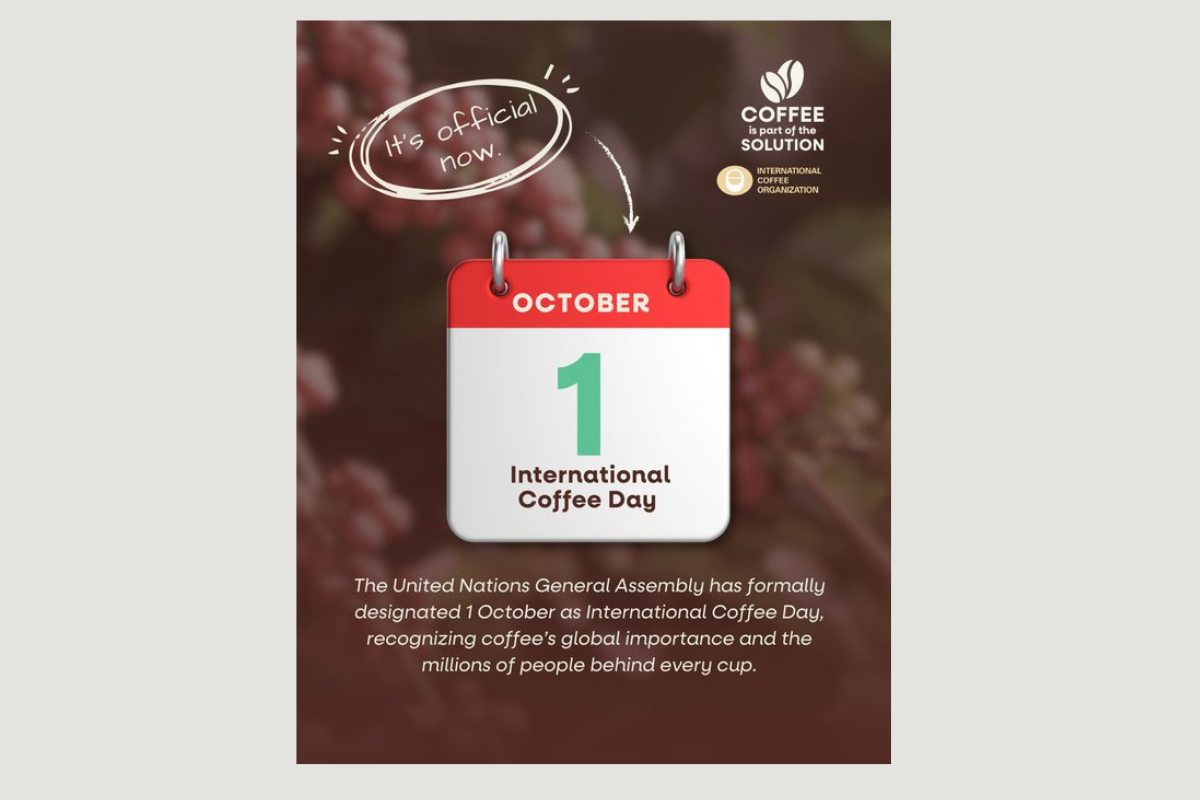
The International Coffee Organization has announced what it described as “a historic moment for the global coffee community” after the United Nations General Assembly formally designated 1 October as International Coffee Day.

According to the announcement, the decision recognizes coffee’s profound importance to global economies, cultures, and livelihoods, highlighting the role the beverage plays across producing and consuming nations alike.

The milestone follows the adoption of Resolution A/80/L.44 by the United Nations General Assembly on 10 March 2026. The resolution, introduced by Brazil, received 150 votes in favor, with one vote against from the United States and one abstention from Canada.

United Nations Officially Declares 1 October International Coffee Day

Under the resolution, 1 October will now be officially recognized every year as International Coffee Day, and all countries, United Nations bodies, and relevant stakeholders are invited to organize activities that highlight the economic, social, and environmental significance of coffee.

The resolution also invites the Food and Agriculture Organization of the United Nations to lead the annual observance in cooperation with the International Coffee Organization.

  • Elevating an existing global celebration

International Coffee Day has already been observed globally on 1 October since 2015, when the initiative was first launched by the International Coffee Organization during Expo 2015 Milan.

The new United Nations designation elevates the observance to an official international day within the UN system, giving the coffee sector broader global recognition and strengthening the visibility of the millions of people who depend on coffee for their livelihoods.

United Nations Officially Declares 1 October International Coffee Day

In its statement, the International Coffee Organization noted that the decision reflects the collective efforts of its member countries, institutional partners, and international organizations, including the Food and Agriculture Organization, to raise awareness of the coffee sector’s importance.

  • Supporting farmers and sustainability

Coffee remains one of the world’s most widely traded agricultural commodities and supports millions of farmers, workers, traders, and communities across Africa, Asia, and Latin America.

The International Coffee Organization and the Food and Agriculture Organization see the UN recognition as an opportunity to strengthen global attention to the sector’s key challenges and opportunities, including sustainability, farmer livelihoods, and climate-related risks affecting coffee production.

Qu Dongyu welcomed the decision, stating that the new international day will help raise awareness of coffee’s socio-economic importance and reinforce its role in supporting efforts to reduce poverty worldwide.

United Nations Officially Declares 1 October International Coffee Day

For the global coffee community—from smallholder farmers to exporters, roasters, and consumers—the recognition marks a significant step toward greater international acknowledgment of the industry’s cultural and economic impact.

With the adoption of the UN resolution, International Coffee Day on 1 October is expected to gain even broader global participation, as governments, organizations, and coffee professionals organize events and initiatives celebrating the beverage and the people behind every cup.

Brazil’s Specialty Coffee Sector Gains Global Momentum

Dubai – Qahwa World

The United States Department of Agriculture (USDA) published a detailed report titled “Brewing Opportunity – Brazil’s Specialty Coffee Sector Shows Strong Potential,” examining the rapid development of Brazil’s specialty coffee industry and the opportunities and challenges shaping its future.

Brazil remains the largest coffee producer and exporter in the world, while also ranking as the second-largest coffee-consuming country. Historically, the nation exported its highest-quality beans while domestic consumption focused largely on lower-grade coffee. In recent years, however, this pattern has begun to shift. Brazilian consumers are increasingly developing a taste for specialty coffee, driving growth in both production and local demand.

According to the report, the expansion of the specialty segment is supported by several structural advantages. Brazil benefits from favorable climatic conditions that allow the cultivation of diverse coffee varieties across multiple regions. In addition, the country has developed a strong network of research institutions, cooperatives, and producer organizations that focus on improving quality, innovation, and technical expertise within the coffee sector.

At the same time, the domestic market for coffee continues to expand, with consumers showing greater interest in differentiated products and higher-quality beans.

You may read: Russia’s Imports of Brazilian Coffee Fall to Six-Month Low

Despite this progress, the report notes that Brazil’s specialty coffee sector still faces several structural challenges. Many producers struggle with limited access to rural credit, making it difficult to finance investments in equipment and infrastructure. Post-harvest processing facilities—such as washing stations, pulpers, sorting machines, and drying systems—also remain insufficient in some areas, limiting the ability of farmers to produce and market high-quality coffee.

Producers have also reported uneven access to technical assistance and a limited number of certified warehouses and exporters, which can reduce profitability and hinder broader participation in the specialty coffee market, particularly among small-scale farmers.

Although specialty coffee generally costs about 50 percent more than conventional coffee, the segment offers advantages beyond price. Buyers often establish longer-term relationships with producers, which can provide farmers with greater stability and security for future harvests.

  • Major Coffee-Producing Regions

Specialty coffee production in Brazil is concentrated mainly in high-altitude regions, where elevation and moderate temperatures contribute to denser beans and more complex flavor profiles.

You may read: Brazil Crop Expectations Pressure Global Coffee Prices

The state of Minas Gerais stands as Brazil’s leading producer of arabica and specialty coffees. Regions such as Sul de Minas, Cerrado Mineiro, Matas de Minas, and Mantiqueira de Minas form a well-organized production chain that includes farmers, cooperatives, exporters, warehouses, and research institutions. Minas Gerais alone produces around 24 million bags of coffee annually, representing nearly half of Brazil’s total coffee output.

Each sub-region offers distinctive characteristics. Cerrado Mineiro became the first coffee region in Brazil to receive Designation of Origin status, while Sul de Minas is known for its concentration of small farms and its large cooperative structure. Mantiqueira de Minas has gained international recognition for its high-altitude coffees, where significant temperature variation between day and night allows cherries to ripen slowly, resulting in sweeter and more aromatic beans.

In Espírito Santo, Brazil’s second-largest coffee-producing state, production is dominated by robusta—locally known as conilon—though high-altitude areas also produce quality arabica coffee. Regions such as Caparaó and Montanhas do Espírito Santo are known for small family farms and coffees with aromatic complexity and balanced acidity.

The state of São Paulo also contributes to the specialty segment through regions such as Alta Mogiana and Média Mogiana, where coffees typically display balanced acidity, strong aroma, and a creamy body.

You may read:Coffee Prices Rise as Brazilian Real Strength Sparks Short Covering

Other regions across Brazil contribute unique characteristics as well. Rondônia, located in the Amazon region, specializes in conilon production, while Paraná, historically a major coffee producer, continues to maintain output through small farms supported by cooperatives and research institutions. Meanwhile, Bahia, one of the country’s newer coffee regions, has gained attention for its use of advanced technology and mechanized farming systems, which support high productivity levels.

  • Quality Standards and Classification

Brazil follows internationally recognized quality standards for specialty coffee. The evaluation system used by the Specialty Coffee Association scores arabica coffees on a 100-point scale, with coffees scoring 80 points or higher classified as specialty grade.

Coffees are evaluated according to sensory characteristics such as aroma, flavor, acidity, body, sweetness, balance, uniformity, and aftertaste, while also being assessed for physical defects.

Brazil also uses national classification systems aligned with these international standards. The country’s official classification process evaluates cup quality using descriptors such as strictly soft, soft, and hard, among others.

In May 2025, the Brazil Specialty Coffee Association adopted a new evaluation protocol known as Coffee Value Assessment, designed to create a more standardized approach to assessing quality and to improve communication between producers and international buyers.

You may read:Brazil Rain and Vietnam Surplus Sink Coffee Futures

Brazilian producers may also use additional certification programs—such as organic or fair-trade certifications—to meet international market requirements, although these certifications do not automatically classify a coffee as specialty.

The quality of Brazilian robusta and conilon coffee has also improved in recent years, contributing to stronger demand and higher prices. Brazil is currently the second-largest producer of robusta coffee globally, behind Vietnam.

  • Challenges Affecting Growth

The report highlights genetics as another key factor in specialty coffee production. However, inconsistencies between international and national databases for coffee cultivars sometimes create challenges. Some varieties recognized internationally for exceptional quality are not officially registered for cultivation in Brazil, while many important Brazilian cultivars are absent from international quality catalogues.

These discrepancies can complicate certification and recognition processes for producers and may increase production costs or reduce profitability.

Specialty coffee production also requires significant investments in cultivation techniques and post-harvest infrastructure. Because these investments can be costly, the specialty coffee sector in Brazil remains concentrated among a relatively limited number of producers.

  • Growing Interest Among Brazilian Consumers

Although Brazil has long been a global coffee powerhouse, domestic appreciation for specialty coffee is relatively recent. Since the early 2000s, coffee culture has evolved significantly as consumers began exploring higher-quality beans, alternative brewing methods, and greater transparency regarding coffee origins.

You may read:India’s Quiet Coffee Superpower

Recent consumer surveys show that some Brazilians have reduced overall coffee consumption in response to rising prices. Nevertheless, demand for specialty coffee continues to grow. The report indicates that consumption of specialty coffee in Brazil has been increasing by about 15 percent per year, significantly faster than the growth of traditional coffee consumption.

Specialty coffee consumption in the country is estimated at around 70,000 tons annually, representing approximately five to ten percent of total coffee consumption.

Consumers interested in specialty coffee tend to seek differentiated beans, visit cafés that emphasize brewing quality, and show greater interest in sustainability practices and traceability.

  • Trade Trends and Export Markets

Brazilian export data does not track specialty coffee as a separate category. Instead, exporters often group it under “differentiated coffees,” which include beans certified for quality, sustainability, or other distinctive characteristics.

According to export data, Brazil shipped 8.1 million bags of differentiated coffees in 2025, representing about 20 percent of the country’s total coffee exports. Although export volumes declined compared with the previous year, revenues increased significantly to approximately 3.5 billion dollars, partly due to favorable exchange rates.

The United States remained the largest destination for Brazilian differentiated coffees, importing about 1.3 million bags, followed by Germany, Belgium, the Netherlands, and Italy. European markets often function as distribution hubs that supply specialty coffee to other regions.

  • Global Promotion and Future Outlook

Brazil is actively promoting its specialty coffee sector internationally through initiatives designed to strengthen its presence in global markets. One such program focuses on marketing Brazilian specialty coffees through trade fairs, branding campaigns, and partnerships with international buyers.

Priority markets include the United States, Japan, China, South Korea, the United Arab Emirates, France, and Australia, while processed coffee products such as roasted and ground coffee are being promoted in markets including Canada, Chile, China, and the United States.

The initiative is scheduled to run until 2027 and aims to expand Brazil’s leadership in the global specialty coffee sector.

The report concludes that rising international demand for traceable, sustainable, and high-quality coffee—combined with ongoing improvements in production and promotion—positions Brazil’s specialty coffee industry for continued growth in the years ahead.
Coffee Farmers in Central America Struggle to Survive Falling Prices

Dubai – Qahwa World

The Guardian published a lengthy report titled “‘Everyone feels like they are being scammed’: can Central America’s small coffee growers survive as global prices fall?”, which discussed the growing pressures facing coffee farmers in parts of Central America, particularly in El Salvador and Honduras. The report explores how climate instability, rising production costs, labour shortages and volatile global markets are reshaping coffee farming across the region.

According to the report, many small producers who have depended on coffee cultivation for generations are now confronting increasingly unpredictable conditions. Weather patterns that once followed a familiar seasonal rhythm have become less reliable, making it difficult for farmers to plan their harvest cycles and manage their farms effectively.

The report begins on a hillside in western El Salvador, where coffee farmer Oscar Leiva observes rainfall arriving in December, a month that traditionally marked the beginning of the dry season. During the latest harvest cycle, flowering occurred early and then stalled, followed by a period of intense heat. As a result, the remaining crop is uneven in quality and more expensive to produce than previous harvests.

You may like: Global Study Maps the “Carbon Footprint” of Latin American Coffee

For Leiva’s family, coffee is not simply a crop but a long-standing way of life. His mother, Esperanza Marinero, remembers when the rainy season arrived on time and harvests could be planned months ahead. Today, that certainty has disappeared. Farmers must make decisions about pruning, fertilising and hiring workers without reliable seasonal patterns, increasing the financial risks they face.

Coffee has historically played a major role in El Salvador’s economy. In the mid-1970s the country ranked among the world’s leading coffee producers, with harvests exceeding five million quintales, a unit equal to about 46 kilograms. Today, national production struggles to reach one million quintales.

The report notes that this decline reflects more than market cycles. Decades of land restructuring, climate shocks and rural migration have weakened the coffee sector and altered the agricultural landscape. Increasing climate volatility has disrupted flowering cycles, reduced yields and affected the quality of coffee, particularly for small farmers who lack financial reserves to absorb repeated losses.

Read also: Shock in the Coffee Market: Colombia’s Production Drops 36%

Cecibel Romero, a researcher focusing on coffee production, explained that the sector is experiencing overlapping challenges that extend beyond climate change alone. Rising temperatures, irregular rainfall and plant diseases such as coffee rust have exposed long-standing vulnerabilities in traditional production systems.

Romero noted that past production models often focused on maximising yields and implementing short-term solutions rather than building long-term resilience. After severe rust outbreaks in the early 2010s, many producers replanted their farms with varieties believed to be resistant. However, some of these varieties produced lower-quality beans or did not maintain their resistance over time.

As coffee’s economic importance declined in El Salvador, public support systems for the sector were also reduced. Agricultural services weakened, renovation programmes became fragmented and access to affordable credit narrowed. As a result, many producers have been left to cope with climate risks, disease outbreaks and market volatility largely on their own.

Read also:Coffee Markets Rise Amid Middle East Shipping Disruptions

Similar pressures are being felt in Honduras, the largest coffee producer in Central America. Although overall production remains higher than in El Salvador, farmers there are also dealing with rising costs and climate-related challenges.

Juan Luis Hernández, a forest engineer who has worked on environmental projects connected to the Honduran Coffee Institute, said adapting to changing conditions requires investment, time and labour. Measures such as managing shade trees, restoring soil health, protecting water sources and monitoring plant diseases all require resources that are not equally available to all farmers.

In the Honduran region of Copán, farmer Gerardo Vásquez manages an eight-hectare family farm while also advising other growers. Trained through the Honduran Coffee Institute, he works on soil analysis, selecting coffee varieties and developing agroforestry systems.

Even with this technical background, Vásquez says the economic reality of coffee farming remains difficult. Establishing one manzana of coffee — roughly 0.7 hectares — now costs about 200,000 lempiras over a period of three years.

Read also: Bridging the Gap: An Exclusive Dialogue with Vanusia Nogueira on the Global Coffee Crisis and the Path to 2026

Production costs have risen significantly in recent years. Fertiliser prices increased sharply after the pandemic, while labour shortages have pushed wages for harvest workers higher. When harvesting, processing and transport are included, farmers may spend more than 3,000 lempiras to produce a single quintal of parchment coffee.

Weather conditions can further complicate the process. Continuous rainfall makes drying coffee difficult, forcing some farmers to sell freshly picked cherries directly from the field at lower prices. Others depend on intermediaries who provide advance payments, which can limit farmers’ ability to negotiate prices later.

Climate change is also affecting where coffee can be grown successfully. Farms located below 1,000 metres above sea level are becoming more vulnerable to heat stress, pests and diseases. As a result, coffee cultivation has gradually moved to higher elevations over time.

However, relocating production to higher ground is not feasible for many smallholders, who may not have access to suitable land or the financial means to make such changes.

At Café San Rafael in Honduras, co-owner Carlos Guerra explained that the flowering cycle of coffee plants has become increasingly irregular. What once occurred within a predictable timeframe now happens in stages, extending the harvest period and raising labour costs.

Labour itself has become one of the most pressing challenges for producers. Coffee harvesting requires careful selection of ripe cherries, a process that cannot easily be mechanised. Younger workers are increasingly leaving rural areas, making it harder for farms to recruit enough labour during harvest season.

Farmers are experimenting with various adaptation strategies, including planting additional shade trees and improving soil management practices. While these measures can help protect coffee plants from heat stress, they may also reduce yields, creating a difficult balance between environmental resilience and economic viability.

Some farms attempt to offset these challenges by focusing on higher-value markets. At Café San Rafael, careful management of fermentation and drying processes helps maintain coffee quality even when harvest conditions are uneven. Operating a roastery also allows the business to manage fluctuations in supply.

However, many small farmers do not have access to such opportunities. Entering specialty coffee markets often requires certification, processing infrastructure and export connections that remain beyond the reach of numerous producers.

Emeric Seguin, director of sourcing and sustainability at a specialty coffee company working with producers in Central America, told the newspaper that mistrust is widespread within the supply chain. Farmers often feel undervalued, while buyers worry about inconsistent supply, leaving cooperatives caught between both sides.

Several initiatives are attempting to promote more resilient farming practices. In El Salvador, a coffee production school known as Renacer encourages ecological approaches that focus on soil health, shade restoration and long-term stability rather than maximising short-term yields.

Agronomist Sigfredo Corado explained that the goal is to reduce extreme fluctuations in harvests. While farms may not achieve exceptionally high yields in strong years, they are also less likely to experience severe drops in production.

Despite these efforts, the report notes that global market conditions could add further pressure. Rabobank has predicted that increasing coffee surpluses in the coming seasons could push international prices lower, potentially making coffee production less viable for smallholders.

As profitability declines, some land previously used for shaded coffee is being converted to other crops or sold for development, gradually altering landscapes that have long been associated with coffee cultivation.

For farmers such as Oscar Leiva, planning for the next season remains unavoidable despite the uncertainty. Each harvest now requires decisions to be made without the reliable patterns that once guided coffee farming.

Across Central America, producers continue searching for ways to adapt to changing environmental and economic realities, while the long-term sustainability of smallholder coffee farming remains an open question.

Global Study Maps the “Carbon Footprint” of Latin American Coffee

Dubai – Qahwa World

A comprehensive international study released in March 2026 has revealed a sharp disparity in the carbon footprint of coffee production across five major Latin American nations. This landmark report establishes the first precise scientific baseline—using primary data collected directly from farms—to address climate change challenges within the global coffee sector.

The study, conducted by Conservation International in collaboration with the Sustainable Coffee Challenge and Meo Carbon Solutions, analyzed supply chains in Brazil, Colombia, Honduras, Mexico, and Peru. The findings provide a “wake-up call” for the industry, highlighting how specific farming practices, particularly fertilization and waste management, dictate environmental impact.

  • The Emission Gap: Colombia Leads while Mexico Sets a Benchmark

Detailed data shows that coffee production in Colombia generates the highest greenhouse gas emission intensity, averaging 5.59 kg of carbon dioxide equivalent (CO2-eq) per kilogram of green coffee. Honduras followed with 4.87 kg. In Brazil, the results varied by variety, with Arabica recording 3.22 kg compared to 2.51 kg for Robusta.

Conversely, Mexico emerged as the country with the lowest emissions in the study group, averaging just 1.46 kg. Experts attribute this lower footprint to specific traditional farming practices, including greater reliance on natural shade and organic soil health.

  • Fertilizers: The Primary Climate Culprit

According to the extensive technical report, the most significant “hotspot” for emissions in Latin American coffee is fertilizer and nutrient application. In Colombia and Brazil, fertilization accounts for approximately 60% of the total carbon footprint. This is primarily due to the heavy use of nitrogen-based inputs, which release potent greenhouse gases when interacting with the soil.

In other regions, the drivers differ. In Peru, “crop residues” and unmanaged organic decomposition were identified as the primary sources of emissions. Meanwhile, in Honduras, the traditional wet processing of coffee cherries—specifically the management of wastewater at the farm level—contributes significantly to the national baseline.

  • A “Pre-Competitive” Global Alliance

The study is the result of an unprecedented “pre-competitive” alliance involving major global coffee brands, roasters, and suppliers. Giants such as Nestlé, Starbucks, and JDE Peet’s contributed by sharing primary data and technical oversight to harmonize carbon accounting standards across the industry.

This collaboration aims to empower stakeholders to direct investments toward “regenerative agriculture.” These practices focus on reducing chemical dependency, improving on-farm waste management, and enhancing the soil’s ability to sequester carbon rather than release it.

  • A Roadmap for Investors and Farmers

The report concludes with actionable recommendations, stressing that reducing the carbon footprint is no longer just an environmental goal but a commercial necessity. As international environmental regulations tighten, understanding these baselines is essential for maintaining global market access.

The findings confirm that transitioning to integrated nutrient management, improving water efficiency, and recycling coffee by-products into natural fertilizers are the most effective ways to bridge the carbon gap revealed in countries like Colombia and Honduras.

Coffee Markets Rise Amid Middle East Shipping Disruptions

Dubai – Qahwa World

Global coffee markets moved higher last week as escalating tensions in the Middle East disrupted key shipping routes and increased freight costs, while supply developments in major producing countries also influenced market sentiment.

Arabica coffee futures began the week at 279.90 US cents per pound and briefly approached the 290-cent level before easing slightly. The market maintained upward momentum through the week, posting marginally higher closes on Wednesday and Thursday. By Friday, prices opened 5.45 cents per pound higher than the previous day’s close, supported in part by reports that Brazil’s coffee exports fell 17.4% year-on-year in February.

You may like:Shock in the Coffee Market: Colombia’s Production Drops 36%

  • Shipping routes under pressure

Market activity during the period from March 2 to March 5 was shaped largely by geopolitical developments rather than major supply news from coffee-producing regions.

Military strikes involving the United States and Israel against Iran, followed by retaliatory actions, disrupted shipping activity through the Strait of Hormuz, a critical route for global trade. At the same time, shipping companies remain cautious about passing through the Red Sea amid concerns over possible attacks by Yemeni Houthi rebels.

These risks have forced some vessels to take longer routes around the Cape of Good Hope, significantly increasing transportation times as well as freight and insurance costs. The situation has added new uncertainty to global supply chains, including agricultural commodities such as coffee.

Read also: Kim Thompson: Coffee on the Edge of Disruption

  • Weather challenges in Colombia

At origin, coffee production conditions in Colombia remain difficult due to excessive rainfall. Persistent wet weather has affected flowering, maturation, and bean development in several regions, particularly in southern areas where limited sunshine has compounded the problem.

Producers and exporters are also facing economic pressure. The stronger Colombian peso, combined with the recent decline in the C-market price, is expected to reduce revenues compared with the previous year.

As a result, exporters have slowed sales, leading to lower export volumes and rising inventories while waiting for more favorable market conditions when possible.

  • Honduras harvest nearing completion

In Honduras, the harvest season has moved well beyond its peak, with more than 75% of the crop already collected. Harvesting has largely finished in lower-altitude regions, leaving mainly higher-elevation farms still gathering the remaining coffee.

Purchasing activity remains mixed. Exporters who secured contracts earlier at higher market prices are continuing to buy coffee cherries and parchment, while others with fewer forward commitments are delaying purchases.

Read this also; Oil Surge Could Brew Higher Coffee Prices

  • Currency markets react

Currency markets were also influenced by developments in the Middle East, with the US dollar strengthening following the weekend’s military strikes.

The GBP/USD and EUR/USD currency pairs initially dropped to 1.327 and 1.155, respectively, before recovering slightly to around 1.332 and 1.160 by Tuesday afternoon.

For the remainder of the week, both pairs traded mostly within a lower range compared with previous weeks as investors monitored geopolitical developments and their potential impact on global trade and energy markets.

  • Market outlook

While major supply-side news from coffee-producing countries remained limited during the week, traders continue to monitor shipping disruptions, weather conditions at origin, export flows, and currency movements. These factors are expected to remain key drivers of short-term price movements in global coffee markets.

Belarusian “Americano”: Lukashenko Proposes a National Version

Minsk – Qahwa World

In Belarus, an unusual initiative is under discussion: President Alexander Lukashenko has suggested creating a national version of the popular Americano coffee. The proposal could affect all fast-food establishments across the country.

The idea was announced during Lukashenko’s visit to the “Mak.by” chain, which positions itself as a Belarusian alternative to international fast-food brands. The president emphasized that it is important to build national traditions even in small details, such as the names of beverages. He proposed that, initially, the new name could be shown alongside the familiar one in parentheses, allowing customers to gradually adapt to the change.

You may read: “Candiano”: From a Simple Joke to a National Debate on Identity and More

Supporting domestic brands in the food service sector has become a priority for Belarusian authorities. Renaming the Americano could become part of a broader campaign to promote national products and strengthen Belarusian cultural identity. However, the initiative may spark debates among coffee lovers accustomed to international standards and names.

The exact name for the Belarusian version of the Americano has not yet been revealed. Nevertheless, the proposal has already prompted lively discussion among entrepreneurs and café visitors: some see it as a way to highlight Belarusian uniqueness, while others view it as an unnecessary formality.


Shock in the Coffee Market: Colombia’s Production Drops 36%

Dubai – Qahwa World

Coffee production in Colombia, the world’s largest producer of washed Arabica coffee, recorded a sharp drop in February 2026. Production reached 869,000 bags, with each bag weighing 60 kilograms, marking a decline of 36% compared with the same month last year. This decrease reflects a continuing negative trend that is putting pressure on the global coffee supply.

  • Noticeable Drop in Annual Production

When looking at the total production over the last 12 months, from March 2025 to February 2026, the total reached 12.72 million bags. This represents a decline of 14% compared with the previous cycle.

German Bahamon Jaramillo, the general manager of the National Coffee Federation (FNC), said that the current situation requires urgent action to protect the stability of the sector and maintain farm productivity, according to the Argentine newspaper Infobae.

You may like: Colombian Coffee Day Celebrated at Dubai Coffee Museum

The main recommendations include improving fertilization to restore plant strength and renewing coffee farms to ensure sustainable production in the medium term. There are also calls for direct support measures for farmers to help them deal with lower profits caused by reduced production.

  • Exports Also Decline

The drop in production has also affected exports. Coffee exports in February fell by 32%, reaching 807,000 bags.

During the beginning of the agricultural season, from October to February, total exports reached 5.06 million bags. This is a decline of 14% compared with the same period in the previous cycle.

  • Production Under Pressure

Experts say this decline shows how vulnerable coffee production is to climate changes and farm management problems. It also puts pressure on global prices and may increase the cost of coffee for consumers. At the same time, it makes it more difficult for small farmers to maintain sustainable businesses.

  • Main Reasons for the Decline

Several factors are behind the drop in production.

Climate changes:
Continuous heavy rain and thick cloud cover affected flowering and plant growth. This also led to the spread of diseases such as coffee leaf rust, although detection rates remain low thanks to resistant coffee varieties.

Read Also: Historic Colombian Coffee Harvests Face Labour Shortages

Farm management challenges:
Coffee plants are showing signs of exhaustion after several years of strong production. The 2024/2025 season recorded the highest production level in 30 years. In addition, higher costs for inputs such as fertilizers and labor have increased pressure on farmers.

Weak start to 2026:
The decline follows a 34% drop in January 2026, when production reached 893,000 bags, making the start of the year one of the weakest in recent years.

  • Suggested Actions

Experts suggest several steps to address the situation.

Short term:
Improve fertilization to strengthen plants and provide direct financial support for small farmers, who produce about 70% of the country’s coffee, to help offset income losses.

Medium term:
Renew coffee farms to ensure long-term sustainability and adopt varieties that are more resistant to climate conditions. Price-stabilization mechanisms are also recommended to reduce market volatility.

Long term:
Address climate change through global strategies. A report from the International Coffee Organization (ICO) and other groups expects that global coffee production could be affected by up to 50% by 2050 if adaptation measures are not taken.

  • Impact on Global Supply

Colombia represents about 10% to 12% of global Arabica production. Because of this, any decline in its output puts pressure on the global supply, especially when production also drops in countries like Vietnam or Indonesia during some periods.

However, some of this pressure may be eased by expectations of a record Brazilian crop in the 2026/2027 season, estimated at 66.2 million bags, an increase of 17.2%. This could push global production to around 180 million bags.

Still, climate volatility keeps supply fragile. As a result, major international buyers, including the United States and Europe, may look for temporary alternatives.

  • Price Movements

Arabica prices recently fell from record levels above $4 per pound in November 2025 to about $2.80 to $3.00 per pound today, mainly because of strong crop expectations in Brazil.

However, the decline in Colombian production has helped push prices up by about 2% to 5% in recent weeks. This increase is linked to concerns about global supply and geopolitical tensions, including shipping disruptions in the Strait of Hormuz.

The World Bank expects Arabica prices to fall by 13% to 15% during 2026 overall. But this outlook could change if production in Colombia continues to decline.

For consumers, coffee prices in the market may rise by about 5% to 10% in the short term, especially in Europe and the United States.

Amal Al-Ekadi: A Woman’s Voice Showcasing the Value of Yemeni Coffee

Dubai Ali Alzakary

At the heart of coffee’s long story, Yemeni coffee remains one of its most authentic and fascinating chapters. From the mountains of Yemen—where coffee first began its journey to the rest of the world—the beans still carry the aroma of history and the character of a land cultivated by generations of farmers. Yet such a rich legacy always needs voices capable of telling its story and bringing it back into the global spotlight.

Among those voices is Amal Al-Ekadi, a Yemeni coffee advocate and marketing specialist who has dedicated years to promoting Yemeni coffee and highlighting its place in the global market. In this conversation with Qahwa World, Al-Ekadi shares her personal journey, the challenges she has faced, and her hopes for the future of Yemeni coffee. Through the following lines, readers are invited to discover her story and vision.

  • A Journey into the World of Coffee

Amal Al-Ekadi describes herself as someone who has been deeply engaged in the world of Yemeni coffee for several years, particularly in promoting and introducing Yemeni beans to wider audiences. Her professional path began at a foreign company where she worked in the production department before gradually advancing into shipping and export operations.

Throughout this journey, she says her goal remained clear: to help the world recognise the true value and rich heritage of Yemeni coffee. Today she is based in Riyadh, but she still considers herself part of the ongoing effort to amplify the voice of Yemeni coffee internationally.

  • Passion Behind the Idea

Al-Ekadi explains that her decision to work in promoting Yemeni coffee grew from her deep love for it and her belief that it represents a true treasure. Yemen, she notes, is the birthplace of coffee, yet marketing efforts have not always reflected this historical importance. This realization motivated her to become part of a movement that introduces people to this remarkable product and restores its rightful place in the global coffee scene.

  • A Flavor That Tells a Story

What fascinates Amal Al-Ekadi most about Yemeni coffee is its unique flavor profile and the diversity that appears from one region to another. For her, Yemeni coffee is far more than a beverage—it is a story, a culture, and a way of life shaped by farmers who dedicate years of work and care to cultivating these beans before they reach a cup.

  • First Steps

Her beginnings in the field were modest. Amal Al-Ekadi started by communicating directly with farmers and learning about the different varieties of Yemeni coffee. She also acknowledges the support she received from her former manager, Shubair Ezi, whose guidance played an important role in her early career.

Through her work in shipping and export, she gained practical experience while also introducing Yemeni coffee to wider audiences through social media and professional connections with coffee enthusiasts both inside and outside Yemen.

  • Challenges Along the Way

The path, however, was not without obstacles. Al-Ekadi points to the difficult circumstances Yemen has experienced in recent years, including war and the logistical challenges of transportation and export.

Despite these difficulties, Yemeni coffee has continued to find its way to global markets, thanks to the efforts of people who believe deeply in its value and remain committed to sharing it with the world.

Amal Al-Ekadi: A Yemeni Voice Promoting Yemeni Coffee

  • Growing Global Interest

According to Amal Al-Ekadi, the past few years have brought a noticeable shift in how people perceive Yemeni coffee. With the rapid growth of the specialty coffee movement worldwide, more consumers and professionals have begun to recognize the exceptional quality and distinctive character of Yemeni beans.

This renewed interest has helped return Yemeni coffee to the international conversation about premium and specialty origins.

  • The Distinctive Flavors of Yemen’s Mountains

While she believes every Yemeni coffee origin has its own charm, Amal Al-Ekadi says she is particularly drawn to coffees from mountainous regions such as Haraz and Yafa. Beans from these areas often display complex and rich flavor profiles that appeal strongly to specialty coffee enthusiasts.

  • The Growing Role of Yemeni Women

Amal Al-Ekadi also highlights the important role Yemeni women play in the coffee sector, from farming and processing to marketing and promotion. She believes women’s presence in the industry has become increasingly visible and influential in recent years, a development she considers both encouraging and essential for the sector’s future.

  • A Dream for Yemeni Coffee

For Amal Al-Ekadi, the long-term dream is for Yemeni coffee to fully reclaim its global reputation. Equally important is ensuring that Yemeni farmers receive the recognition and fair prices they deserve for the tremendous effort they invest in cultivating this historic crop.

  • A Message to Farmers and Young Entrepreneurs

In closing, Amal Al-Ekadi offers a message to farmers and young people interested in entering the coffee sector. Farmers, she says, are the foundation of this precious heritage, while the younger generation holds the key to its future development.

With greater awareness, thoughtful work, and professional marketing, she believes Yemeni coffee can become not only a source of pride but also an important economic pillar for Yemen.

Amal Al-Ekadi also expressed her appreciation to Qahwa World and to Mr Ali for the opportunity to share her experience with Yemeni coffee, expressing hope that collective efforts will continue to highlight the value of this historic product and bring it the recognition it deserves.


Russia’s Imports of Brazilian Coffee Fall to Six-Month Low

Moscow – Qahwa World

Russia significantly reduced its imports of Brazilian coffee in February 2026, reaching the lowest level recorded since September 2025, according to Brazilian customs data cited by RIA Novosti.

Shipments to Russia totaled about 2.8 thousand tons, valued at $20.3 million. This represents a 1.8-fold decline compared with January 2026 and a 2.6-fold drop compared with February 2025. As a result, Russia’s position among the largest importers of Brazilian coffee fell from seventh to fourteenth place.

The decline occurred during a broader slowdown in Brazil’s coffee exports. In February, total Brazilian shipments reached 142.5 thousand tons, worth $1.03 billion, marking a 0.7% decrease from January and a 17% decline year-on-year.

You may like: Russia Updates Instant Coffee Standards for the First Time in 32 Years

The reduction in exports to Russia, however, was more pronounced and appears linked to several domestic economic developments. Economic pressures in Russia have led to an increased pace of restaurant and café closures, reported to be the fastest since 2021 according to data from Sberbank. The shift has reduced demand for imported coffee as more consumers move toward lower-cost food options.

Global coffee prices may also be influencing purchasing decisions. During 2025, arabica prices rose by roughly 25%, encouraging some buyers to delay purchases while waiting for potential price declines. Expectations of a strong Brazilian harvest for the 2026/2027 crop year, projected at 66.2 million bags, have already pushed arabica futures down to about $2.80 per pound in early March 2026.

At the same time, Russia’s instant coffee sector has expanded. The country increased exports of instant coffee by 28% in 2025, reaching $366 million, which may partly reduce reliance on imported green coffee.

Read Also: Russian Instant Coffee Exports Rise 28% to $366 Million

Trade policy changes may also influence future imports. Russia removed a 40% import duty on Brazilian coffee at the end of 2025, a move that could support a recovery in shipments in the coming months. Meanwhile, the Russian standards agency Rosstandart has approved an updated national standard for instant coffee that will take effect in November 2026, expanding the classification to include granulated and freeze-dried coffee, replacing a standard dating back to 1994.

Despite the drop in Russian purchases, several countries remained the largest importers of Brazilian coffee in February, including Germany, Italy, the United States, Belgium, and Japan, with import volumes ranging between 8.3 thousand and 23.4 thousand tons.

The sharp decline in Russia’s imports highlights a possible shift in the country’s coffee market, influenced by economic conditions, changing consumption patterns, and developments in global coffee supply.

Caffè Nero Forecasts Rising Prices Amid Steady Global Growth

Dubai – Qahwa World

Caffè Nero is pressing ahead with its international expansion, even as it warns that the price of a cup of coffee is likely to keep climbing. The premium coffee house group cited a volatile mix of geopolitical conflict, rising labor costs, and climate-driven supply shortages as the primary drivers behind the anticipated hikes.

The family-owned business, which operates 1,151 outlets globally, is targeting significant growth this year. The group plans to open 30 new stores in the UK and up to 70 additional locations across its 10 international markets. This expansion follows the recent acquisition of Washington D.C.-based Compass Coffee, a move that integrated 15 new sites and a dedicated roasting facility into the brand’s North American infrastructure.

  • A Different Rhythm

Gerry Ford, who founded the chain in 1997, suggests that Caffè Nero’s private ownership has allowed it to weather the current economic storm better than its publicly traded rivals. While competitors like Starbucks and Costa have struggled with store closures or stalled sales plans, Ford attributes Nero’s resilience to a “steady pace” and longer-term planning.

“We don’t want to take over the world,” Ford noted. “We have more flexibility because we aren’t trying to hit a quarterly reporting target. We move to our own rhythm.”

  • Financial Headwinds

Despite a 13% jump in annual sales to £587.6 million, the group’s pre-tax losses widened to £41 million. This was largely due to the rising cost of servicing its £481 million debt, fueled by recent interest rate hikes and a string of strategic acquisitions, including 200 Degrees and Harris + Hoole.

Caffè Nero Forecasts Rising Prices Amid Steady Global Growth

To manage these costs, Ford confirmed that the group will pause further acquisitions for at least a year to focus on integrating its latest purchases and meeting upcoming debt repayments.

  • The Cost Crisis

The industry is currently facing a “perfect storm.” Coffee prices tripled between 2023 and early 2025 as the climate crisis ravaged crops in Brazil and Colombia. While wholesale prices have recently stabilized, they remain nearly double what they were three years ago.

Ford warned that consumers shouldn’t expect relief at the till anytime soon. The ongoing conflict in the Middle East continues to drive up energy and shipping costs, while rising business rates and wages in the UK add further pressure. Data shows that the average price of a latte has already surged by 35% over the past five years, now sitting at approximately £3.76.

Despite these challenges, Ford remains bullish on the future of the specialty coffee sector, insisting that there is still plenty of “white space” for independent, premium brands to thrive globally.

Kim Thompson: Coffee on the Edge of Disruption

Dubai – Ali Alzakary

The global coffee industry has spent the past few years navigating one disruption after another—from pandemic shutdowns and climate volatility in producing countries to freight crises that reshaped global shipping routes. As the global coffee market grapples with volatility—production reaching around 175 million bags in 2025 while costs continue to rise due to climate pressures and freight disruptions—the ongoing conflict in the Middle East is adding a new layer of uncertainty to an already fragile supply chain.

Coffee moves through one of the most complex trade networks in the food and beverage sector. Green beans travel from farms across Latin America, Africa and Asia through international ports and maritime corridors before reaching roasters, cafés and consumers. Any disruption to shipping routes, insurance costs or regional logistics can quickly ripple across the industry. For specialty coffee—where freshness, tight margins and long-term sourcing relationships define the business—the impact can be felt even faster.

To understand how the sector is reacting, we spoke with Kim Thompson, Co-Founder  at RAW Coffee Company in Dubai. From monitoring shipments already at sea to preparing technical support systems for cafés, Thompson explains how roasters are navigating rising costs, uncertain logistics and a rapidly shifting geopolitical landscape.

You may like: Oil Surge Could Brew Higher Coffee Prices 

In this conversation, she offers a clear view of what café operators are worrying about right now, how long menu prices can realistically hold, and why the coffee industry’s resilience often comes down to relationships built across the supply chain.

  • Has the “fear factor” kicked in yet? Are you seeing cafés or hotels panic-buying and stockpiling coffee to guard against a potential shortage?

Not really. The reality of the café industry is that most operators are managing week-to-week cash flow, not building strategic stockpiles. Right now the conversations we’re having are far more about cost control than hoarding inventory.

The other factor is freshness. Speciality coffee isn’t a commodity that sits in a warehouse for months. We roast weekly and deliver fresh, so stockpiling doesn’t really fit how quality coffee businesses operate.

Our expectation is that the real response, if there is one, will likely come after Eid al-Fitr, once operators have had time to assess the geopolitical situation and think through their own coping strategies. At the moment, people are watching closely rather than panicking.

  • The coffee you’re roasting today was bought at pre-war prices — how long can you hold your current menu prices before new logistics costs force your hand?

The uncomfortable truth is that price pressure in coffee started well before this conflict. The industry has already been absorbing significant increases at origin, higher processing costs, and rising freight prices for the past two years.

We have already had to adjust pricing once, simply because the economics of producing high-quality coffee have changed globally.

If shipping routes tighten or logistics costs spike again because of regional instability, there’s only so much the supply chain can absorb. Roasters can cushion the impact for a period of time, but eventually the math catches up with everyone.

Coffee has historically been underpriced for the amount of work and risk involved in producing it. What we are seeing now is the global market slowly correcting that reality.

  • Are there specific “origins” or specialty grades that are now effectively “cut off” due to their transit routes through the conflict zone?

At the moment nothing is completely cut off, but logistics has become far more complicated overnight.

We currently have multiple containers on the water and are actively tracking them while exploring alternative routing options that avoid the Strait of Hormuz.

In many ways it feels like a return to the early COVID-19 playbook—scenario planning, contingency routing, and leaning heavily on relationships across the supply chain to keep things moving.

The specialty coffee industry is surprisingly resilient because it’s built on long-term relationships with producers, exporters and logistics partners. When things get unpredictable, those relationships become incredibly valuable.

  • What’s the plan for equipment and spare parts? Is there a risk that a broken espresso machine could stay down because of shipping delays?

Equipment supply is definitely something we’re watching closely, but fortunately we forecasted and planned ahead. We have several containers on the water carrying both commercial and domestic machines, so supply may get tight but we’re not walking into this empty-handed.

More importantly, we have invested heavily in our technical infrastructure. We run a full in-house service department with extensive spare parts inventory, qualified technicians, and swap-out machines available for our commercial partners.

In practical terms, if a café’s machine goes down, we’re structured to keep them operating. The bigger challenge in this industry is rarely the machine itself—it’s the global logistics that sit behind everything.

Oil Surge Could Brew Higher Coffee Prices

Dubai – Qahwa World

Rising oil prices linked to escalating tensions in the Middle East are raising fresh concerns across the coffee sector, with vendors warning that higher fuel costs could eventually translate into more expensive coffee for businesses and consumers.

Crude oil climbed above 90 dollars per barrel on Friday, a level that industry participants say may increase the cost of transporting coffee beans across global supply chains. Because coffee is largely traded internationally and shipped over long distances, higher energy prices can quickly affect freight and logistics costs.

You may like: Vietnam’s Coffee Crisis Could Disrupt Global Supply Chains 

The concern comes only months after the United States removed most tariffs on coffee and several agricultural products last November, a move that had provided temporary relief to importers, roasters and coffee retailers.

  • Shipping Costs Back in Focus

Coffee businesses say transportation costs remain one of the most sensitive factors affecting the price of beans. Any sustained increase in oil prices could raise the cost of shipping green coffee from producing countries to roasting and consuming markets.

Industry observers note that global coffee prices have already been under pressure due to supply challenges in recent years.

According to the World Bank, coffee prices have remained relatively high after adverse weather conditions in several coffee-producing regions reduced harvests and tightened global supply. Earlier expectations suggested that prices might gradually ease this year as production recovered.

However, the recent geopolitical tensions and the accompanying surge in oil prices could introduce new cost pressures, particularly through higher freight rates and supply chain expenses.

  • Uncertain Outlook for Coffee Markets

For coffee retailers and roasters, the coming months may depend largely on how energy markets evolve. Higher fuel costs can affect nearly every stage of the coffee supply chain, from farm transportation and export logistics to international shipping.

While the full impact remains uncertain, market participants say sustained increases in oil prices could add another layer of volatility to an already sensitive global coffee market.