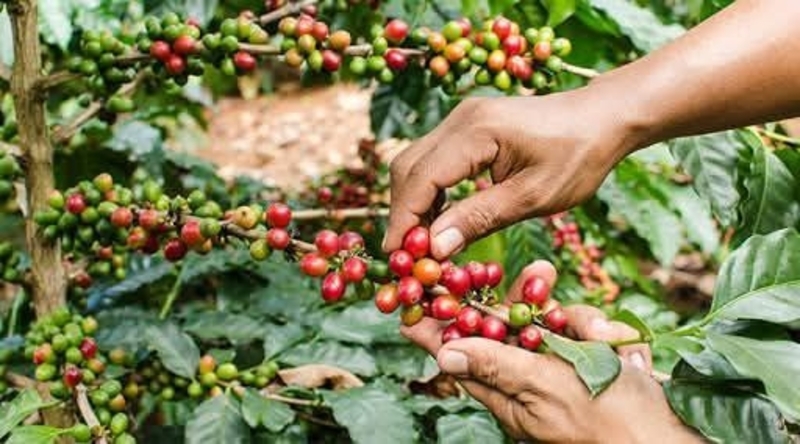
Robusta: A Climate-Resilient Future

Dubai – Qahwa World

As climate change and escalating environmental pressures create unprecedented challenges for global coffee production, the industry is facing a critical turning point that threatens the sustainability of the entire supply chain. In response, World Coffee Research (WCR) is spearheading a massive international effort to develop high-performing, climate-resilient varieties designed to thrive in an increasingly volatile environment. A major strategic shift occurred in late 2025 when WCR integrated Robusta breeding into its Innovea Global Coffee Breeding Network. This expansion recognizes that relying solely on Arabica is no longer a viable long-term strategy in the face of rapid global warming. As a committed member of WCR, Sucafina has expressed its pride in supporting this essential research, emphasizing that investing in variety development is the only definitive way to safeguard the future of coffee and secure the livelihoods of millions of farmers who form the backbone of the industry.

Coffee-growing conditions worldwide are undergoing forced evolution, requiring farmers at origin to adapt to weather patterns that no longer follow traditional predictability. Additionally, they must battle new strains of pests and diseases that thrive in rising temperatures. Strengthening the long-term resilience of the coffee supply has become a top priority, as high-performing varieties act as a vital shield, helping farmers mitigate climate stress while ensuring reliable, high-quality yields. However, the industry faces a significant temporal challenge: the process of developing, scientifically testing, and commercially releasing a new variety typically spans several decades—a timeframe the world cannot afford given the acceleration of climate change. Addressing these challenges requires practical, long-term collaboration, which is the core mission of WCR as an industry-driven research organization dedicated to identifying and developing the coffee varieties of tomorrow.

The launch of the Innovea program in 2022 marked a revolution in coffee breeding, designed to accelerate development by uniting national research institutes, governments, and the private sector across 11 countries in Latin America, Africa, and Asia. Operating under standardized trial protocols, the network coordinates breeding efforts on a global scale, testing candidates across diverse soils, climates, and disease pressures. By pooling massive datasets and cross-border expertise, promising varieties are identified far more rapidly than through traditional methods, while ensuring they are perfectly suited for local farming systems. This innovative approach received global acclaim when Innovea was named one of TIME’s Best Inventions of 2025, recognizing its power to provide tangible solutions to one of agriculture’s most complex challenges.

Vern Long, CEO of WCR, explains that the program’s structure allows for a step change in variety performance faster than ever before, shortening development timelines from 30 years down to just eight. As climate challenges intensify, a continuous global pipeline of improved varieties will provide farmers with the tools needed to reduce risk and stabilize their income. Historically, breeding efforts focused almost exclusively on Arabica, despite the rise of Robusta, which now accounts for approximately 40% of global production. This shift is driven by Robusta’s natural heat tolerance and market dynamics. Robusta possesses greater genetic diversity than Arabica, yet its breeding is more complex as it cannot self-pollinate, requiring sophisticated management of parent plants. By late 2025, Robusta was fully integrated into the Innovea network, bringing in major producers like Vietnam and Ghana alongside enhanced programs in India, Indonesia, Rwanda, and Uganda. Together, these nations represent 64% of global Robusta production. The ultimate goal is to move these varieties from the lab to the field, evaluating thousands of candidates to identify the best performers that will secure a stable and sustainable foundation for the future of coffee.
The Coffee Leaf’s Second Life

By Dr. Steffen Schwarz, Coffee Consulate

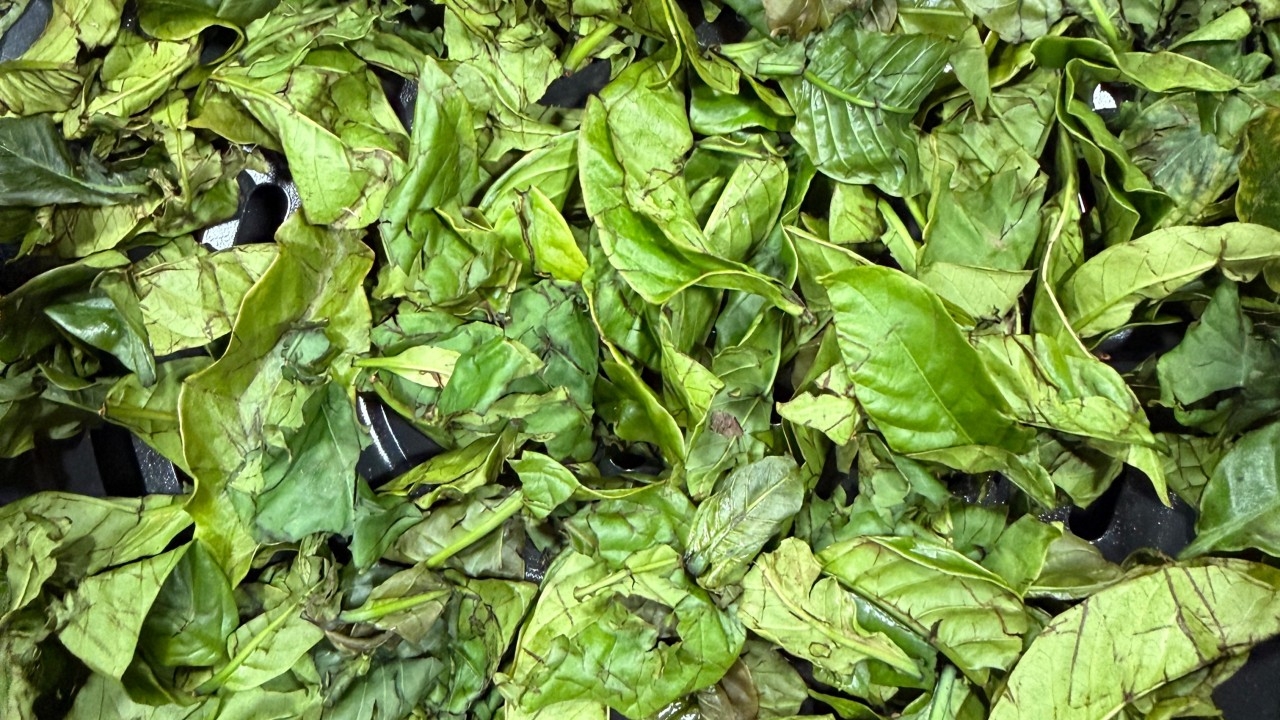
There is a peculiar irony in the coffee business: we have spent more than a century perfecting how we roast, grind, extract, foam, chill, carbonate, nitrogen-infuse and brand a seed, while the plant that produces it has been standing all along as a far larger, greener biomass—photosynthesising, defending itself, interacting with shade trees, fungi and insects, and repeatedly regenerating its canopy after pruning. The leaf is the coffee plant’s true working organ: an engine of carbohydrates and a chemical laboratory that negotiates sunlight and drought, pests and pathogens, growth and recovery. And yet, in most producing countries, coffee leaves have been treated as little more than compost, mulch, or a nuisance swept aside during canopy management. That is now changing, and not simply because the world enjoys novelty. Coffee leaf tea is emerging at the intersection of ethnobotany and modern food law, of phytochemistry and sensory design, and—most importantly for decision makers—of farm economics and operational resilience.

Coffee leaf infusions are not an invention of the wellness era. They are older than espresso, older than filter coffee, older than the first international coffee prices. In several coffee-producing regions, leaves have long been infused, decocted, mixed with milk, or combined with spices and herbs to create beverages that sit somewhere between nourishment, social ritual and folk medicine. The scientific and cultural value of this heritage is easy to underestimate, especially if one’s mental map of coffee begins at the port and ends at the café. Yet the ethnographic record is clear: leaf-based coffee drinks have been prepared and consumed in places as varied as Ethiopia, South Sudan, Indonesia, Jamaica and India, often under local names that signal not a substitute for coffee, but a beverage category of its own.

In Ethiopia, coffee leaf brew is widely known in multiple regions and languages—Chemo, Kuti, Hayta Tuke, Kitel Buna—each name carrying the weight of daily habits and community meanings. The leaves are not merely steeped; they are processed through cleaning, crushing or chopping, boiling, spicing, straining, serving. The result is a drink that can be mild or intense, pale gold or deep brown, lightly herbal or richly aromatic, depending on leaf maturity, drying, brewing time, and the chosen constellation of botanicals.

One of the most detailed recent documentations of these practices comes from the Gofa Zone in South Ethiopia, where Eyasu Yohannis and colleagues recorded indigenous coffee leaf brew and a related preparation called Engere, a blend of coffee leaf brew and cow’s milk. Their work does something crucial for our industry: it moves the conversation away from vague stories of “traditional use” and towards measurable patterns of ingredients, processes and consumption. In their community-based survey, the authors found that coffee leaf brew is not an occasional curiosity; it is embedded in daily life. A majority of respondents described it as a staple, stimulating beverage, while others linked it explicitly to medicinal value and cultural ceremonies. Engere, meanwhile, occupies a different functional niche: it is widely perceived as strength-enhancing, supportive for physically demanding work, and beneficial for lactating women, postpartum recovery and stamina.

The brewing practices described in Gofa are remarkably concrete. Coffee leaves are harvested by cutting terminal portions of the plant—precisely the same anatomical zone that farm managers already target in canopy control—then cleaned and washed, crushed with mortar and pestle or a traditional wooden grinder, and boiled in water typically in the range of 85–100 °C. The documented spice and herb palette is extensive—Ruta chalepensis, coriander fruit, garlic leaf, ginger, basil, lemongrass, chilli, Ethiopian cardamom, fennel, salt—an aromatic architecture that resembles a culinary broth more than a minimalist tea. This matters because it tells us that coffee leaf beverages in their indigenous context have already undergone centuries of consumer testing: bitterness has been managed, aroma has been amplified, mouthfeel and perceived warmth have been engineered through botanical synergy.

For modern markets, this ethnographic depth is more than storytelling. It is a starting point for applied product development. The Gofa data reveal three distinct brewing logics: a combined boiling method where leaf and minor ingredients meet in one pot; a separated boiling method where components are brewed individually and combined later; and a leaf-only approach used particularly for Engere without added botanicals. These are, essentially, three different extraction strategies.

This is where Europe enters the narrative in a decisive way. Coffee leaf infusion is no longer merely an indigenous beverage; it is now a legally defined food category within the European Union. On 1 July 2020, the EU authorised the placing on the market of infusion from coffee leaves as a traditional food from a third country through Commission Implementing Regulation (EU) 2020/917. The regulatory framing is not trivial. By treating coffee leaf infusion as a traditional food under the Novel Food Regulation, the EU effectively acknowledged that a long history of safe consumption outside Europe can form part of a safety argument.

For coffee businesses, EU authorisation changes the strategic landscape. It reduces regulatory uncertainty for importers, roasters and beverage developers. It invites investment in leaf supply chains, not only for niche “novelty teas” but for scalable beverage categories: ready-to-drink formats, sparkling botanical blends, functional infusions, cold brews, and milk-based variants.

The scientific literature suggests that coffee leaves are not simply “coffee without beans”. They contain a complex set of phytochemicals, including phenolic compounds with antioxidant capacity and bioactivities that have been discussed in relation to anti-inflammatory and antihypertensive effects. A crucial commercial insight lies in caffeine itself. Many consumers want the ritual and complexity of coffee-like beverages, but with less stimulant load. Coffee leaf infusions typically contain caffeine, but the overall experience can be positioned differently from espresso-driven intensity.

However, no beverage category survives on sensory novelty alone. The deeper business relevance of coffee leaf tea lies in what it can do at origin. For decades, the coffee sector has discussed farmer income, price volatility, and the fragility of livelihoods. Coffee leaf tea, if commercialised responsibly, can shift part of this debate into operational economics: it can create an additional product stream from the same farm, using a biomass that is already generated in canopy management. That is not merely “extra income”; it is income diversification, and diversification is one of the most reliable ways to increase resilience in agricultural systems.

If we approach coffee leaf tea with the seriousness it deserves—honouring its origins, applying rigorous process science, designing compelling sensory styles, and building supply chains that reward farmers for better agronomy—we will not merely sell another beverage. We will create a mechanism through which coffee farms can become more stable employers, more productive agricultural systems, and more resilient businesses. In a world where coffee’s future is increasingly shaped by climate stress and economic uncertainty, a leaf may seem like a small thing. But in biology and in business, small things are often the levers that change the whole system.

Arabica Coffee Gains on Technical Support Amid Mixed Market Performance

Dubai – Qahwa WORLD

March Arabica coffee (KCH26) concluded Monday’s session with a gain of +1.00 (+0.30%), while March ICE Robusta coffee (RMH26) saw a notable decline, closing down -84 (-2.04%) at a four-week low. The market showed a mixed performance as substantial rainfall in Brazil improved yield prospects but pressured prices. Somar Meteorologia reported that Minas Gerais, Brazil’s premier Arabica region, received 69.8 mm of rain during the week ending January 30, representing 117% of the historical average.

Further weighing on the market, Brazil’s crop agency, Conab, recently increased its 2025 total coffee production forecast by 2.4% to 56.54 million bags. Meanwhile, Robusta prices faced significant headwinds from surging exports in Vietnam, the world’s top Robusta producer. Official statistics from January 5 indicated a +17.5% year-over-year jump in Vietnamese coffee exports to 1.58 MMT. Production for the 2025/26 cycle in Vietnam is projected to rise +6% to 1.76 MMT, a four-year high, with Vicofa suggesting a potential 10% increase if weather remains favorable.

The recovery of ICE-monitored inventories has also exerted downward pressure on prices. Arabica stocks climbed to a 3.25-month high of 461,829 bags in early January, recovering from a multi-year low recorded in November. Similarly, Robusta inventories reached a two-month high of 4,662 lots last Monday. On the supportive side, Cecafe reported an -18.4% decline in Brazil’s December green coffee exports, with Arabica shipments down -10% and Robusta exports falling sharply by -61%.

Globally, the International Coffee Organization noted a marginal -0.3% decrease in exports for the current marketing year. However, the USDA’s Foreign Agriculture Service predicts record global production of 178.848 million bags for 2025/26, a +2.0% increase. This forecast anticipates a -4.7% drop in Arabica output alongside a +10.9% surge in Robusta production. Ending stocks for the 2025/26 period are expected to decline by -5.4% to 20.148 million bags.

Climate Innovation Takes Center Stage at 7th African Coffee Scientific Conference

Addis Ababa – Qahwa World × Buna Kurs

Following yesterday’s high-level policy commitments, the focus of the Third African Coffee Week shifted today from the corridors of power to the laboratory and the field. Scientists, researchers, and agronomists gathered at the Skylight Hotel for the 7th African Coffee Scientific Conference, under the theme “Climate-Resilient Coffee: Innovation for a Sustainable Future”.

While Day One established the policy framework for the continent, Day Two provided the scientific “how-to,” focusing on breeding, pest management, and the institutionalization of African coffee research.

A New Era for Robusta: The Regional Breeding Network

A major highlight of the morning session was the formal launch of the Robusta breeding network, a collaborative initiative involving Ghana, Uganda, and Rwanda. Led by Robert Kawuki, the network aims to modernize breeding efforts for a variety that is increasingly seen as a cornerstone of climate adaptation due to its relative heat tolerance compared to Arabica.

The session, moderated by Dr. Geofrey Arinaitwe, also delved into the genetic foundations of Ethiopian coffee. Researchers Natol Bakala and Wakuma Merga presented findings on the genetic diversity of “Laage” coffee landraces, emphasizing that preserving Ethiopia’s unique genetic reservoir is critical for the global coffee industry’s survival.

Science-Driven Adaptation and Pest Management

As climate change shifts ecological zones, the conference addressed the alarming migration of pests and diseases. Kifle Belachew Bekele presented a critical study on why Coffee Leaf Rust (Hemileia vastatrix) has begun migrating to highland Arabica growing areas in Ethiopia—territories previously considered “safe” due to their altitude.

Other scientific breakthroughs discussed included:

  • Disease Resistance: Admikew Getaneh shared research on the phytochemical basis of resistance to Coffee Wilt Disease, while Monyo Grace presented new F1 hybrid genotypes resistant to Coffee Berry Disease.

  • Eco-Innovation: Mariamawit S. Kassa explored “Beyond the Brew,” highlighting the hidden potential of spent coffee grounds, while Mohammed Aman discussed using the Desmodium plant for sustainable production.

  • Pest Control: Innovative “locally made” traps for the Black Coffee Twig Borer in Northern Tanzania were showcased by Aden Mbuba as a low-cost, high-efficiency solution for smallholders.

Institutionalizing Knowledge: The African Coffee Research Center

The afternoon session marked a pivotal moment for the continent’s intellectual infrastructure. The Inter-African Coffee Organisation (IACO) and the African Coffee Research Network (ACRN) announced the establishment of the African Coffee Research Center. This center is designed to be the “brain” of the continent’s coffee sector, ensuring that the research presented today translates into scalable field solutions.

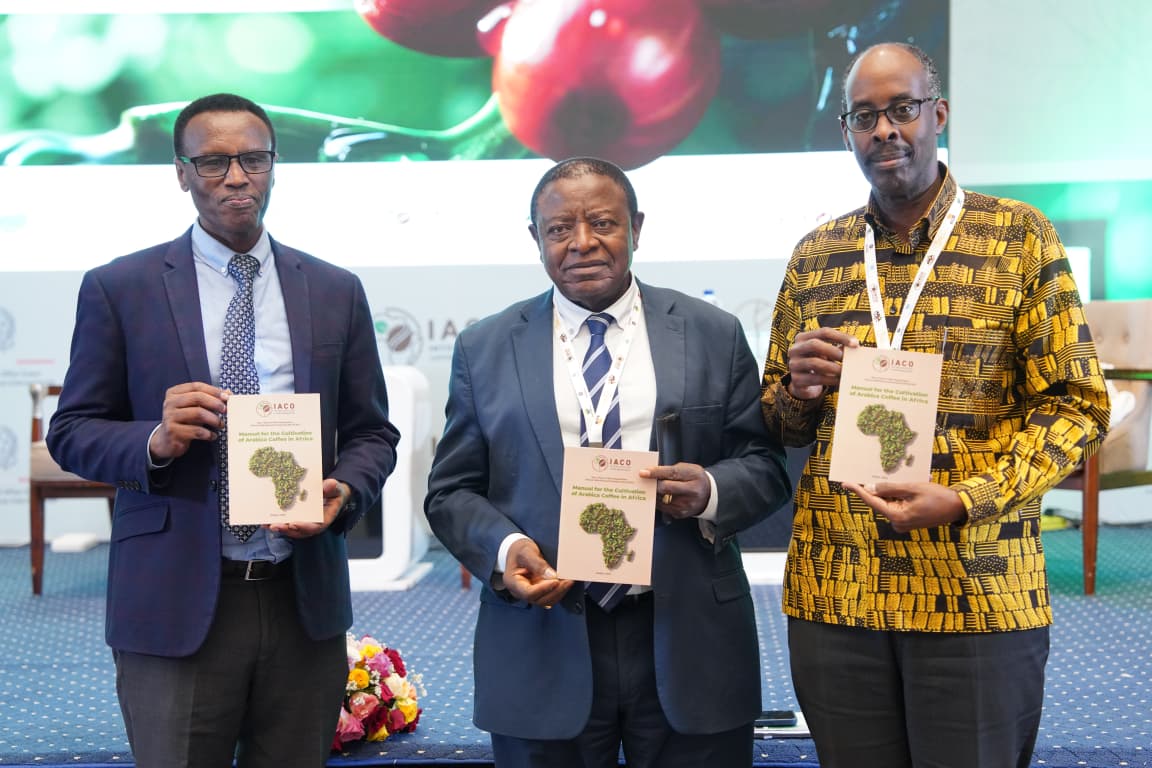
To wrap up the day’s proceedings, the Secretary General of IACO and the Chairperson of the ACRN officially launched the new coffee manual, a comprehensive guide intended to harmonize best practices across Africa’s diverse coffee-growing regions.

The conference concluded with closing remarks from the IACO Chairman, signaling a transition from scientific theory to a unified, continental implementation strategy.

Peru Hits Record Coffee Sales of Over $1.5 Billion in 2025

Dubai – Qahwa World

Peru’s coffee industry reached an unprecedented historical milestone in 2025, with the latest official data from the Ministry of Agrarian Development and Irrigation (MIDAGRI) reporting record-breaking sales of $1.57 billion between January and November. This figure represents a staggering 54.1% year-on-year growth compared to the same period in the previous year, firmly positioning the coffee sector as one of the most vital pillars of the Peruvian national economy over the last decade.

This exceptional success is the result of Peru’s long-term strategic commitment to solidifying its status as the world’s leading producer and exporter of organic coffee. This commitment has perfectly aligned with a major shift in global consumer behaviour, where buyers are increasingly prioritising sustainable, eco-certified, and ethically sourced crops. Furthermore, favourable international prices for high-value speciality coffee lots played a decisive role in maximising financial returns. Peruvian exporters have successfully navigated and met the rigorous quality standards and strict traceability requirements demanded by major strategic markets, most notably the United States and the European Union.

Field reports indicate that this growth was not accidental but the product of intensive investment in improving logistical supply chains and advancing post-harvest processing technologies within the rugged Andean highlands. This prosperity has had a direct and tangible impact on the national income, significantly enhancing the livelihoods of more than 223,000 farming families across the Andes and the Amazon rainforest. In these regions, coffee cultivation serves as the primary socioeconomic lifeline and a fundamental social pillar for rural communities. Building on these historic results, the Peruvian government now aims to leverage this momentum to further promote regional brands in international forums and ensure the long-term sustainability of these record-breaking figures in future seasons.

Coffee Prices Sink as Brazil Rainfall Outlook Improves

Dubai – Qahwa World

Coffee futures faced a sharp retreat on Friday, with Arabica falling -13.25 (-3.85%) to a five-and-a-half-month low, and Robusta sliding -66 (-1.58%) to a three-and-a-half-week low. The primary downward pressure stems from weather forecasts predicting steady, beneficial rains over the next week in Minas Gerais, Brazil’s premier coffee-growing region.

The bearish sentiment is further reinforced by an ample supply outlook. Brazil’s crop agency, Conab, recently raised its 2025 production estimate to 56.54 million bags, a 2.4% increase from previous forecasts. Simultaneously, Vietnam—the world’s top Robusta producer—reported a 17.5% year-over-year surge in 2025 exports, reaching 1.58 MMT. Vietnam’s 2025/26 output is projected to climb another 6% to a four-year high, potentially reaching 10% growth if favorable weather holds.

Inventory recoveries at the Intercontinental Exchange (ICE) have added to the price pressure. Arabica inventories rose to a two-and-a-half-month high of 461,829 bags in mid-January, while Robusta inventories hit a seven-week high of 4,609 lots last Friday.

However, some factors continue to provide underlying support. Cecafe reported that Brazil’s December green coffee exports dropped 18.4% to 2.86 million bags, with Robusta exports specifically plummeting 61%. Additionally, while rains are forecasted, recent data shows that Minas Gerais received only 53% of its historical average rainfall in mid-January.

Looking ahead, the USDA’s Foreign Agriculture Service projects record global production of 178.848 million bags for 2025/26. While Arabica production may see a 4.7% dip, a significant 10.9% increase in Robusta output is expected to drive global totals to new heights, even as global ending stocks are forecasted to tighten slightly.

Africa’s Coffee Leaders Launch Climate Transformation Plan in Addis

Addis Ababa – Qahwa World × Buna Kurs

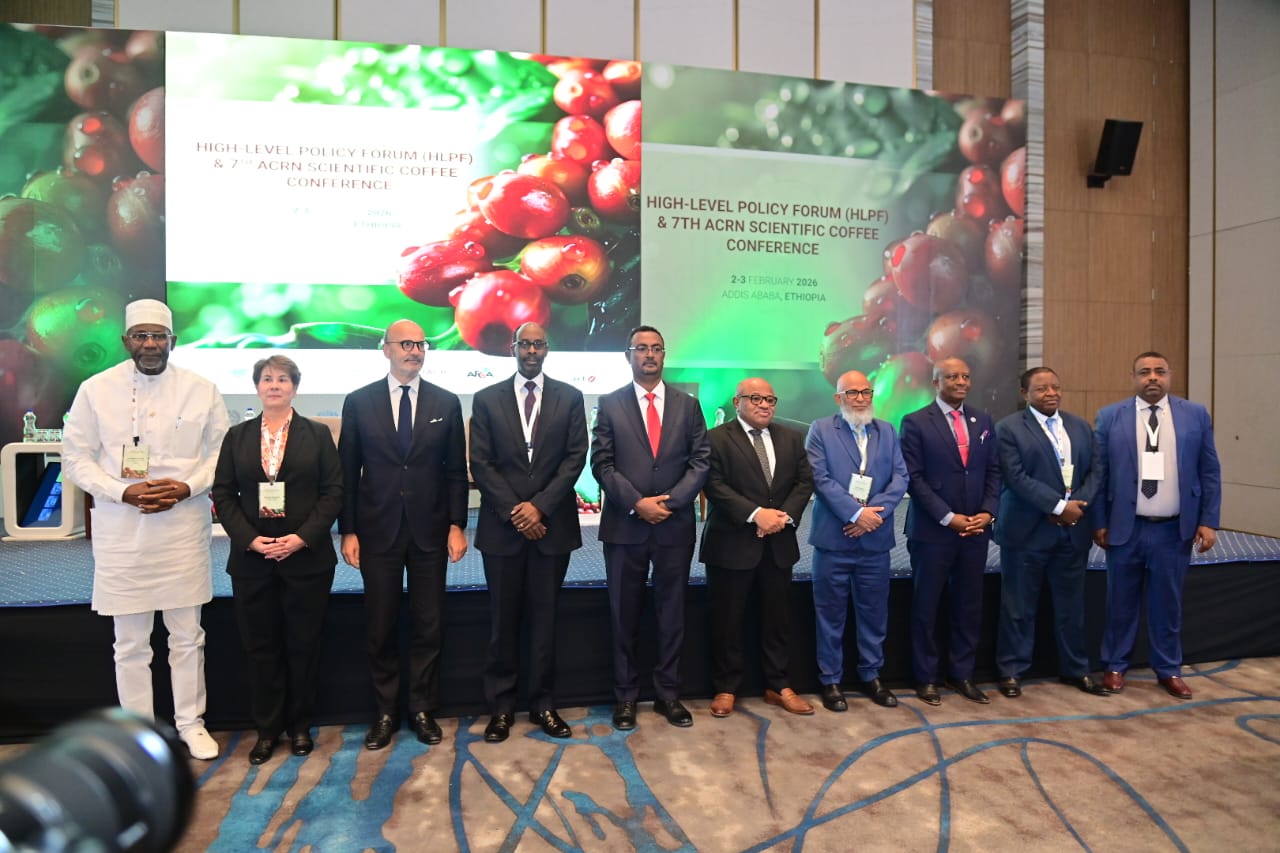
African governments, international institutions, and private sector leaders convened today in Addis Ababa for the High-Level Policy Forum held during the Third African Coffee Week. The assembly issued a strong call for coordinated action to safeguard the future of Africa’s coffee sector amid escalating climate and market pressures.

Organized by the Inter-African Coffee Organisation (IACO)—the African Union’s specialized agency for coffee—in collaboration with UNIDO, the Forum is being held under the theme: “Advancing Climate Resilience and the Transformation of the African Coffee Sector.” The event, hosted at the Skylight Hotel, brings together ministers, ambassadors, development partners, regulators, researchers, and industry executives from across Africa and beyond.

In the opening session, senior representatives of the Ethiopian government, IACO member states, the African Union, UN agencies, and international partners underscored the strategic importance of coffee to Africa’s economies and export earnings. While coffee supports millions of smallholder farmers across the continent, it faces growing risks from climate change, regulatory shifts, and limited local value addition.

The High-Level Policy Forum is anchored in the ACT Programme (Advancing Climate-Resilience and Transformation of the African Coffee Sector), a continental framework structured around five key pillars:

  1. Climate resilience

  2. Value addition and industrial transformation

  3. Compliance with international market standards

  4. Research, innovation, and knowledge sharing

  5. Social inclusion and sustainable livelihoods

Day One discussions focused on five outcome-oriented policy panels, each aimed at producing actionable recommendations and investment pathways:

  • The First Panel addressed social inclusion, emphasizing the need to place farmers, women, and youth at the center of sector transformation. Speakers highlighted inclusive business models, access to finance, and skills development as essential to long-term resilience in coffee-growing communities.

  • The Second Panel examined value addition, noting that Africa still exports the majority of its coffee as green beans. Panelists discussed the investments needed to expand local processing, roasting, and branding, specifically looking at opportunities under the African Continental Free Trade Area (AfCFTA).

  • The Third Panel was dominated by climate resilience and adaptation. Experts outlined climate-smart production systems, agroforestry, and the role of climate finance in supporting smallholder farmers, stressing that adaptation must move from pilot projects to scalable, financed solutions.

  • The Fourth Panel focused on research and innovation, calling for the integration of scientific data and digital tools into policymaking. Regional collaboration and South–South knowledge exchange were identified as key enablers of quality improvement.

  • The Final Panel addressed market access and compliance, with particular attention to the European Union Deforestation Regulation (EUDR). Speakers discussed traceability systems and how harmonized African standards can transform compliance from a barrier into a competitive advantage.

The day concluded with the official launch of the African Coffee Sustainability Standards, led by the African Organisation for Standardisation (ARSO)—a milestone aimed at strengthening market access and regulatory alignment for African producers.

The High-Level Policy Forum continues tomorrow, focusing on consolidating policy recommendations and partnership commitments under the ACT Programme.

US Coffee Market: The End of a Monopoly

Dubai – Qahwa World

The United States retail sector in 2026 is undergoing a radical economic shift that financial market analysts describe as the “loosening of the caffeine grip”. While Starbucks dominated the “third place” concept for decades, it now finds itself trapped between two forces: the Chinese technological expansion of Luckin Coffee and the rise of Yemeni coffee empires that have restored the soul of the original product—most notably Qamaria, Qahwah House, and Haraz. This report reveals through figures and field analysis how the green giant’s market share has declined from 52% in 2023 to 48% today.

  • The Triangle of Authenticity and the Erosion of Luxury

Starbucks committed a major strategic error by pivoting toward full automation and reducing seating areas to accelerate digital orders. This cultural vacuum was brilliantly filled by high-end Yemeni coffee houses, led by Qamaria, Haraz, and Qahwah House.

The Economics of Authenticity at Qamaria: Yemeni coffee is no longer just a niche beverage; it has transformed into a luxury brand. In Qamaria branches stretching from Michigan to Manhattan and California, the price of a cup—sourced from rare mountain strains—reaches $9. Nevertheless, consumers stand in long lines. The value added here is the “story and ritual”, something missing for the Starbucks customer who now feels they are buying from a factory rather than a café.

Restoring the Social Dimension: While major chain branches have turned into rapid “pickup stations”, Qamaria and its peers have revived the concept of the café as a social and cultural hub. Field data indicates that the average customer dwell time in these cafes is 40% longer than in traditional chains. This boosts sales of secondary products such as traditional sweets, dates, and private blends, supporting a higher average transaction value.

  • Chinese Tech Expansion and Cost Efficiency

From the other side, Starbucks faces an existential technological threat coming from China, as Luckin Coffee began an aggressive expansion in major US cities using the “Smart Mini-Store” model.

Cost Analysis: This model relies on rental spaces 60% smaller than traditional stores, with minimal human staff. This efficiency has allowed them to provide coffee of competitive quality at a price 25% lower, attracting the younger generation looking for fast, digitally programmed caffeine.

Algorithms vs. History: While American chains rely on their history, Chinese startups rely on demand-prediction algorithms. This reduces waste by 15% and increases service speed, placing legacy chains in the category of “bloated corporations”.

  • Market Saturation and the Supply Surplus Dilemma

Retail experts point to a bitter reality: there is too much coffee and too little distinction. With more than 34,500 chain-affiliated cafes in America, the market has reached a point of complete saturation.

The Rise of Drive-Thru: Drive-thru chains are no longer just kiosks; they have turned into massive profit engines thanks to their absolute specialisation in speed. This sector has syphoned off the “rushed” customers from major chains, who represent 60% of morning traffic.

Operational Inflation: The year 2026 saw a 12% increase in labour wages and an 8% rise in commercial real estate rents. For chains with large branches, this was a painful blow to profit margins, while Yemeni cafes like Qamaria were better able to absorb costs due to their premium pricing aimed at the elite.

  • Is the Era of the Single Pole Over?

Starbucks’ attempts to add 25,000 seats and launch smaller-format stores are seen by analysts as a late attempt to repair its identity. The problem is not the number of seats but the loss of specialisation.

The success of Qamaria and Haraz proves that the American consumer in 2026 has become “brand-agnostic”. They seek authentic Yemeni coffee on weekends for social connection, choose fast tech-driven coffee while heading to work, and only return to traditional chains when specialised alternatives are unavailable.

  • Economic Conclusion

We are witnessing the end of the “Universal Platform” era. The US coffee market today is shaped by two poles: the cultural quality pole (led preeminently by Yemen) and the technological efficiency pole (led by China and drive-thru chains). As for traditional powers, they are struggling to survive in the “middle”—the most dangerous place in modern retail economics, where price advantage is absent and cultural authenticity fades.


This report is based on performance data analysis for the period 2024–2026, periodic financial reports, and a field survey of the growth of Qamaria, Qahwah House, and Haraz branches in Michigan, New York, Texas, and California, in addition to National Coffee Association data on new American consumption patterns.


African Coffee: Re-Engineering the 2026 Global Market

Dubai – Qahwa World

At a time when global commodity markets are reeling from extreme climate volatility hitting traditional production belts in Brazil and Vietnam, the African continent has emerged in the 2026 season as an indispensable strategic player. This year is more than just a bountiful harvest; it represents a geopolitical turning point in the coffee sector. Africa has successfully bridged a critical global production gap, preventing Arabica and Robusta prices on international exchanges from reaching catastrophic inflationary levels.

  • The Angolan Renaissance

The Angolan experience deserves careful analytical scrutiny. Having invested heavily in its coffee sector over recent years, Angola is no longer a marginal player in 2026. It has become a primary alternative supplier of high-quality Robusta. Land reclamation in regions such as Uíge has not been limited to farming; it included the commissioning of modern centralised processing units that significantly reduced post-harvest losses. This production surge has provided international roasters, particularly in Russia, with a “third option” shielded from the fluctuations of the Vietnamese market, benefiting from preferential shipping rates through recently modernised Atlantic ports.

  • Deciphering the Figures

Looking at raw data, Uganda has achieved an extraordinary milestone with exports nearing 7.05 million bags. This growth, exceeding 50% in certain annual periods, is a direct result of “agricultural intensification” policies and the distribution of high-yield seedlings. In Ethiopia, surpassing the 11 million bag mark amidst logistical challenges is an economic feat. In-depth analysis suggests that Ethiopia capitalised on a “quality premium”. While global Arabica prices surged, Ethiopia offered premium strains with moderate price increases of approximately $2 per kilogram compared to last year—a cost absorbed by quality-hungry markets, providing vital foreign exchange to support the Ethiopian trade balance.

  • Free Trade Logistics

Beyond the farms, a revolution is taking place in supply routes. In 2026, the African Continental Free Trade Area (AfCFTA) began leaving a concrete mark by reducing customs barriers between origin countries and ports. Previously, transit complexities inflated final costs unjustifiably. Today, thanks to digital coordination and standardised procedures, there has been a significant reduction in cross-border transport costs. This logistical saving is the true driver behind African exporters’ ability to offer competitive prices in the Russian market, ensuring African coffee reaches roasting facilities in Moscow and Saint Petersburg with high efficiency and freshness, despite global inflationary pressures.

  • Sustainability as an Economic Shield

African coffee in 2026 is acquiring the status of a “safe haven” for investors. Strains planted in Kenya and Tanzania have shown increased resistance to plant diseases and water scarcity. Economically, this translates to long-term stability. International roasters signing futures contracts with these origins are guaranteed supply continuity, insulated from the recurring climate shocks seen in Latin America. Today, Africa is not just selling its harvest; it is selling “sustainability” as a value-add in a turbulent global market.


Note: This analytical reading is based on Q1 2026 performance indicators and preliminary data issued by coffee development authorities in origin countries (such as UCDA and ECTA), taking into account Intercontinental Exchange (ICE) fluctuations and futures contracts reflecting growing confidence in the African crop’s ability to balance global supply and demand.


Irina Sharipova: Coffee in its Purest Form

We are delighted to launch our new column at “Qahwaworld.com” titled “QAHWATI” – My Coffee – where we step into the private worlds of celebrities and coffee enthusiasts to discover the secrets of their relationship with this magical drink.

In the “Qahwati” series, we aim to pull back the curtain on the personal lives of industry experts and connoisseurs.

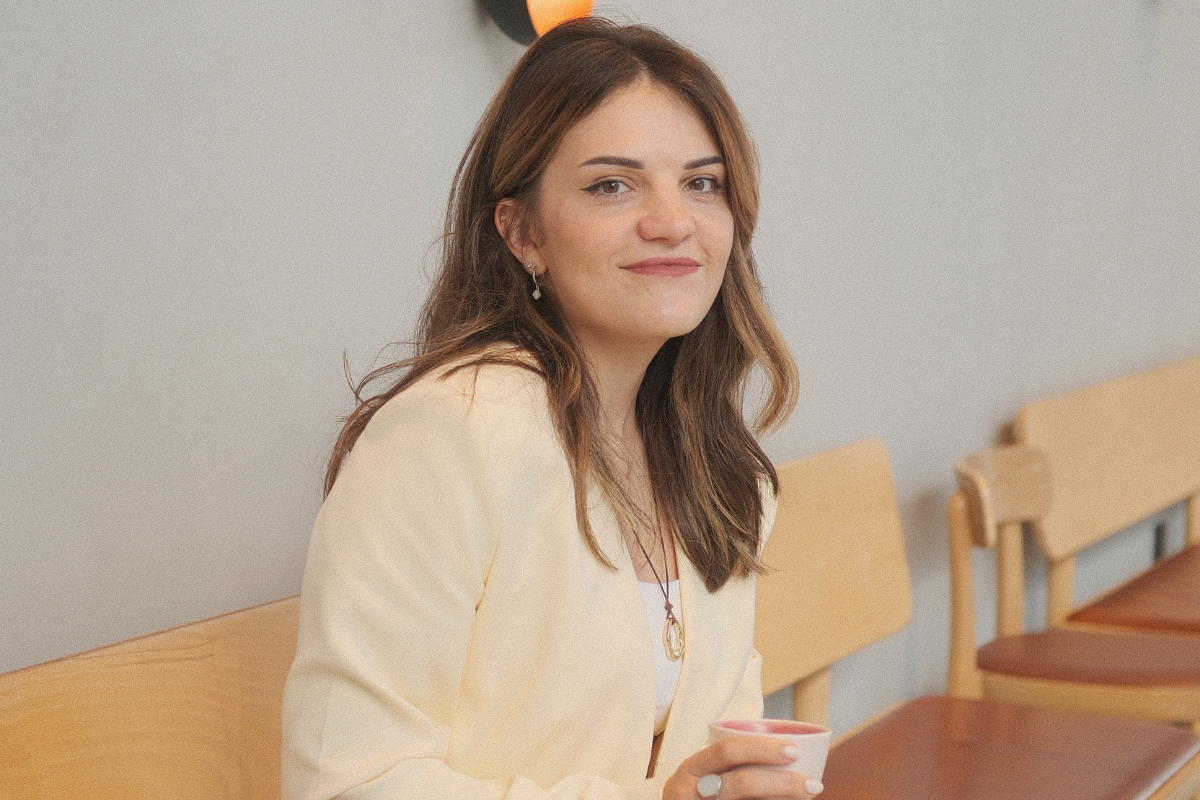
To kick off this series today, we host the renowned certified coffee trainer and expert Irina Sharipova in a moment of serenity, far from training platforms and strict evaluation standards.

For Irina, coffee isn’t just a science or a set of rules; it is a daily ritual that begins with simplicity and ends with exploration. Here, she shares how a professional expert spends her morning, balancing the consistency of batch brew with an endless passion for manual experimentation.

Irina says: “I really like making coffee at home My perfect coffee is batch brew. I honestly love it for its simplicity and balance. When batch brew is done right, it’s clean, smooth, and easy to drink.  I mostly brew with my Moccamaster. It’s reliable, consistent, and fits perfectly into my daily routine. I enjoy the process: grinding the coffee, filling the water, pressing the button, and letting the aroma slowly fill the space. It feels calm and familiar — exactly what I want in the morning.

Lately, I’ve also been experimenting more with manual brewing, especially using Orea, a new funnel I recently started experimenting with. It’s fun, flexible, and gives me a lot of variables to play. I like brewing different coffees with it and seeing how small changes can completely transform the cup. This kind of experimentation keeps coffee exciting for me and reminds me that learning never really stops.

Aside of work, I usually drink my coffee in the morning or early afternoon, without rushing. Sometimes it’s a quiet moment alone, sometimes it’s shared with conversation. I drink my coffee black — I enjoy tasting the coffee as it is, without distractions.”

Bridging the Gap: An Exclusive Dialogue with Vanusia Nogueira on the Global Coffee Crisis and the Path to 2026

From regulatory hurdles like the EUDR to the volatile C-Market and climate resilience, the Director General of the International Coffee Organization (ICO) outlines a strategic roadmap for a fairer global coffee value chain.

Dubai – Ali Alzakary

The International Coffee Organization (ICO) is the primary intergovernmental body dedicated to fostering a sustainable coffee sector. At its helm stands Mrs. Vanusia Nogueira, a visionary leader whose tenure has been defined by a relentless pursuit of equity for smallholder farmers.

This exclusive interview marks a historic moment—the first dialogue granted by the Director General to an Arabic media outlet. We are profoundly grateful to Mrs. Nogueira for graciously accepting our invitation. Beyond her professional stature, her humility and the sincerity with which she approached this conversation were truly remarkable. In an industry often characterized by formal diplomacy, her transparency and candor provided a clear and honest look at the challenges facing our sector. We are deeply indebted to her for her time, her precision, and the kindness she showed throughout this significant exchange.

  • Now that we are well into 2026, how do you personally see the ICO’s role in helping smallholder farmers cope with regulations like the EUDR and other environmental requirements?

The ICO acts as a vital bridge between producing and consuming nations. With 75% to 80% of global coffee producers being smallholders, our role is to make policymakers understand the ground-level challenges. There is often a lot of good intentions behind regulations, but policymakers and consumers are often unaware of how difficult it is to comply in the field. We educate these stakeholders and bring together partners—governments, development agencies, and the industry—to provide the technical and financial support that vulnerable communities need to make these transitions feasible and viable.

  • Traceability and data systems are becoming unavoidable. How can we ensure these costs don’t end up being paid mainly by small farmers?

We are building partnerships with the consuming side—the industry and governments—to support the infrastructure needed, from geolocations to databases. In many countries, the key issue is internal infrastructure, such as internet access. We are working with partners like the German, UK, and Italian governments to implement these systems. Furthermore, we need to educate consumers on why it is fair to pay a little more. Transparency is essential; we must show that these margins are necessary for producers to survive and thrive.

  • Looking back at 2025, has the industry made progress toward a “living income,” or are we still stuck with the C-Market logic?

Vanusia Nogueira: The sector learned in the past two years that a living income is not just about price. It is about closing gaps in productivity, yield, and infrastructure like healthcare and education. While producers in some regions reached a comfortable level last year due to higher prices, others are still struggling. A key solution is for small producers to stop working in isolation; they must organize into cooperatives or associations to access new markets and technical assistance together.

  • Regarding the climate impact on specific origins—in Yemen, for example, the harvest has become fragmented into multiple stages and quantities are dropping. How do you view this?

The situation in Yemen—where you have three or four harvests from the same tree instead of one—is a clear symptom of climate change that we must analyze deeply. We have seen similar shifts in Brazil. We need to understand if the traditional varieties in Yemen—which is one of the original homes of Arabica—are still suitable for this new climate or if we need to renovate the plantations with more resilient strains. Yemen’s heritage is a global priority, and scientists must work to find solutions that protect its unique productivity.

  • There is a growing debate about responsibility. Are large roasters and traders doing enough today?

I see major roasters and traders working very closely with producing countries on “pre-competitive” actions to address these challenges. I am in constant contact with global industry leaders, and I am confident they are totally open to new solutions and are supporting the initiatives needed to stabilize the sector.

  • How should the sector approach lab-grown and alternative coffee products without losing the value of natural coffee?

Vanusia Nogueira: Communication and clarity are paramount. It must be clear to everyone what is “real coffee” and what is a substitute. Natural coffee has scientifically proven health benefits, whereas the impact of chemical or artificial alternatives is often unmentioned. In countries like Brazil and Vietnam, regulations already exist to ensure that packaging for substitutes cannot claim to be “coffee.” We must continue to express why natural coffee remains superior for health and culture.

  • Price swings have been extreme. What is actually driving this volatility?

It is a matter of a “short blanket”—supply and demand. Severe weather events since 2021—frosts in Brazil, droughts in Vietnam and Africa, and typhoons—have lowered production while consumption is surging, particularly in the Middle East and Asia. We are currently working with AI experts to create models that can better predict these events to help us protect production in the short and long term.

  • Markets like the Middle East are now shaping their own identities. How does the ICO plan to engage with them?

The Middle East is a driver of the industry. Saudi Arabia became an official member of the ICO six months ago, and I visited Riyadh recently to touch base with the situation there. I also heard incredible things about the “World of Coffee Dubai” event two weeks ago—people told me it was a truly “crazy” and amazing event. We need to be present in these markets, working as partners to improve communication and support these maturing consumer bases.

  • What role can consumer regions—including the Arab world—play in supporting producers beyond certifications?

The Arab world can play a strategic role as a “catalytic investor.” Beyond labels, their impact lies in investment, partnership, and system-building. They can help de-risk innovation and climate adaptation at the origin. By supporting logistics, research, and digital agriculture, they can help reshape how value and responsibility are shared across the sector.

  • If you could speak directly to the global sector in 2026, what would you say needs to change most urgently?

Vanusia Nogueira: What needs to change most urgently is how risk and value are distributed. Today, smallholders absorb most of the impact of price volatility and climate change. Coffee must be treated not just as a commodity, but as a global public good. If producers earn a prosperous income, the entire sector becomes resilient. That change cannot wait.

  • Editorial Highlights

“Coffee must be treated not just as a commodity, but as a global public good that supports livelihoods, ecosystems, and cultures.”

“Yemen is the cradle of Arabica; we must ensure that its historic coffee heritage survives the challenges of a changing climate.”

“The ‘World of Coffee Dubai’ was an amazing, high-energy event that proved the Arab world is now a central driver of the global coffee industry.”

“A living income is not just about prices—it is about productivity, healthcare, and education. Doubling prices is not enough if the foundation is missing.”

“We must be clear with consumers: natural coffee has scientifically proven health benefits that chemical substitutes simply cannot match.”

“The Arab world has the power to be a ‘catalytic investor,’ moving beyond labels to truly de-risk innovation at the origin.”


Brazil Rain and Vietnam Surplus Sink Coffee Futures

NEW YORK — Qahwa World

Coffee futures saw a sharp downturn on Friday, with Arabica hitting a five-and-a-half-month low and Robusta dropping to a three-and-a-half-week trough. March Arabica (KCH26) finished the session down 13.25 cents (-3.845%), while March ICE Robusta (RMH26) fell by $66 (-1.58%).

The primary pressure stems from the weather outlook in South America. Forecasts now indicate consistent rainfall across Minas Gerais, Brazil’s premier growing region, for the upcoming week. This shift toward a more favorable moisture profile has dampened the recent rally.

Further bearish sentiment is driven by a bolstered supply outlook. On December 4, Brazil’s Conab increased its 2025 production forecast by 2.4%, now estimating a total of 56.54 million bags. Simultaneously, Vietnam—the world’s top Robusta producer—continues to flood the market. Vietnam’s National Statistics Office noted a 17.5% year-over-year surge in 2025 exports, totaling 1.58 million metric tons. Production for the 2025/26 cycle is expected to climb 6% to a four-year high of 29.4 million bags, with Vicofa suggesting output could rise by 10% if conditions remain optimal.

Market inventories are also seeing a notable recovery. ICE-monitored Arabica stocks rebounded from a nearly two-year low in November to reach 461,829 bags as of mid-January. Robusta stocks followed a similar path, recovering from a one-year low in December to reach a nearly two-month high of 4,609 lots this past Friday.

However, some factors continue to provide an underlying floor for prices. Cecafe reported a sharp 18.4% drop in Brazilian green coffee exports for December, with Robusta shipments specifically tanking by 61%. Furthermore, recent data from Somar Meteorologia highlighted that rainfall in Minas Gerais was recently only 53% of the historical average, while the ICO reported a slight 0.3% dip in global exports for the current marketing year.

Looking ahead, the USDA Foreign Agriculture Service (FAS) projects record global production of 178.848 million bags for 2025/26. While the agency expects a 4.7% dip in Arabica output, a projected 10.9% jump in Robusta production is set to offset those losses. Despite the record harvest, FAS anticipates ending stocks will tighten by 5.4% to roughly 20.15 million bags.