Brazilian Coffee Ends 2025 with Record Revenues Exceeding $15.6 Billion

São Paulo – Qahwa World

In a detailed economic report reflecting major shifts in global commodity markets, the Brazilian Coffee Exporters Council (Cecafé) announced the conclusion of 2025 with an unprecedented financial performance. Despite ongoing supply chain disruptions and geopolitical volatility, Brazil achieved a historic record in coffee export revenues, reinforcing its position as a leading force in the global agricultural economy.

  • Cecafé: The Reference Authority for Data and Policy

The Brazilian Coffee Exporters Council (Cecafé) is the official body representing coffee exporters in Brazil and is responsible for monitoring coffee trade flows to more than 120 countries worldwide. According to Cecafé’s December 2025 report, these exceptional financial results demonstrate the sector’s ability to adapt to global price fluctuations, supported by strategic investments in quality enhancement and value creation for Brazilian coffee in international markets.

  • Financial Performance Analysis: Value Growth Amid Lower Volumes

Based on data analyzed by Cecafé, Brazil’s coffee export revenues reached $15.586 billion in 2025, marking a 24.1% increase compared with the previous year. This figure represents the highest export revenue level in Brazil’s coffee trade history.

Notably, this record revenue was achieved despite a 20.8% decline in shipment volumes. Brazil exported 40.049 million 60-kg bags in 2025, down from more than 50 million bags in 2024. The increase in revenues was driven by a sharp rise in the average export price, which reached $389.17 per bag, up 56.4% year on year. This pricing dynamic allowed exporters to generate higher returns with lower volumes, supporting crop sustainability and helping preserve domestic stocks affected by adverse climatic conditions.

  • A Reshaped Trade Map: Germany Takes the Lead

The year 2025 marked a significant shift in Brazil’s coffee export destinations. According to Cecafé, the United States fell to second place among Brazil’s largest coffee importers, while Germany emerged as the leading destination.

Germany imported 5.409 million bags, representing a 6.1% increase, while U.S. imports declined sharply by 33.9%, totaling 5.381 million bags. Cecafé attributes this contraction in the U.S. market primarily to the imposition of 50% import tariffs on Brazilian coffee during parts of the year, which reduced the product’s competitiveness and redirected volumes toward European and Asian markets.

In parallel, Japan recorded growth of 19.4%, while China posted a 19.5% increase, highlighting the success of Cecafé’s market diversification strategy and its focus on emerging economic powers in Asia.

  • Differentiated Coffees: Driving Qualitative Growth

Cecafé’s report also highlights the strong performance of the “Differentiated Coffees” segment, which includes coffees certified for high quality standards or sustainable production practices. This segment generated $3.525 billion in revenue, accounting for 22.6% of total export earnings.

Although shipment volumes in this category declined by 15.1%, their total value increased by 39.1%. Márcio Ferreira, President of Cecafé, noted that global consumers are increasingly willing to pay premium prices for coffees that ensure environmental and social sustainability—an area in which Brazil has strengthened its position through advanced agricultural technologies.

  • Logistics Challenges: The Cost of Success

Despite the strong financial results, 2025 was not without challenges. Cecafé reported severe logistical constraints at Brazilian ports, particularly at the Port of Santos. According to the report, 55% of vessels experienced schedule delays, disrupting the shipment of thousands of containers each month.

These delays resulted in operational losses amounting to millions of Brazilian reais, driven by demurrage charges and additional storage costs. Cecafé emphasized that improving port infrastructure and ensuring a steady supply of containers are essential to sustaining record export performance in the coming years.

  • Outlook for 2026: Sustainability and Innovation

Cecafé’s December 2025 report concludes with an optimistic outlook led by Marcos Matos, CEO of the Brazilian Coffee Exporters Council. He stated that the “Cafés do Brasil” brand has become a global benchmark, successfully combining large-scale production with environmental responsibility.

According to the report, Brazil—through Cecafé—not only supplies approximately one-third of global coffee demand, but also leads efforts in agricultural digitalization, labor rights protection, and forest conservation, positioning Brazilian coffee as a reliable and sustainable choice for the future.

  • Conclusion

Generating more than $15.6 billion in export revenues in a single year is not merely a statistical milestone, but a clear indicator of the strength and global standing of Brazilian coffee. It also underscores the central role played by the Brazilian Coffee Exporters Council (Cecafé) in guiding the sector toward new levels of financial and professional achievement.
Coffee Prices Rise Amid Brazilian Heatwave and Supply Pressures

Dubai – Qahwa World

Coffee markets are seeing an upward shift in prices, driven by weather events in key production regions and tightening global supplies.

March arabica futures rose 1.26%, while ICE robusta for January had previously gained 1.06% before the holiday closure. The Brazilian coffee belt is experiencing a heatwave forecasted to last through Monday, putting pressure on crops and supporting prices.

Additional factors are influencing the market. In Indonesia, recent floods have affected roughly one-third of northern Sumatra’s arabica plantations, potentially cutting the nation’s coffee exports by up to 15% in the 2025-26 season. Robusta production has been less impacted. Indonesia remains the third-largest robusta producer worldwide.

Meanwhile, Brazil’s Minas Gerais region received rainfall during the week ending December 19 that was below average, according to Somar Meteorologia. Reduced precipitation in key growing areas can add bullish pressure on arabica coffee.

Coffee inventories also play a role in market dynamics. ICE-tracked arabica stocks hit a 1.75-year low of 398,645 bags in November before rising to 456,477 bags recently. Robust a inventories similarly fell to near 12-month lows before modest recovery.

US demand for Brazilian coffee remains restrained. Tariffs previously imposed on imports led to a 52% drop in purchases from August to October compared to the previous year. Although tariffs have since eased, US stock levels remain limited.

On the supply side, Brazil’s national crop agency Conab raised its 2025 production estimate to 56.54 million bags, up from 55.20 million in September, signaling an ample supply outlook.

Robusta coffee faces downward pressure amid expectations of strong output. Vietnam’s coffee exports surged 39% year-on-year in November and 14.8% from January to November, according to government statistics. Total production in 2025/26 is projected to rise 6% to 1.76 million metric tons, a four-year high.

Globally, the International Coffee Organization reported a slight decline of 0.3% in coffee exports for the current marketing year, supporting price stability. The USDA projects world coffee output for 2025/26 to reach a record 178.85 million bags, with arabica falling 4.7% and robusta rising 10.9%. Brazil’s production is expected to decrease by 3.1%, while Vietnam’s output could rise 6.2% to a four-year high. Ending stocks are projected to decline by 5.4% to 20.15 million bags.

Overall, a combination of adverse weather in Brazil, flooding in Indonesia, and fluctuating inventories is contributing to upward momentum in coffee prices, even as abundant output in some regions, particularly Vietnam, applies downward pressure on robusta markets.

Russia Sets Record for Brazilian Coffee Imports

Moscow – Qahwa World

Russia significantly increased its imports of coffee from Brazil between January and November, with the total value reaching nearly $390 million — the highest level recorded to date, according to official Brazilian statistics.

Since the beginning of the year, Brazilian coffee shipments to Russia amounted to approximately $392.6 million, compared with about $232.3 million over the same period last year, highlighting a sharp expansion in bilateral trade within this segment.

Import volumes also rose in physical terms, totaling 62.3 thousand tonnes, which represents a 13% year-on-year increase.

As a result of the higher purchases, Russia ranked 11th among the world’s largest importers of Brazilian coffee. Germany remained the leading destination with imports worth around $2.1 billion, followed by the United States at $1.8 billion and Italy at approximately $1.2 billion.

Other major markets for Brazilian coffee during the period included Japan and Belgium, as well as the Netherlands, Türkiye, and Spain, while China also featured among the top ten importing countries.

Historic Sale at Cerrado Mineiro: Coffee Bag Fetches $38,500

Patrocínio, Brazil – Qahwa World

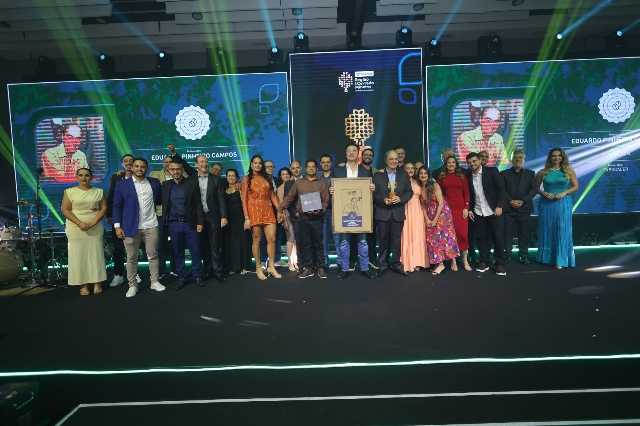
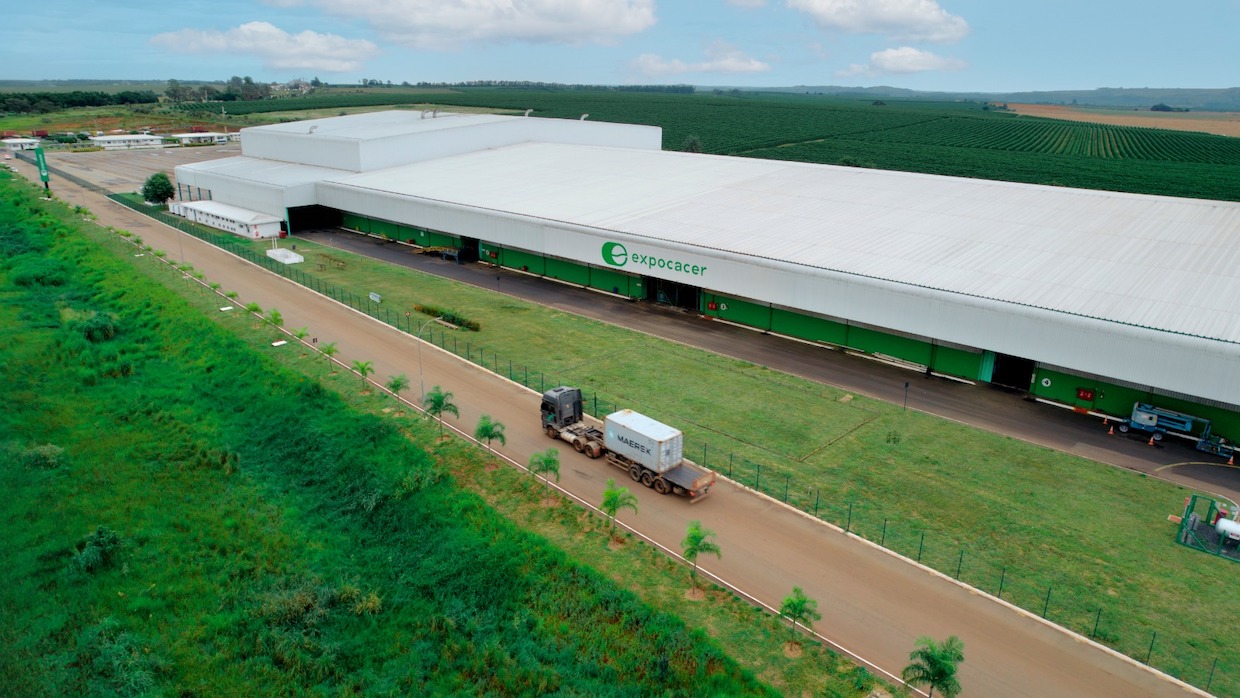
A bag of specialty coffee from Brazil’s Cerrado Mineiro region has reached a record price of US$38,500 at the 13th Cerrado Mineiro Regional Award in Uberlândia, Minas Gerais. The lot, winning the Pulped Cherry category, was cultivated by Eduardo Pinheiro Campos of Fazenda Dona Nenem in Presidente Olegário and purchased by a consortium led by Expocacer, in collaboration with Veloso Green Coffee, Marex, and Nucoffee.

The runner-up bid of US$19,250 went to Louis Dreyfus Company for the champion of the Natural category. The strong competition reflects growing worldwide interest in Cerrado Mineiro coffees.

The Cerrado Mineiro Coffee Growers Federation confirmed that this is the highest amount ever paid for a coffee bag at an auction in Brazil. The auction raised a total of US$108,500 across nine lots, averaging US$12,000 per bag.

Eduardo Pinheiro Campos commented: “This achievement honors our hardworking team. It reflects years of dedication, awards, and excellence. Over the thirteen editions of this competition, we have reached the podium eleven times, showing consistent quality and commitment.”

Simão Pedro, President of Expocacer, added: “When buyers compete at this level, it demonstrates the global recognition of our quality, sustainability, and innovation. Expocacer is proud to lead Brazil’s coffee sector, proving that our specialty coffee sets benchmarks internationally.”

The 13th Cerrado Mineiro Regional Award showcased the best coffees of the 2025–2026 harvest in four categories: Natural, Pulped Cherry, Fermented, and Sweet Cerrado Mineiro. Expocacer members won first place in Pulped Cherry and shared first place in Sweet Cerrado Mineiro.

Forty percent of the auction proceeds (US$43,400) will benefit the Escola de Atitude project, which supports youth education and personal development in coffee-growing communities.

Highlights of Expocacer at the 13th Cerrado Mineiro Regional Award

Eduardo Pinheiro Campos – First place, Pulped Cherry (90.59 points)

Maria Soraia Guimarães – Third place, Pulped Cherry (89.18 points)

Guima Café – First place (shared), Sweet Cerrado Mineiro

About Expocacer
Founded in 1993 in Patrocínio, Minas Gerais, Expocacer is a cooperative of coffee producers supporting over 740 members. With modern facilities, including warehouses holding over one million coffee bags, the cooperative exports specialty coffee to more than 35 countries while promoting social and environmental initiatives.

Brazilian Real Firming Lifts Arabica Coffee as Market Signals Remain Mixed

Dubai – Qahwa World

March arabica coffee (KCH26) rose slightly by +0.15 (+0.04%) on Tuesday, while January ICE robusta (RMF26) slipped -15 (-0.34%), hitting a 1.5-week low. The day’s movements reflect a split market, with arabica gaining support from a stronger Brazilian real, now at a two-week high against the US dollar. The firmer currency is discouraging export sales from Brazil’s growers, helping arabica prices edge upward.

Robusta, however, is under pressure. The Vietnam Coffee and Cocoa Association reported that around 10% of the country’s robusta harvest is now complete and forecasted that expected drier weather will accelerate harvesting through the month. Vietnam is the world’s largest robusta producer, and signs of increased output continue to weigh on prices.

Weather conditions in Brazil are offering some support to the market. Somar Meteorologia noted that Minas Gerais—Brazil’s main arabica-producing region—received only 20.4 mm of rain in the week ending November 28, equivalent to 39% of the historical average.

Coffee inventories monitored by ICE continue to tighten. US tariffs on coffee imports from Brazil triggered a sharp drawdown in stocks. ICE-certified arabica inventories reached a 1.75-year low of 398,645 bags on November 20, while robusta inventories fell today to an 11-month low of 4,115 lots. American buyers have cancelled new Brazilian coffee contracts due to the tariffs, tightening domestic supply. US imports of Brazilian coffee from August to October fell 52% year-on-year to 983,970 bags.

On the policy side, the outlook for ample supply strengthened after the European Parliament approved a one-year delay to the European Union’s anti-deforestation law (EUDR). The postponement allows EU members to continue importing agricultural commodities—including coffee—from regions in Africa, Indonesia, and South America where deforestation remains a concern.

Several supply signals are weighing on the market. StoneX recently projected Brazil’s 2026/27 crop at 70.7 million bags, including 47.2 million bags of arabica, a 29% year-on-year increase. Vietnam’s supply outlook also remains heavy: its Jan–Oct exports rose 13.4% year-on-year to 1.31 MMT, and 2025/26 production is expected to grow by 6% to 1.76 MMT (29.4 million bags), a four-year high. Vicofa additionally suggested that Vietnam’s 2025/26 output could rise by 10% if favorable weather continues.

Some indicators continue to signal tightening global supply. The International Coffee Organization reported that global exports for the current Oct–Sep cycle slipped 0.3% year-on-year to 138.658 million bags. In Brazil, Conab cut its 2025 arabica estimate by 4.9% in September, lowering the projection to 35.2 million bags. Total Brazilian coffee output was trimmed to 55.2 million bags.

Longer-term forecasts from the USDA’s Foreign Agriculture Service expect global production to rise 2.5% in 2025/26 to a record 178.68 million bags. The outlook includes a 1.7% decline in arabica output to 97.022 million bags, alongside a 7.9% increase in robusta to 81.658 million bags. Ending stocks are projected to rise 4.9% to 22.819 million bags.

Brazil’s Expocacer Launches First Blockchain-Powered Coffee Auction

Dubai – Qahwa World

The major Brazilian coffee cooperative Expocacer is taking a significant digital step by preparing to host its inaugural online auction on the new Coffee Chain trading platform. This event will offer roasters and importers worldwide access to highly traceable specialty coffee lots.

Auction Details and Focus
Scheduled for December 11-12, the online-only auction, branded “Essências by Expocacer,” will feature select lots from the cooperative’s Essências program. This initiative is designed to assist small and medium-sized members in developing and marketing higher-value specialty coffee.

The auction is open for registration to any entity or individual within the global القهوة industry, targeting roasters and importers internationally.

While official lot details and opening bids are pending release, promotional materials for Coffee Chain indicate a strong emphasis on high-scoring microlots sourced from the Cerrado Mineiro region. These lots are expected to come with extensive farm-level documentation and complete traceability.

The Coffee Chain Platform
This auction marks a key milestone in the deployment of Coffee Chain, a digital trading solution co-developed by Expocacer and the Brazilian technology firm AIDDA, which specializes in providing blockchain-based solutions for the agricultural sector.

The cooperative describes the custom-built system as a comprehensive tracker for production, inventory, and sales data, with every transaction and event securely logged on the blockchain. The platform also integrates certifications, verifies designation of origin, and provides tools to streamline contract negotiation and management for its users.

Initially unveiled at the 2025 Specialty Coffee Expo in Houston, the platform was presented as a transparent, direct e-commerce channel for trade. Expocacer currently backs the platform with logistics hubs established in the United States and the UK, enabling service to over 40 export markets globally.

Sandra Moraes, Expocacer’s Specialty Coffee Manager, emphasized the platform’s strategic importance, noting, “The significance and high competitiveness of the U.S. market motivated us to further advance the development of the Coffee Chain platform.” She added that the platform has demonstrated “consistent growth in its user base and sales volume, establishing itself as a valuable client solution.”

The cooperative is capitalizing on a successful year, having reported in November that it anticipates closing 2025 with approximately $545 million in revenue, a surge of about 58% compared to 2024. Foreign sales now account for more than half of its total revenue.

Global Coffee Prices Jump Amid Supply Concerns

Dubai – Qahwa World

Prices for coffee futures saw a sharp increase today, driven by worries over how weather conditions might impact harvests in major producing nations, alongside notable drops in monitored exchange inventories.

Prices for both arabica and robusta coffee are significantly higher as adverse weather bolsters concerns over global coffee crops. Arabica coffee has found support due to dryness concerns in Brazil. Specifically, meteorology reports indicated that Brazil’s largest arabica coffee-growing area, Minas Gerais, received 49% of its historical average rainfall during the week ended November 21st, fueling concerns about the current crop. Robusta coffee is climbing today on forecasts of heavy showers in Vietnam’s Dak Lak province, the country’s biggest coffee-growing region. These heavy rains are expected to further delay the harvest, tightening short-term supply expectations.

Shrinking inventories monitored by the Intercontinental Exchange (ICE) are also supportive of prices. US trade actions concerning Brazilian coffee imports have reportedly caused a substantial reduction in US exchange stockpiles. ICE-monitored arabica stocks fell to a 1.75-year low last week, and ICE robusta inventories hit a 4.5-month low today. American buyers avoided new contracts for Brazilian coffee purchases due to the tariffs, thereby tightening US supplies, as about a third of America’s unroasted coffee comes from Brazil. US purchases of Brazilian coffee during the period when tariffs were effective dropped by 52% from the same period last year.

Last Friday, arabica coffee had briefly tumbled to a seven-week low after an executive order was signed late last week, exempting Brazilian food products, including coffee, from the 40% tariff. In a potentially bearish factor, one major commodity consultancy forecast that Brazil will produce 70.7 million bags of coffee in the new 2026/27 marketing year, including 47.2 million bags of arabica, a significant year-over-year increase. Increased Vietnamese coffee supplies are also bearish for prices. Recent statistics show Vietnam’s coffee exports rose by 13.4% year-over-year in the January-October period. Additionally, Vietnam’s 2025/26 coffee production is projected to climb 6% year-over-year to a four-year high of 29.4 million bags, with the Vietnam Coffee and Cocoa Association suggesting a 10% increase if weather remains favorable. Vietnam is the world’s largest producer of robusta coffee.

Signs of tighter global coffee supplies are generally supportive of prices. The International Coffee Organization (ICO) reported that global coffee exports for the current marketing year (October-September) fell 0.3% year-over-year. Coffee prices also found support after Conab, Brazil’s crop forecasting agency, cut its Brazil 2025 arabica coffee crop estimate by 4.9% in September, and slightly reduced its total Brazil 2025 coffee production estimate. The USDA’s Foreign Agriculture Service (FAS) previously projected that world coffee production in 2025/26 will increase by 2.5% to a record high, driven by a 7.9% increase in robusta production, offsetting a slight decrease in arabica output. FAS forecasted modest production increases for both Brazil and Vietnam in 2025/26, along with a climb in global ending stocks.

Global Coffee Market Finds Balance as Prices Stabilize and Trade Shifts Eastward

October 2025 ICO Report Reveals Steady Prices, Regional Export Rebalancing, and Signs of Market Surplus

Dubai – Qahwa World

After months of price turbulence driven by weather extremes, logistics disruptions, and policy shifts, the global coffee market entered October 2025 in a rare state of equilibrium. According to the latest Coffee Market Report issued by the International Coffee Organization (ICO), the ICO Composite Indicator Price (I-CIP) averaged 326.38 US cents per pound, a modest 0.5% increase over September—marking a month of sideways stability in an otherwise volatile year.

The data reflects a market adjusting to both rising production in key origins and softening consumption growth across major economies. Yet behind this stability lies a quiet reshaping of global trade flows, as Asia and Africa consolidate export strength while South America experiences cyclical slowdown.

A Month of Stability Amid Global Uncertainty

The October 2025 I-CIP fluctuated between 314.68 and 344.77 US cents/lb, posting a median of 325.52 US cents/lb. Although stable, prices remain 30% higher than a year earlier, underscoring the persistent cost pressures that continue to define the post-pandemic coffee economy.

Price movements among coffee groups showed a clear divide. Colombian Milds slipped marginally (−0.1%) to 403.25 US cents/lb, while Other Milds gained 0.9% to 403.79 US cents/lb. Brazilian Naturals fell slightly to 373.47 US cents/lb, and Robustas, in contrast, expanded 2.0% to 215.06 US cents/lb — a sign of ongoing resilience in lower-grade coffee demand, especially for soluble and instant formats.

The differential between Colombian Milds and Other Milds narrowed into negative territory (−0.54 US cents/lb), highlighting how recent weather disruptions in Central America temporarily compressed quality spreads. Meanwhile, arbitrage between London and New York futures markets contracted by 2.9% to 163.84 US cents/lb, signaling closer alignment between Arabica and Robusta futures.

Market volatility, however, crept upward. Intra-day volatility of the I-CIP averaged 15.9%, up by more than two percentage points month-on-month — an indication that traders remain reactive to climate events and logistics developments, such as Suez Canal restrictions and persistent container shortages delaying deliveries.

Weather, Tariffs, and Consumption Trends: Forces in Counterbalance

The ICO attributes October’s price stability to a balance between bullish and bearish factors.

On the bullish side, Hurricane Melissa and low rainfall in key Brazilian coffee zones constrained supply, while Typhoon Kalmaegi caused significant crop losses in Vietnam, the Philippines, and Cambodia. The continuation of structural backwardation in futures markets — where near-term contracts are priced higher than future ones — further indicates tight supply for immediate delivery.

At the same time, several bearish influences tempered the market. Among them, signs of slowing consumption in the United States, where rising living costs have eroded discretionary spending. Vehicle repossessions, up 12% year-on-year, highlight a broader financial strain that extends to premium beverage categories. Additionally, a potential reduction in U.S. tariffs on Brazilian coffee — hinted at by Presidents Donald Trump and Luiz Inacio Lula da Silva — has fueled expectations of eased trade tension and lower costs for importers.

The result: prices moved horizontally through the month, neither rallying nor collapsing — a rare moment of equilibrium in a market accustomed to extremes.

Export Flows Reveal a Shifting Coffee Geography

While prices stabilized, trade patterns told a story of transformation. Global green coffee exports reached 9.94 million 60-kg bags in September 2025, down 0.2% year-on-year, marking the sixth consecutive month of negative growth in the 2024/25 coffee year. Total exports across all coffee forms fell by 2.8% to 11.00 million bags.

The Arabica segment showed divergence.

  • Colombian Milds rose by 7.0%, driven by Colombia’s robust output of 14.87 million bags — up 16.5% from the previous year.

  • Other Milds gained 6.1%, with Ethiopia, Mexico, and Nicaragua performing strongly.

  • Brazilian Naturals, however, plunged 21.9% as Brazil entered its “off-year” in the biennial Arabica cycle and faced logistics delays at the port of Santos.

  • Robustas grew 23.0% to 3.67 million bags, powered by Vietnam and Indonesia, whose improved harvests sharply reversed last year’s declines.

These mixed results left the Arabica share of global exports at 63.4%, a marginal drop from 63.7% the previous year — consistent with the long-term average since 2016.

Ethiopia, notably, emerged as a bright spot, expanding exports by 24.4% to 4.91 million bags on the back of an 11% rise in local production and strategic release of stored stocks responding to high international prices.

Regional Divergence: East Rises as South America Contracts

Regional analysis underscores a structural eastward shift in coffee trade:

  • Asia & Oceania: Up 29.3% year-on-year in September and 9.1% for the full coffee year, reaching 44.45 million bags. The surge was led by Vietnam (+7.1%) and Indonesia (+46%), both benefiting from favorable weather and restored yields.

  • Africa: Rose 3.2% in September and 18.6% annually to 19.69 million bags, driven by strong harvests and higher export releases from Ethiopia and Uganda.

  • South America: Fell 13.9% in September and 12.3% across the coffee year to 58.94 million bags, largely due to Brazil’s cyclical downturn and port congestion.

  • Mexico & Central America: Declined 14.6% in September but expanded 7.7% annually to 15.58 million bags, with Mexico and Nicaragua showing resilience.

As a result, South America’s share of global coffee exports slid from 48.4% to 42.5%, while Asia & Oceania’s share climbed to 32.1%, its highest level on record.

This redistribution confirms what many analysts have observed through 2025: a geographic rebalancing of coffee supply chains, with the global center of gravity shifting steadily toward Asia and Africa.

Soluble Coffee Gains Ground

Trade data by form reinforces this transformation. Exports of soluble coffee declined 21.0% in September but rose 5.0% over the full year to 16.72 million bags. This steady annual growth signals a continuing pivot toward value-added coffee formats catering to urban markets and middle-income consumers in producing countries.

By contrast, roasted coffee exports dropped 22.9% year-on-year to 0.68 million bags, reflecting weaker demand for ready-to-drink products in mature economies. Green coffee still dominates global shipments, accounting for 87.5% of total exports.

Global Balance Returns to Surplus

The ICO estimates world production at 177.5 million bags in 2024/25, up 5.2% year-on-year, outpacing consumption, which grew just 1.4% to 175.1 million bags. This modest gap yields a surplus of 2.4 million bags, marking the first positive balance since 2021/22.

The surplus reflects stronger harvests in Asia and Africa, coupled with a stabilization of consumption after the pandemic-era surge. Europe and North America both registered declines in coffee intake (−1.2% and −3.3%, respectively), while consumption in Asia & Oceania rose 7.4%, highlighting a shift in demand patterns alongside production.

A Market at the Crossroads

The October 2025 ICO report captures a market in transition. Prices have steadied, but volatility remains elevated; production is up, yet distribution challenges persist. The eastward drift of coffee trade — reinforced by Indonesia, Vietnam, Ethiopia, and Uganda — may reshape the traditional dominance of Latin American origins in the years ahead.

For producers, this stability offers breathing room after years of disruption. For traders and roasters, it demands agility — balancing sourcing strategies across continents amid ongoing climate and logistical uncertainty.

In short, the coffee world has entered a new phase: from crisis to cautious equilibrium, where resilience and regional diversification define the next chapter of global coffee commerce.

EU’s New Deforestation Law Proposal Sparks Frustration Among Brazilian Exporters and Raises Coffee Market Concerns

São Paulo – Qahwa World

A new European Commission proposal to relax the implementation of the EU Deforestation Regulation (EUDR) has triggered frustration among Brazilian coffee, soybean, and beef exporters, who were among the first to invest heavily in sustainable supply-chain compliance to secure early access to European markets.

According to a Rabobank report seen by Reuters, the proposed changes — which include postponing enforcement deadlines and easing penalties — could undermine the financial incentives that originally drove agribusinesses to adopt deforestation-free practices ahead of schedule.

The current law requires exporters of coffee, cocoa, palm oil, soy, wood, and beef to the European Union to provide due-diligence statements proving that their products are not linked to deforestation.

Under the new proposal, large companies would begin compliance checks from June 30, 2026, while smaller firms with fewer than 50 employees would have until December 30, 2026 to submit their declarations.

Rabobank analyst Marcela Marini emphasized that the delayed enforcement could erode the competitive advantage of those who acted early: “Companies that invested ahead of time were aiming for preferential access to the European market. The absence of fines and delayed enforcement weakens the incentive for sustainability premiums.”

The report also warned that the revision may disrupt global coffee supply chains, especially as the industry intensifies efforts toward traceability and environmental transparency.

The European Parliament is expected to review the proposal in the coming weeks. If approved, the regulation will still take effect in 2025, but with softer requirements and extended timelines — a move that some experts fear could dilute Europe’s commitment to fighting deforestation and impact the global push for sustainable coffee production.

Global Coffee Prices Fall as U.S.–Brazil Trade Talks Raise Hopes for Tariff Relief

New York – Qahwa World

Coffee prices continued to decline on Monday as traders reacted to signs of a possible breakthrough in trade negotiations between the United States and Brazil. The downward movement follows a volatile week in which arabica and robusta futures hit multi-month highs before retreating sharply.

Market optimism grew after Brazil’s President Luiz Inácio Lula da Silva announced that his meeting with U.S. President Donald Trump, held on the sidelines of the ASEAN Summit in Malaysia, was “surprisingly good.” Lula hinted that both nations were close to finding a “definitive solution” on trade within days. This development has raised expectations that the heavy tariffs imposed on Brazilian exports, including coffee, could soon be eased.

Brazil, the world’s largest coffee exporter, has been significantly affected by the 50 % tariffs placed on its coffee shipments to the U.S. earlier this year. The duties have disrupted the normal flow of beans to American buyers, forcing many roasters to look for alternative suppliers. As a result, coffee inventories monitored by ICE have dropped to their lowest levels in over a year — arabica stocks fell to 447,773 bags and robusta holdings slipped to just over 6,000 lots. Since nearly one-third of the U.S. coffee supply comes from Brazil, any shift in trade policy could have immediate effects on American imports and retail prices.

Even as the diplomatic news eased some pressure, weather conditions in Brazil continue to concern the market. Somar Meteorologia reported that the main arabica-producing state of Minas Gerais received only 0.3 millimeters of rain in the week ending October 24 — about 1 % of its normal rainfall. The Bloomberg Brazil Weather Analysis confirmed that rainfall across the region has been about 30 % below average for the past month, fueling fears that prolonged dryness could reduce flowering and affect the 2026/27 crop yield.

Meanwhile, Vietnam’s coffee sector, the world’s largest producer of robusta, is showing the opposite trend. The Vietnam Coffee and Cocoa Association expects production in 2025/26 to increase by 10 % year-on-year if favorable weather continues. Official statistics show that the country exported 1.23 million metric tons between January and September 2025 — up 10.9 % from a year earlier — and total output for the upcoming season is projected to reach 1.76 million tons, equivalent to 29.4 million bags. This would mark Vietnam’s most productive season in four years and continue to weigh on robusta prices.

The International Coffee Organization also reported that global coffee exports from October to August rose slightly by 0.2 % to 127.9 million bags, suggesting that the overall supply remains sufficient despite regional challenges. In Brazil, crop forecasting agency Conab cut its 2025 arabica estimate in September by 4.9 % to 35.2 million bags, bringing total coffee production for the year to 55.2 million bags.

At the global level, the U.S. Department of Agriculture’s Foreign Agriculture Service (FAS) projects total coffee production for 2025/26 to reach 178.7 million bags — a 2.5 % increase year-on-year. Arabica output is expected to fall 1.7 % to 97 million bags, while robusta is forecast to grow 7.9 % to 81.6 million bags. Ending stocks are likely to rise nearly 5 % to 22.8 million bags, signaling more comfortable supply conditions heading into 2026.

However, climate factors may quickly change that outlook. The U.S. National Oceanic and Atmospheric Administration (NOAA) has raised the probability of a La Niña event to 71 % for the period between October and December. If it materializes, it could lead to drier-than-usual conditions across Brazil’s coffee-growing regions, threatening future yields.

For now, the coffee market remains pulled between political progress and environmental risk. The possibility of a U.S.–Brazil trade agreement could restore smoother coffee flows to the United States and ease supply constraints, but persistent drought conditions in South America and growing output in Southeast Asia continue to shape global price trends. Traders are watching both developments closely as the market searches for direction in the final quarter of 2025.

South America’s 100 Best Coffee Shops 2025 – Full List Revealed

Dubai – Qahwa World

The global coffee community celebrates a new milestone as The World’s 100 Best Coffee Shops unveils the official list of South America’s 100 Best Coffee Shops 2025, recognizing the continent’s finest cafés for their excellence, creativity, and cultural impact.

After months of evaluation and travel across cities, mountains, and coffee regions, the judges compiled a single, unified ranking that reflects South America’s dynamic coffee landscape — one that continues to inspire and shape global coffee culture.

This year’s edition honors cafés that deliver exceptional quality, unique concepts, sustainable practices, and authentic coffee experiences. From traditional roasteries to modern coffee laboratories, these 100 destinations represent the beating heart of coffee craftsmanship in the region.

South America’s 100 Best Coffee Shops 2025 — Complete List

  1. Tropicalia Coffee / Colombia

  2. Kafi Wasi Café Tostaduría / Peru

  3. Holaste! Specialty Coffee / Chile

  4. Fankør / Ecuador

  5. Tributo Casa de Café – Chacao / Venezuela

  6. Fruto Café / Argentina

  7. Monotono Specialty Coffee / Peru

  8. Cupping Café / Brazil

  9. Puku Puku / Peru

  10. Eco Mapu Coffee Villarica / Chile

  11. Typica Café / Bolivia

  12. Pergamino Café Laureles / Colombia

  13. Caferatto Café Especial / Colombia

  14. Wake Up Coffee Lab / Chile

  15. Masaro Café / Peru

  16. Mulano Coffee Shop / Ecuador

  17. Origen Tostadores de Café / Peru

  18. Casa Canela / Venezuela

  19. Mugen Coffee Project / Bolivia

  20. Coffee Five / Brazil

  21. Café Guayasamín – Centro Quito / Ecuador

  22. Café de Barrio / Argentina

  23. Three Monkeys Coffee Cusco / Peru

  24. Abstrakto Café de Especialidad / Uruguay

  25. Neira Café Lab / Peru

  26. Café Local / Chile

  27. Tasta Café / Peru

  28. Oso Café / Peru

  29. Insignia Coffee / Colombia

  30. Alquimia Specialty Coffee Shop / Bolivia

  31. Antaqa Café / Peru

  32. Café 4 Llamas – Santa Cruz / Bolivia

  33. Café Micelio Puerto Varas / Chile

  34. Rua – Café de Especialidad Curado / Ecuador

  35. Café 18 – El Chicó / Colombia

  36. Cronopios Café / Ecuador

  37. Abisinia Café y Tostaduría / Peru

  38. Slow Brew Coffee Shop Cuenca / Ecuador

  39. HB Bronze Coffeebar / Bolivia

  40. Tres / Argentina

  41. Don Salazar / Peru

  42. Cuervo Café / Argentina

  43. Punto Café / Peru

  44. Famosta Café / Colombia

  45. Negro Cueva de Café / Argentina

  46. Libertario Coffee Roasters – Calle 70A / Colombia

  47. Surry Hills Coffee Palermo / Argentina

  48. Azahar Café / Colombia

  49. D’sala Caffé / Peru

  50. Café Folks / Chile

  51. Café Melosa / Venezuela

  52. Florencia y Fortunata Specialty Coffee / Peru

  53. Roaster Specialty Coffee / Bolivia

  54. Stratto Bodega de Café + Coffee Shop / Ecuador

  55. Raiz Coffee / Peru

  56. Café Buena Vista / Bolivia

  57. Buho Nómada / Chile

  58. Colo Coffee / Colombia

  59. Atmósferico Cafetería de Especialidad / Ecuador

  60. Indera Experience Cafetería de Especialidad / Ecuador

  61. Kofi & Co / Brazil

  62. Típica Café Milla de Oro / Colombia

  63. Coffee Busters Roastery / Peru

  64. Mato Café / Brazil

  65. Cafetería Tunu Katari / Peru

  66. KOF – King of the Fork / Brazil

  67. Café Ao Leu / Brazil

  68. Primates Tostadores / Chile

  69. Lucca Cafés Especiais / Brazil

  70. María Julio Coffee Shop / Colombia

  71. Kaweh Coffee Shop / Ecuador

  72. Puma Café / Peru

  73. Dagada / Ecuador

  74. Somos Specialty Coffee / Bolivia

  75. Coffeestylers / Colombia

  76. Amanecer Coffee Store / Venezuela

  77. ArtemisA Coffee & Cocktail Bar / Chile

  78. Alto Tostado Coffee Roasters – Santa Cruz / Bolivia

  79. Eleganza Coffee Roasters / Chile

  80. Ciclos Café / Peru

  81. Blacksoul Café Brewing Lab / Bolivia

  82. Marrón Café / Venezuela

  83. Laurino Coffee / Colombia

  84. Café Nexos / Venezuela

  85. 9 Gramos Café / Colombia

  86. Manva Natural Market / Venezuela

  87. Rita Specialty Coffee Armenia / Argentina

  88. Café Black Mamba / Chile

  89. Kaffei / Paraguay

  90. Elevaria Café / Peru

  91. Casa Berracos / Uruguay

  92. Senzuru Coffee / Peru

  93. Anella Café / Venezuela

  94. Kajue Café / Argentina

  95. Varietale Chapinero / Colombia

  96. Ninina / Argentina

  97. Guanacoffee / Peru

  98. Barista Coffee House / Argentina

  99. Café Bauda / Chile

  100. Calu’s / Argentina

A Continental Celebration of Coffee Excellence

The 2025 list captures the remarkable growth of specialty coffee in South America, where cafés are increasingly emphasizing sustainability, direct trade, and community connection. From Peru’s mountains to Colombia’s coffee triangle, each café has earned its place through dedication and creativity.

This recognition is more than a ranking — it’s a celebration of coffee as a cultural bridge. Each destination tells a story of farmers, roasters, and baristas working together to redefine what coffee can be.

The organizers extended their gratitude to this year’s sponsors and partners:
@cafedecolombia, @corferias, @fidatecorg, @hechoencafe, Craft Specialty Coffee, and @fedecafeterosc, for their continued support in promoting excellence and sustainability in coffee.

About the Awards

The South America’s 100 Best Coffee Shops 2025 is part of The World’s 100 Best Coffee Shops global initiative, which celebrates the finest cafés worldwide. The listings are curated by international coffee professionals who assess cafés on quality, innovation, design, and overall customer experience.

For the complete story and upcoming global rankings, visit:
https://theworlds100bestcoffeeshops.com/

U.S.-Made Coffee Remains More Expensive Than Imports Despite Tariffs

Dubai – Qahwa World

Throughout 2025, U.S. consumers have witnessed a steady rise in prices across nearly all goods following the administration’s decision to impose tariffs on imported products from global trade partners. Coffee has been no exception, even though the United States relies almost entirely on imported beans to satisfy domestic demand.

Data shows that coffee prices rose by 14.5% between July 2024 and July 2025, while roasted and packaged coffee in supermarkets increased by 21.7% between August 2024 and August 2025. These price hikes are largely attributed to tariffs affecting major coffee-producing nations such as Brazil, which supplies around 40% of the world’s coffee, and Vietnam, the second-largest global exporter.

Despite rising international prices, coffee produced within the United States remains significantly more expensive — a trend unlikely to change. Coffee cultivation requires specific geographical and climatic conditions found only in limited areas of the country, most notably Hawaii, where the right soil and altitude allow for small-scale production of high-quality beans. Even so, the total domestic yield accounts for barely 1% of what Americans consume annually.

Experts in both agriculture and finance agree that the United States lacks the natural and environmental capacity to achieve self-sufficiency in coffee production, even if domestic and imported prices were equal. Consumption far exceeds what local producers can supply, and expanding cultivation faces both economic and ecological constraints. The country’s main coffee-growing regions — Hawaii and Puerto Rico — can only cover a fraction of nationwide demand.

While tariff policies are intended to strengthen local industries and reduce reliance on imports, coffee remains a clear exception. Natural limitations make large-scale domestic production unfeasible, and imported coffee continues to be more affordable and abundant despite higher tariffs. Analysts conclude that the American coffee market will remain deeply tied to global supply chains — particularly to producers in Brazil, Vietnam, and Ethiopia — regardless of future policy changes or tariff increases.