Top 20 Most Powerful Coffee Companies in the World 2026

The Map of Influence and the $200 Billion Battle

DUBAI – QAHWA WORLD

In 2026, the coffee sector has transcended being a mere consumer commodity to become one of the most complex and influential sectors in the global economy. As the market value surpasses the $200 billion mark, the map of power has been redrawn. “Store count” is no longer the sole metric of success; instead, Big Data, Sustainable Supply Chains, and Digital Delivery Speed have become the primary engines of growth. This report highlights the 20 titans shaping the coffee landscape in 2026 based on operating income, market influence, and geographical footprint.

Top 10 Coffee Companies in the Retail Sector (Coffee Chains)

  1. Starbucks – USA:

    • Revenue: ~$39.2 Billion.

    • Footprint: +40,000 stores in 86 countries.

    • Analysis: Remains the dominant global force. In 2026, it successfully integrated the “Deep Brew” AI to predict customer orders with 95% accuracy and solidified its position in China despite fierce competition.

  2. Luckin Coffee – China:

    • Revenue: ~$6.8 Billion.

    • Footprint: +22,000 stores (surpassing Starbucks in Asia by count).

    • Analysis: Operates on a “Cloud Cafe” model with 100% digital ordering. Its strength lies in low overhead costs and lightning-fast expansion.

  3. Tim Hortons – Canada:

    • Revenue: ~$4.8 Billion.

    • Footprint: +5,900 stores.

    • Analysis: The powerhouse of the RBI group. It expanded aggressively in 2026 into emerging markets like India and the Philippines while maintaining absolute dominance in Canada.

  4. McCafé – USA:

    • Estimated Revenue: ~$3.5 Billion (as a standalone segment).

    • Footprint: Available in most McDonald’s locations (+40,000 points).

    • Analysis: The “silent” competitor to Starbucks. In 2026, it pivoted toward high-quality specialty beans to compete with premium cafes at economy prices.

  5. Dunkin’ – USA:

    • Footprint: +13,500 stores.

    • Analysis: Under Inspire Brands, Dunkin’ has transformed into a tech-centric company, with 60% of sales processed via mobile apps in 2026.

  6. Costa Coffee – UK:

    • Footprint: +4,300 stores and +16,000 “Costa Express” machines.

    • Analysis: Its true strength in 2026 lies in “Smart Vending,” delivering cafe-quality coffee in gas stations and airports, backed by Coca-Cola’s logistics.

  7. Panera Bread – USA:

    • Revenue: ~$6.2 Billion.

    • Analysis: A pioneer in the “Subscription Economy.” In 2026, its “Unlimited Sip Club” reached record numbers, ensuring steady recurring cash flow.

  8. Cotti Coffee – China:

    • Footprint: +8,000 stores.

    • Analysis: The challenger that was born big. It follows an aggressive pricing strategy, securing the 8th spot globally by store count in record time.

  9. Peet’s Coffee – USA:

    • Analysis: Focuses on “Coffee Purists.” In 2026, it became the go-to reference for fresh-roasted coffee in the premium US and Asian markets.

  10. Caribou Coffee – USA:

    • Footprint: +850 stores.

    • Analysis: Despite a smaller footprint, it dominates the US Midwest and maintains a powerful presence in the Middle East through franchising.

Top 10 Coffee Companies in the Manufacturing Sector (Packaged & Home Coffee)

  1. Nestlé – Switzerland:

    • Coffee Revenue: +$26.5 Billion.

    • Brands: Nescafé, Nespresso, Starbucks At Home.

    • Analysis: The “Central Bank of Coffee.” Dominates soluble coffee and capsules, holding the largest R&D budget for climate-resilient coffee strains.

  2. JDE Peet’s – Netherlands:

    • Revenue: ~$10.2 Billion.

    • Analysis: The European giant with over 50 brands. In 2026, it strengthened its grip on packaged coffee in emerging markets.

  3. Keurig Dr Pepper – USA:

    • Revenue: ~$15.5 Billion (Total Group).

    • Analysis:* Controls the “Single-Serve” system in North America and serves as a manufacturing partner for over 100 other brands.

  4. Lavazza – Italy:

    • Revenue: ~$3.4 Billion.

    • Analysis: The icon of Italian coffee. In 2026, it successfully acquired several specialty roasters in Europe to boost its “Premium” segment presence.

  5. Tchibo – Germany:

    • Analysis: A unique business model combining coffee trade with consumer goods, holding a dominant position in Germany and Eastern Europe.

  6. Olam Food Ingredients (OFI) – Singapore:

    • Analysis: The “Back-end Engine.” The largest supplier of green beans and processed coffee to most companies on this list, making it a strategic player in global pricing.

  7. UCC (Ueshima Coffee Co.) – Japan:

    • Analysis: A leader in Ready-to-Drink (RTD) and canned coffee innovation. Dominates the Asian market and owns model estates in Hawaii and Brazil.

  8. Melitta – Germany:

    • Analysis: Controls both the brewing equipment and the coffee itself, providing a competitive edge in the “At-Home” segment.

  9. illycaffè – Italy:

    • Analysis: While not the largest by revenue, it is the strongest in “Reputation.” In 2026, illy remains the gold standard for the luxury hotel and restaurant sector worldwide.

  10. Strauss Coffee – Brazil/Israel:

    • Analysis: Dominates the Brazilian market (the world’s largest producer) and holds leading market shares in Russia and Eastern European countries.

Key Indicators for 2026

  • Digital Transformation: 45% of sales for major companies (like Starbucks and Luckin) are now conducted via mobile apps.

  • Sustainability: Net-zero carbon commitment has become a prerequisite for staying on the list; Nestlé and Lavazza have invested billions in sustainable supply chains.

  • Specialty Growth: Giants are increasingly acquiring small specialty roasters to cater to Gen Z preferences.

  • The Asia Market: China is no longer an “emerging” market; it has become the “Main Engine” for global store growth.

Major Trends of 2026

This report shows that the gap between “cup sellers” and “coffee manufacturers” is narrowing. Power in 2026 belongs to companies that own Customer Data and control the Supply Chain from Farm to Cup. We also note the rise of Ready-to-Drink (RTD) coffee as the fastest-growing segment, prompting giants like Nestlé and Coca-Cola (Costa) to inject massive investments.

Research Note: This data was compiled based on fiscal year-end reports for 2025 and growth projections for Q1 2026. Financial figures reflect market value and operational cash flows.
Coffee Prices Rise as Brazilian Real Strength Sparks Short Covering

DUBAI – QAHWA WORLD

Coffee futures climbed sharply on Thursday following a surge in the Brazilian real, which encouraged traders to cover short positions. March arabica contracts closed up 1.65%, while March robusta contracts rose 2.02%.

The real reached its highest level against the U.S. dollar in nearly two years, prompting caution among Brazilian coffee exporters and contributing to the price gains.

Over the past two weeks, coffee prices had been under pressure. Arabica and robusta recently hit six-month lows amid expectations of a strong Brazilian crop. According to Brazil’s crop agency Conab, total coffee production in 2026 is projected to reach 66.2 million bags, up 17.2% from 2025. Arabica output is expected to increase 23.2% to 44.1 million bags, while robusta production is forecast to grow 6.3% to 22.1 million bags.

Rainfall in Brazil has also improved crop prospects. Minas Gerais, the country’s largest arabica-growing region, received 72.6 mm of rain during the week ending February 6, exceeding the historical average. This eased earlier concerns over dry conditions that had pressured prices.

Vietnam’s coffee exports, particularly robusta, are increasing, exerting downward pressure on prices. January exports rose 38.3% year-on-year to 198,000 metric tons, while total 2025 exports climbed 17.5% to 1.58 million metric tons. Production for 2025/26 is projected at 1.76 million metric tons (29.4 million bags), the highest in four years.

ICE coffee inventories have also recovered, limiting price gains. Arabica stocks, which fell to a 1.75-year low in November, rose to a three-month high by early January. Robusta inventories, previously at a 13-month low in December, similarly increased in January.

On the upside, Brazil’s coffee exports fell 42.4% year-on-year in January, reducing global supply pressure. Smaller production in Colombia, the second-largest arabica producer, also supported prices, with January output down 34% year-on-year.

Globally, the International Coffee Organization reported a slight decline (-0.3%) in exports for the current marketing year, signaling tighter supplies. Meanwhile, USDA forecasts indicate that total global coffee production in 2025/26 will reach a record 178.848 million bags, with arabica slightly down and robusta up. Brazil’s 2025/26 production is expected to decrease by 3.1%, while Vietnam’s output is projected to rise 6.2%, reaching a four-year high. Ending stocks are forecast to decline by 5.4%.

Brazil’s Canephora Coffee Cultivation Moves Beyond Traditional Regions

DUBAI – QAHWA WORLD

Brazil’s production of canephora coffee—covering conilon and robusta varieties—is spreading into states that have historically focused little on these crops. The expansion is being fueled largely by firm prices and growing demand, according to industry representatives and official data.

While Brazil remains the world’s leading producer of arabica coffee, canephora output has gained momentum in recent years. Canephora beans, typically used in espresso blends and instant coffee, offer higher yields compared to arabica and have become increasingly attractive to growers. Brazil is currently the second-largest canephora producer globally and continues to narrow the gap with Vietnam, the leading producer.

Traditionally, the state of Espírito Santo has dominated Brazil’s canephora production, particularly conilon. However, data from Companhia Nacional de Abastecimento (Conab) show that since 2020, other states—including Mato Grosso and Minas Gerais—have significantly increased their output.

  • Prices Encourage New Plantings

Strong international prices over the past year have encouraged farmers to plant canephora outside its traditional strongholds. Although prices have eased from last year’s highs, they remain above long-term averages, sustaining producer interest. Improvements in bean quality have also contributed to broader acceptance in both domestic and export markets.

Minas Gerais, best known as Brazil’s largest arabica producer, is projected to nearly double its canephora production between 2020 and 2026, reaching more than 600,000 60-kilogram bags, according to Conab forecasts.

  • Mato Grosso Eyes Productivity Gains

In Mato Grosso, a state better known for soybeans and corn, efforts are underway to boost canephora cultivation. Agronomists are drawing inspiration from neighboring Rondônia, a key robusta-producing state with higher average yields. Current productivity in Mato Grosso trails Rondônia’s levels, but local research and extension agencies are working to close the gap.

Conab estimates that Mato Grosso’s canephora production will approach 300,000 bags this year, nearly doubling compared with 2020 levels.

  • Ceará Explores New Opportunities

Further north, Ceará is evaluating the potential for both conilon and robusta Amazonica, a variety commonly cultivated in Rondônia. Although Ceará’s current production is modest and grouped with smaller producing states such as Acre and Pará in official statistics, combined output from these regions is projected to increase substantially by 2026.

Ceará’s proximity to ports and transport infrastructure is seen as an advantage for export-oriented growth. State officials anticipate an initial expansion of planted area in the coming years, with room for further development if market conditions remain favorable.

Overall, Brazil’s canephora sector is undergoing geographic diversification, supported by price incentives, productivity gains, and broader market demand.

Coca-Cola Confirms Continued Ownership of Costa Coffee

DUBAI – QAHWA WORLD

Coca-Cola has officially ended months of market speculation by announcing it will keep Costa Coffee as a wholly-owned subsidiary. Despite rumors of a potential divestment throughout 2025, the beverage giant has opted to maintain its hold on the international coffee chain.

The decision was confirmed by Coca-Cola CFO John Murphy during a recent interview with Bloomberg. While private equity interest—specifically from TDE Capital—was reported late last year, Murphy clarified that the company intends to keep Costa 100 per cent owned within its current portfolio. However, one area remains in flux as the company is still reviewing its operations in the Chinese market to determine the best path forward.

While financial filings from the UK Companies House showed an operating loss of approximately $18.42 million in 2024, the brand’s core remains resilient. Performance in the primary markets of the UK and Ireland is characterized as strong, and Costa continues to dominate as the UK’s largest coffee chain. On a global scale, the brand manages over 4,000 retail locations and a massive network of 14,000 “smart café” automated machines across more than 30 countries.

READ ALSO:

Costa Coffee on the Edge of Sale: Losses in the UK, Growth in Asia

Coca-Cola Weighs Future of Costa Coffee Amid Strategic Review

Uganda’s Ambition Shakes Coffee Markets: A Historic Leap Toward 20 Million Bags

DUBAI – QAHWA WORLD

While global markets remain preoccupied with weather volatility in Brazil, Uganda continues its steady and confident rise to solidify its position as the largest coffee exporting power in Africa, surpassing all conventional expectations.

According to data from the International Coffee Organization (ICO) Report for January 2026, Uganda recorded a historic surge in its exports with a growth rate of 52.5%, serving as a primary contributor to the increase in the continent’s total exports.

This exceptional performance was no coincidence; rather, it is the result of a national strategy that enabled the country to exceed the 8.2 million bags (60 kg each) annual threshold, placing it seventh globally and transforming it into a “pivotal player” that cannot be ignored in the global supply equation.

Analytical insights from the report indicate that Uganda successfully exploited the “price vacuum” left by production disruptions in other regions by improving production quality and expanding cultivated areas.

The Ugandan success story relies on a unique diversity; the country balances the production of “Robusta,” which forms the backbone of its exports, and high-quality “Arabica” grown on mountain slopes.

This diversity has granted it high flexibility in facing global exchange fluctuations, as Ugandan coffee has become the first choice for roasters seeking “value for money,” especially with increasing demand for both varieties in emerging European and Asian markets.

Behind these figures lies Uganda’s most ambitious plan in the continent’s history, aiming to double production to reach 20 million bags by 2030.

This government vision includes a comprehensive modernization of the post-harvest sector, the distribution of disease-resistant seedlings, and enhancing the capacities of smallholder farmers who represent 90% of the productive force.

Analysts believe that Uganda reaching this figure will make it a direct competitor to countries the size of Vietnam, redrawing the power map of the global coffee market and reducing total dependence on Latin American production.

The recent export leap is not just a number in an international report; it is a clear signal to investors that the center of gravity in coffee production has begun to shift toward East Africa. The ambition of 20 million bags is no longer a distant dream but an economic reality taking shape under the mantle of sustainable development and agricultural leadership.

Robusta Defies Global Downturn, Trading Against the Tide

DUBAI – QAHWA WORLD

While Arabica prices succumbed to the pressures of improving weather conditions in Brazil, the Robusta category recorded an exceptional case of economic resilience during January 2026, announcing the decoupling of its price path from the general market trend.

According to data from the International Coffee Organization (ICO) Report, Robusta achieved a solitary growth of 1.0%, raising its average price to 218.83 cents per pound. This came at a time when all Arabica categories witnessed sharp declines, peaking at 4.5% for Brazilian Naturals and 3.6% for Colombian Milds.

This price divergence places the global coffee market before a new structural reality, where Robusta has transformed from a “substitute option” into a “primary pillar” for major roasting companies seeking to maintain their profit margins.

Coffee economy experts attribute this price defiance to the increasing industrial reliance on Robusta in commercial coffee blends and the instant coffee sector, serving as a defensive mechanism against the violent fluctuations in Arabica prices that touched record levels early in the month.

The price gap (Arbitrage) between the two varieties began to narrow under the pressure of growing demand, granting producers in Vietnam and Uganda a negotiating power that enabled them to resist the mass sell-off that swept the New York Stock Exchange.

Analyzing the data shows that Robusta was unaffected by the Brazilian “rain shock” that toppled Arabica prices, as its supply is concentrated in geographical areas far from the climatic fluctuations of Latin America, making it a “stable asset” in traders’ portfolios during January.

Furthermore, the International Coffee Organization report indicates that the tightness of immediate Robusta supply in central markets played a decisive role in supporting prices above the 218-cent level.

While speculators were offloading Arabica contracts in the futures market, factories were racing to secure their Robusta needs to ensure the continuity of production lines, especially with the growth of coffee consumption in emerging markets that favor this variety for its price efficiency and suitability for manufacturing.

This performance reflects a maturity in the Robusta market, as its linked contracts on the London Stock Exchange (ICE) now show clear independence from the movements of the New York Stock Exchange, forcing top analysts to re-evaluate the weight of this variety in future risk assessment reports.

In conclusion, January 2026 proves that Robusta no longer follows Arabica “like a shadow” but has instead led its own stability front. Its 1.0% price growth in a bearish environment is a testament to the strength of real physical demand that transcends speculative noise.

This shift means the global coffee industry has entered a “multipolar” era, where the global cup remains as dependent on the hardiness of Robusta beans as it is on the aesthetics of Arabica, making the monitoring of Southeast Asian and African supplies an indispensable pillar for understanding the future of international coffee trade.

Minas Gerais Rains End Speculative Fever and Topple Global Coffee Prices

DUBAI – QAHWA WORLD

Global coffee markets witnessed a dramatic shift in the final week of January 2026, as a wave of heavy rainfall in Brazilian production regions toppled the hopes of those betting on continued price increases. In a corrective movement described as the most violent in months, the pound of coffee lost more than 21 cents of its value within just 72 hours, causing the International Coffee Organization Composite Indicator Price (I-CIP) to plummet from a peak of 304.17 cents on January 27th to 283.02 cents by the end of the month. This freefall was not merely a response to a passing climatic event, but rather an official announcement of the end of the “risk premium” that had fueled markets throughout the past period due to fears of a long-term drought in the state of “Minas Gerais,” the beating heart of coffee production in Brazil, according to the latest data issued by the International Coffee Organization (ICO) Report for January 2026.

The report’s analytical data indicates that the market entered January in a state of cautious balance, as clear directional catalysts were absent, keeping prices within a narrow range that left farmers in a state of financial satisfaction without pushing them toward aggressive selling. However, this situation evaporated immediately upon the release of meteorological reports confirming improved moisture in the Brazilian soil, providing a strong signal for investment funds and major speculators on the New York Stock Exchange to liquidate their long positions and flee the market before prices retreated to minimum levels. This “mass exodus” of speculators doubled the downward momentum, turning the price correction into a rapid collapse that disrupted the calculations of exporters who had bet on prices remaining above the 300-cent barrier.

Economically, this collapse was linked to local currency variables in Brazil; as the strength of the “Real” against the Dollar played a dual role at the beginning of the month by raising prices, before global markets succumbed to the pressure of expected future supply. Analysts believe that the recent rains not only improved the condition of the existing “Arabica” crop but also sent reassuring messages regarding the 2026/2027 season, which pulled the rug from under the traders who built their strategies on supply scarcity. This shift placed global roasting companies in a stronger negotiating position, as they began to reduce their spot purchases in anticipation of further declines, reflecting the technical state of “Backwardation” dominating the exchanges, where spot prices remain higher than futures contracts, discouraging the desire to build long-term inventories at high prices.

On the field level, the International Coffee Organization report confirmed that these climatic developments have redrawn the forecast map for the first quarter of the year, as markets are now expected to witness an abundance of supplies with the fading fears of “water stress.” In conjunction with these price pressures, major players in the New York market began reassessing their positions, amid expectations that downward pressure will continue as long as the sky continues to grant Brazil’s farms the necessary moisture. The “Rain Revolution,” as some traders called it, was nothing but a harsh reminder that technology and financial analysis remain helpless before weather fluctuations in the world’s largest coffee-producing country, and that the security of the global cup remains more linked to weather maps over the mountains of Brazil than to the policies of central banks.

Global Coffee Market Roadmap—January 2026

DUBAI – QAHWA

January 2026 was not merely the start of a new calendar year for the International Coffee Organization (ICO); it served as a critical testing ground for the resilience of global supply chains against dual shocks: climatic in the primary production origin (Brazil) and logistical in vital waterways. The ICO Composite Indicator Price (I-CIP) averaged 296.89 US cents/lb, a 2.6% decrease from December 2025. While this figure may appear as a slight retreat, a deep dive into daily market movements reveals a state of “silent boiling” that culminated in a sharp price collapse in the final three days of the month, ending a long period of relative stability since late 2025.

  • I. Price Psychology and the “Minas Gerais” Effect

Prices entered January in a state of “cautious balance” (range-bound), lacking clear directional catalysts. Prices fluctuated within a narrow band, interpreted by analysts as being high enough to keep farmers financially satisfied but not low enough to trigger aggressive stock liquidations. However, this calm was shattered by two opposing factors:

Currency Impact and Hedging (Early Month): In the first week, around January 6th, the indicator rose by 3.2%. This increase was driven not by supply shortages, but by the strength of the Brazilian Real. The positive correlation between the Real’s strength and global coffee prices is a classic driver; a stronger local currency reduces export incentives for Brazilian farmers who then prefer selling in the domestic market (CEPEA index), which offered attractive premiums over international prices, creating temporary upward pressure.

The Saving Rain Shock (End of Month): A dramatic shift occurred between January 27th and 30th, with the market losing over 21 cents in a flash. Eyes were glued to weather maps over Minas Gerais, the heart of Brazil’s coffee production. Reports of heavy, consistent rainfall dissipated the “risk premium” previously added by traders fearing drought. This precipitation not only improved the current crop’s condition but provided strong positive signals for the 2026/2027 season, prompting investment funds and speculators to liquidate long positions, causing the indicator to drop to 283.02 cents.

  • 2. Structural Shifts in Demand (Robusta as the New Leader)

The report reveals a significant economic phenomenon: diverging performance among the four main coffee groups. While Arabica varieties suffered sharp declines—up to 4.5% in the “Other Milds” category—Robusta was the only group to achieve positive growth (1.0%), stabilizing at 192.52 cents. This divergence is no coincidence; it is the result of a “structural” shift in the global coffee industry. Amid rising global living costs, major international roasters have begun adjusting “blends” to increase the proportion of Robusta to lower final costs for consumers. This sustained demand for Robusta narrowed the price gap (arbitrage) between the New York and London exchanges by 8.4%, signaling that Robusta is emerging as the actual driver of corporate profit stability.

  • 3. Export Geography: Redrawing the Global Map

Global green coffee exports in December 2025 reached a strong 10.15 million bags, up 9.2%. However, this hides stark regional disparities:

The Central America and Mexico Surge (81.3%): This figure must be read carefully; it reflects “recovery from paralysis” rather than a sudden productivity spike. In December 2024, tropical storms (notably Sara) delayed harvesting, making exports almost non-existent then. In December 2025, stabilized climate allowed coffee to flow normally to ports, resulting in a massive percentage increase compared to the previous year’s “trough.”

Asia and Oceania Leadership (Vietnam & Indonesia): The region grew by 38.4%, led by Vietnam (+30%). Vietnam compensated for early-season harvest delays through improved processing efficiency and the “base effect.” Indonesia and India also saw a combined 61.1% jump, reinforcing Asia’s position as a primary global supplier while South America falters.

South American Contraction (The Persistent Dilemma): For the 14th consecutive month, South America recorded a decline (-15.0%). Brazil fell by 18.5%, and notably, Colombia dropped by 18.9%. The report hypothesizes that Colombia may have reached its “maximum production capacity” due to environmental factors and labor structure changes.

  • 4. Uganda: A Unique African Success Story

Uganda stands out as the “hero” of the African continent, with exports jumping 52.5% in one month. This is the fruit of a national strategy to renew trees and expand Robusta acreage. Uganda aims to export 20 million bags by 2030, and current figures show it is on track, filling the void left by other struggling producers with competitive quality.

  • 5. Logistics: Red Sea Security as a Cooling Factor

A pivotal analytical point is the breakthrough in the Red Sea. Following long-term disruptions, major shipping lines resumed using the Suez Canal by January 12, 2026, after security stabilized. This has a direct price impact:

Reducing “Coffee on Water”: Shortening transit times freed up millions of bags previously held at sea for extra weeks, allowing them to reach European and American ports faster.

Increased Destination Stocks: The availability of coffee in consuming ports reduces “urgent” buying pressure, removing a key price support pillar from last year.

  • 6. Technical Analysis of Stocks and the “Backwardation” Dilemma

Despite export flows, the market faces a technical contradiction called “Backwardation,” where spot prices remain higher than futures. This indicates short-term “hunger” despite long-term optimism. Consequently, certified stocks remain at critical levels (50% of the 5-year average), acting as a “safety valve” that prevents total price collapse.

  • Conclusion and Future Outlook

The January 2026 report clarifies that the global coffee market is moving from a “supply crisis” to a “logistical and climatic rebalancing.” The 2.6% price drop is likely the start of a broader correction in Q1, provided Brazilian rains continue and Suez Canal traffic remains steady.

Ethiopian Coffee Lifts Russia Trade to $435m in 2025 Surge

DUBAI – QAHWA WORLD

Trade between Russia and Ethiopia climbed to more than $435 million in 2025, nearly tripling from the previous year, reflecting a rapidly strengthening economic relationship anchored by commodities, agriculture, and expanding technology ties.

The figures were disclosed by Russia’s Ambassador to Ethiopia, Evgeny Terekhin, in comments to Russian state media. He attributed the growth to rising Russian exports of fertilisers, agricultural machinery, and energy equipment, alongside increased Ethiopian exports of coffee, flowers, and textiles.

Coffee has emerged as the standout driver of the trade surge. Ethiopian beans—particularly the Sidamo and Harar varieties—have seen growing demand among Russian consumers.

According to the ambassador, Ethiopia’s coffee exports to Russia rose from about $46 million in 2024 to an inflation-adjusted $123 million in 2025. Import volumes more than doubled over the same period, increasing from 8,300 tonnes to approximately 18,300 tonnes.

“Traditional export items are acting as growth drivers,” Terekhin said, pointing to sustained demand on both sides.

Beyond agricultural trade, cooperation is expanding into digital commerce. Ethiopian authorities have granted Russian online marketplaces a regulatory “green corridor,” easing market entry requirements. Wildberries and Russ—now operating under the merged entity RWB—are preparing to begin operations in Ethiopia after adapting their platforms to local market conditions.

“The entry of Russian tech companies into the Ethiopian market is no longer theoretical,” Terekhin said, noting that technical integration and product localisation are already underway.

The strengthening trade relationship also includes industrial ambitions. At a bilateral intergovernmental commission meeting in November 2025, Russian aluminium producer Rusal signed agreements with Ethiopian Investment Holdings to explore the construction of an aluminium plant in Ethiopia.

If realised, the project could deepen industrial cooperation and expand Russia’s footprint in East Africa, further broadening a partnership that is increasingly being shaped by coffee-led trade growth.

Study Links Moderate Coffee Consumption to Brain Health

DUBAI – QAHWA WORLD

The saying about fruit and doctors might need an update: your daily cup of coffee could also play a role in keeping your mind active as you age.

Public debate around popular indulgences like coffee, tea, alcohol, and chocolate tends to swing back and forth. However, researchers based in Cambridge, Massachusetts have recently reported findings that place caffeinated drinks in a more positive light, particularly when it comes to long-term cognitive health.

A large research review drawing on decades of data and involving more than 130,000 adults observed an association between regular consumption of coffee or caffeinated tea and a lower likelihood of developing dementia. The analysis also suggested slower cognitive decline and better maintenance of mental performance among habitual caffeine consumers.

The researchers propose that compounds found in caffeinated coffee and tea may have neuroprotective properties, potentially helping to limit inflammation and cellular damage in the brain. These mechanisms are discussed as possible explanations for the observed relationship with cognitive outcomes.

The findings are especially relevant for older adults. Dementia diagnoses have risen sharply in recent years, and projections from health professionals anticipate a substantial increase in new cases in the coming decades. According to the study’s senior author, the widespread and routine nature of coffee consumption made it an appealing dietary factor to examine in the search for practical approaches to supporting brain health.

Earlier studies on caffeine and cognition often struggled to assess long-term effects or to separate outcomes by beverage type. By combining data from long-running cohort studies that tracked participants for more than four decades, the researchers were able to compare the cognitive trajectories of people who consumed caffeinated coffee, caffeinated tea, decaffeinated coffee, or little caffeine at all.

Within the study population, about 8% of participants developed dementia over time. Those who reported the highest intake of caffeinated coffee showed a notably lower risk compared with individuals who consumed minimal caffeine. Similar patterns were observed among tea drinkers, while decaffeinated coffee did not show the same association, leading the authors to focus on caffeine as a potential key factor.

As for quantity, the analysis pointed to moderate intake rather than excess. Approximately two to three cups of coffee per day, or one to two cups of tea, were associated with the most favorable cognitive outcomes.

The researchers also reported that the observed associations were consistent regardless of genetic predisposition to dementia, suggesting that caffeine’s potential benefits may apply across different levels of inherited risk.

That said, coffee is only one small element in a much broader picture. Dementia risk is strongly influenced by genetics and by health conditions such as high blood pressure, diabetes, obesity, physical inactivity, and mental health challenges. The authors emphasized that the effect linked to caffeine was modest and should be viewed as one possible component of a comprehensive approach to healthy aging.

In short, while caffeine is not a cure or a guarantee, moderate coffee or tea consumption may be one lifestyle factor associated with maintaining cognitive health later in life.

The Silent Cafe is Dying

By: Sonam Sherpa

We are living in a time where most of us know how to brew specialty coffee.

Great equipment, precise recipes, advanced processing methods everything is available. And yet, I’ve tasted many technically perfect brewed coffees that felt without lives.

What do I mean by coffee without life? As generations change, every industry evolves and coffee is no different. Brewing techniques are innovating faster than ever. But somewhere along this journey, we’ve started overlooking something far more important: the customer experience.

At the end of the day, the final goal isn’t the brew. It’s the person holding the cup.

Adding life to coffee doesn’t mean doing more complicated brewing. It means helping the customer feel that the coffee they’re paying for is worth it. Serving coffee alone isn’t enough anymore. Life is added when we share the story behind the cup,like

  1. Where the coffee comes from? 2.How it was processed ?

  2. What makes it unique? 4.Why it was roasted a certain way?

  3. How it’s meant to be experienced when brewed.

  4. And etc

Many of us already share this information. But what’s often missing is communication the ability to express it in a way that customer could connect. Not every customer wants technical details. What they want is something they can relate to. This is where storytelling becomes powerful. In the future, storytelling won’t just be a skill, it will be a necessity. The cafés that stand out will be the ones that communicate a beverage in a way that even a non-coffee drinker can understand and enjoy.

So here’s my encouragement to fellow coffee professionals and café owners:

Learn to tell stories. Learn to communicate. Because when a customer connects with the story, the coffee comes alive.

IKKA Gallery Debuts Reem Ali’s “On Practicing Recovery” this February

DUBAI – QAHWA WORLD

This February, IKKA reinforces its position as Dubai’s first restaurant to house a permanent, rotating gallery programme. By debuting contemporary works before they reach the traditional gallery circuit, IKKA continues to bridge the gap between fine dining and the UAE’s evolving art scene.

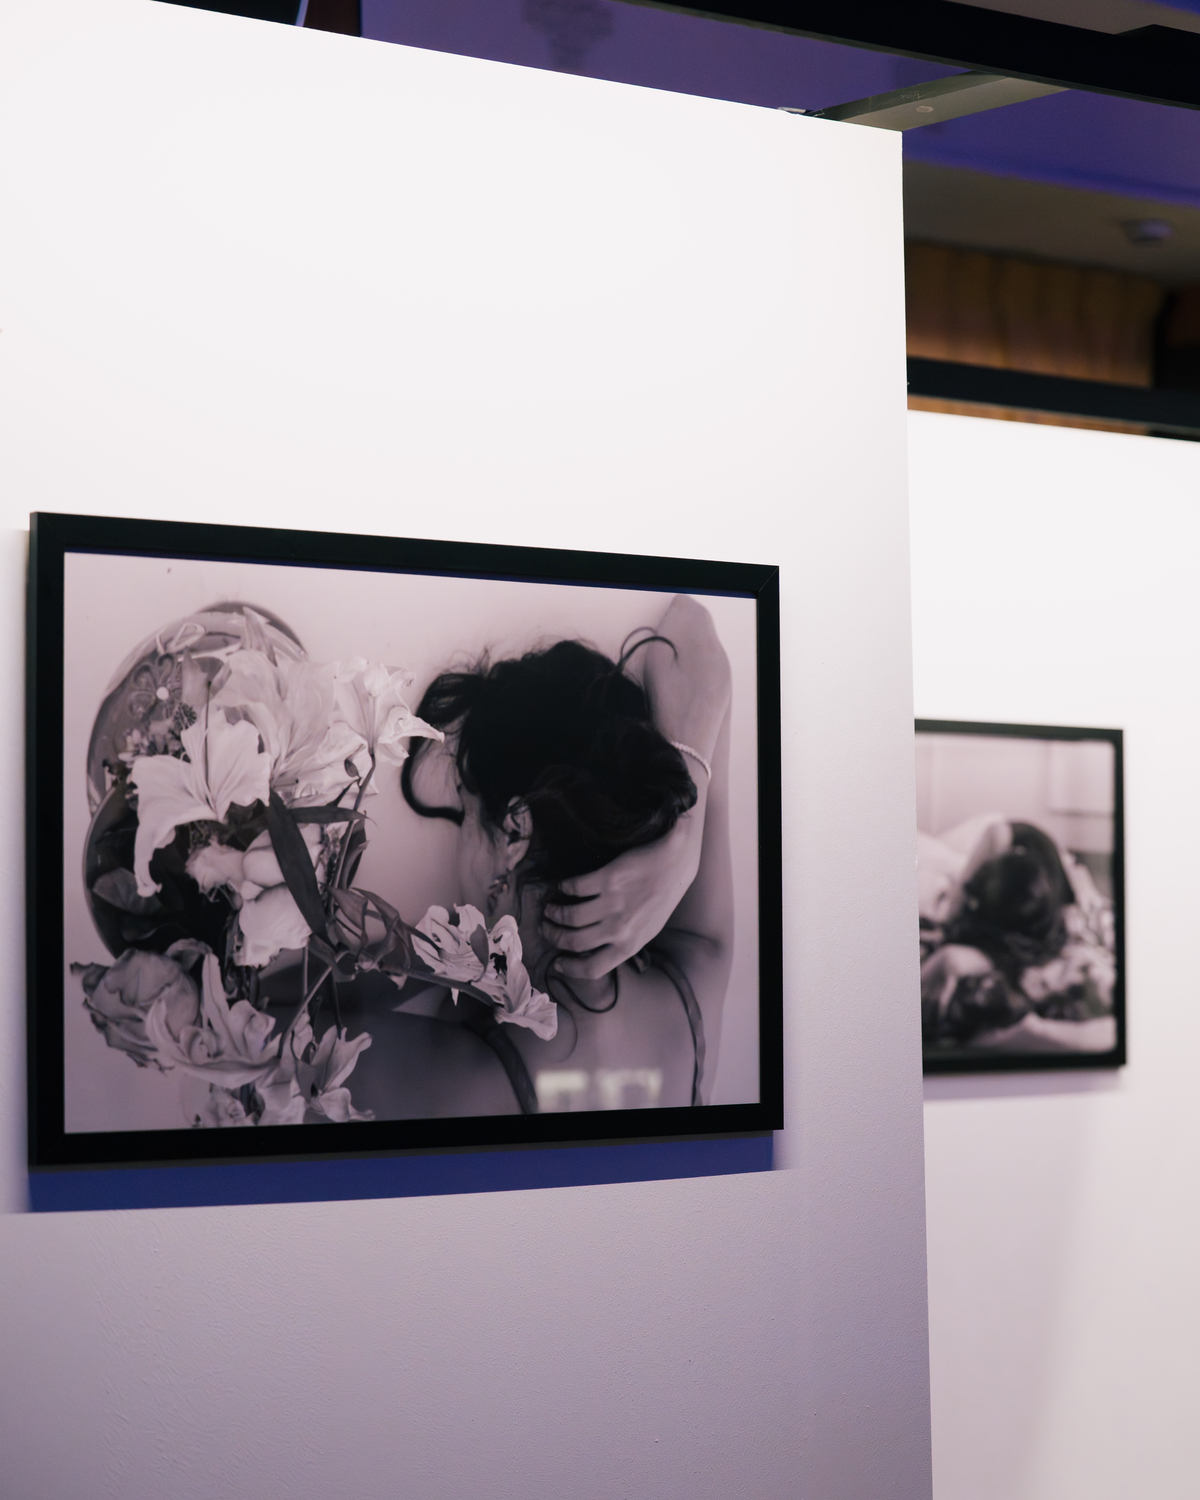
Following its successful January launch, the gallery presents “On Practicing Recovery” by Paris-based Saudi visual artist Reem Ali. Marking the artist’s Dubai debut, the exhibition follows a series of acclaimed showcases in Paris and will run from 4 to 28 February 2026.

A New Site for Contemporary Art Ali’s work explores recovery as an ongoing, non-linear process shaped by domestic space and women’s inner lives. Informed by her background in biology, her video and photography works offer a restrained, contemplative aesthetic that sits in deliberate contrast to the restaurant’s vibrant atmosphere.

At IKKA, the first encounter with new work unfolds through movement and shared experience. Art is experienced alongside the rhythm of the restaurant—integrated into the evening between shared plates, cocktails, and the venue’s signature rooftop energy.

  • Exhibition Details:

Artist: Reem Ali

Dates: 4th – 28th February 2026

Timings: 4:00 PM – 01:00 AM

Venue: IKKA, Hyatt Centric Jumeirah Dubai

Reservations: +971 43 021 275