Yemen: The Future of Drought-Resistant Coffee Amid Climate Change

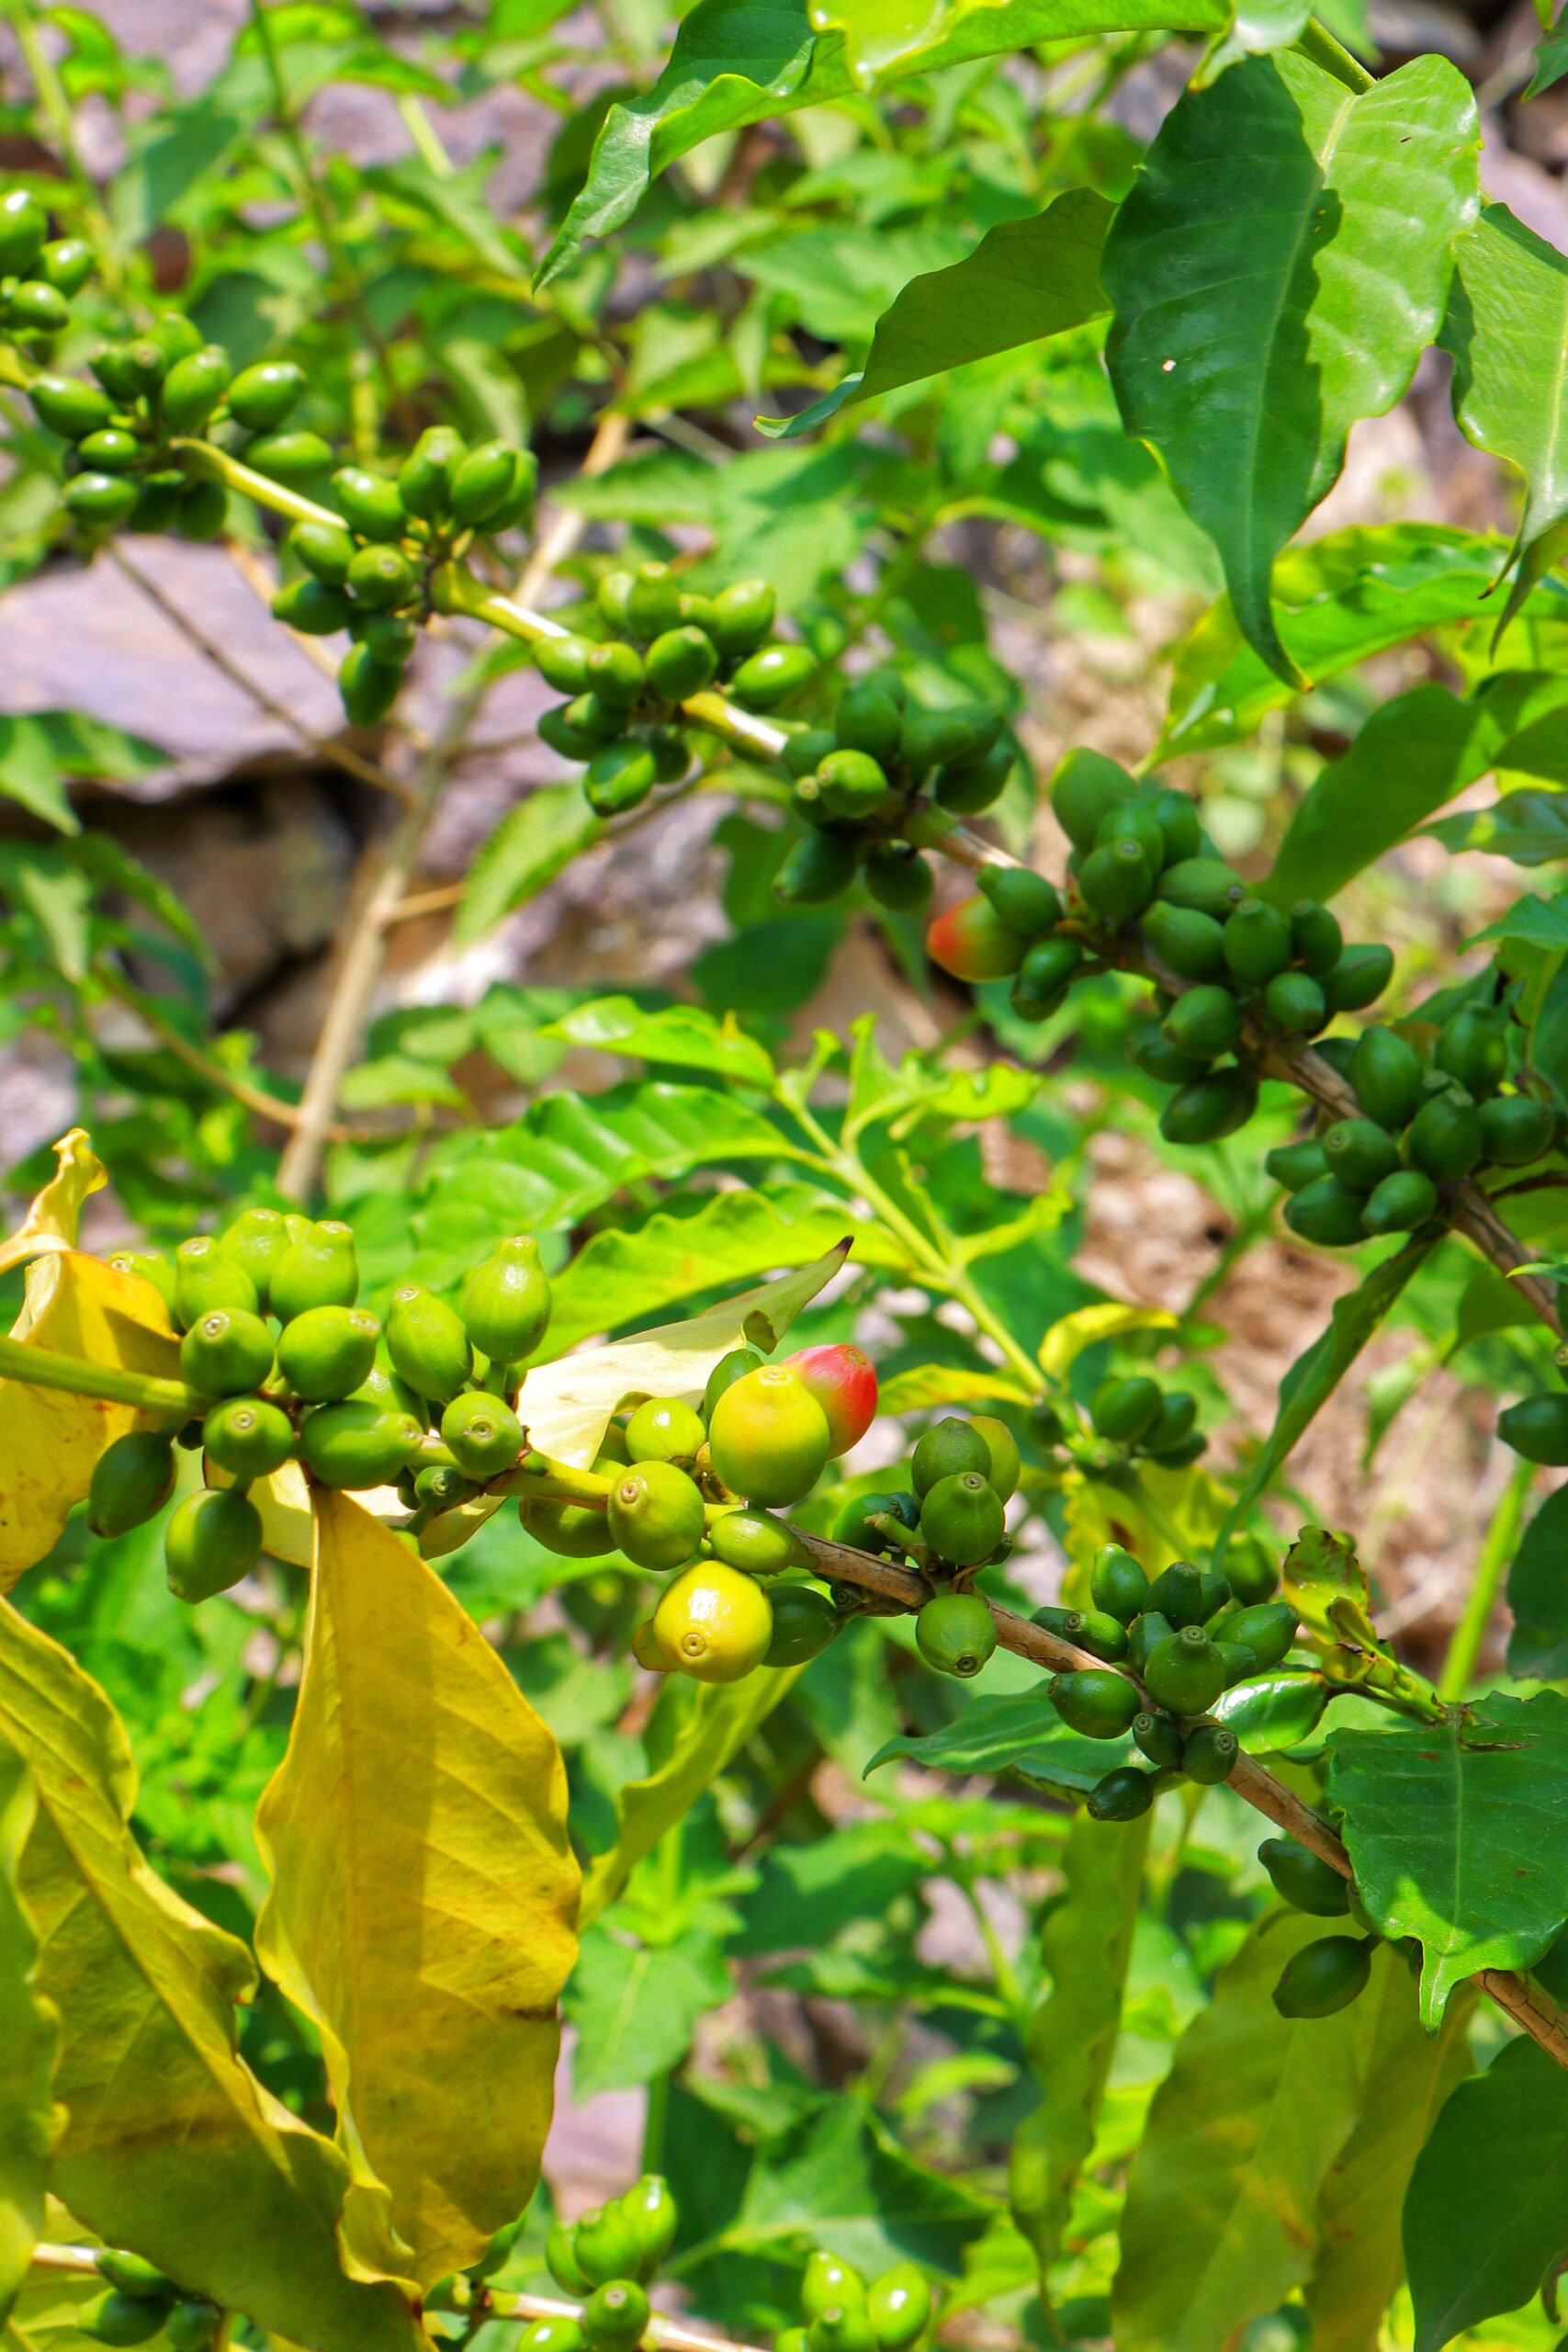
Dubai, 17 September 2025 (Qahwa World) –Coffee in Yemen has never been just a crop. It is deeply rooted in the nation’s history, culture, and identity. From these rugged mountains and arid landscapes, coffee spread across the seas more than five centuries ago to conquer global markets. Today, as climate volatility poses unprecedented threats to the coffee industry worldwide, Yemen is once again at the centre of attention—not only as the birthplace of coffee but also as a potential leader in producing drought-resistant varieties that could safeguard the sector’s future.

According to the latest DMCC Coffee Centre report, part of its Future of Trade Agri Series, climate change may render half of today’s coffee-growing land unsuitable for production by 2050. Arabica beans, which account for 60–70% of global production and are prized for their superior quality, are the most at risk. They require cooler climates and well-defined wet and dry seasons, making them highly sensitive to even slight shifts in rainfall and temperature.

Robusta, known for its resilience and tolerance to higher temperatures, may also face threats from ongoing climate disruptions. The report highlights that recent years have already offered a preview of this uncertain future. In Vietnam, prolonged drought caused production to fall by 20% and exports by 10% during the 2023/24 season. In Brazil, the world’s largest coffee producer, one of the most severe droughts in its history pushed Arabica prices up by more than 80% in 2024. These are not isolated incidents but warning signs of a shifting climate reality that threatens global supply.

Against this backdrop of instability, the DMCC report underscores Yemen’s exceptional position. For centuries, Yemeni farmers have cultivated coffee under harsh conditions—scorching heat, scarce rainfall, and limited water resources—yet the crop has endured. This historic resilience is what makes Yemen uniquely qualified to lead the development of drought-resistant coffee varieties that could redefine global production.

Garfield Kerr, president of the Speciality Coffee Association (SCA) and founder of Mokha 1450 in Dubai, put it bluntly: “I expect Yemen to become an industry leader in producing drought-resistant coffees, because farmers and agronomists there are already producing coffee in higher temperatures with less water.”

Garfield Kerr, President of the Specialty Coffee Association (SCA) and founder of Mokha1450

This statement reflects a growing global recognition that Yemen’s traditional practices and harsh realities may hold the key to coffee’s survival in the face of climate change.

The significance of Yemen lies not only in its ability to grow coffee under extreme conditions but also in the potential role it can play in stabilising global supply. If Yemen succeeds in pioneering drought-resistant varieties, it could help reduce the risks facing millions of smallholder farmers across Latin America, Africa, and Asia who are far less equipped to adapt to environmental shocks.

Economically, this advantage positions Yemen to capture new opportunities. With demand for resilient coffee varieties expected to rise, Yemen could evolve from a historically modest producer into a global laboratory for agricultural innovation. Strategic investment in research, farmer training, and international partnerships will be key to transforming this potential into reality.

The report also emphasises that farmers cannot bear the burden of climate adaptation alone. Institutions, trade bodies, and global buyers must work together to foster resilience across the supply chain. Yemen’s experience offers valuable lessons, but scaling them up will require cooperation, knowledge-sharing, and financial backing.

As consumer demand for sustainability and transparency intensifies, regulatory frameworks such as the European Union’s Deforestation Regulation are reshaping access to global markets. For Yemen, aligning with such frameworks could open doors while reinforcing its role as a pioneer in climate-smart coffee production.

Conclusion

The DMCC Coffee Centre report places Yemen firmly back in the global spotlight—not only as the birthplace of coffee but also as a crucial player in shaping its future. At a time when the sector faces escalating risks from droughts, heatwaves, and unpredictable weather, Yemen emerges as a beacon of resilience and possibility.

For the global coffee industry, the message is clear: climate change is already altering production landscapes, and the risks are intensifying. Yet Yemen’s centuries-old experience in cultivating coffee with fewer resources provides hope that adaptation is possible.

If the right investments and collaborations are put in place, Yemen could help secure coffee’s future—not just for itself, but for the millions worldwide whose livelihoods and cultures depend on this extraordinary crop.

DMCC Coffee Centre: Specialty Coffee Redefines the Global Market

DUBAI, 16 September 2025 (Qahwa -World) – Coffee is no longer just a daily beverage. It has become a cultural experience, a marker of taste, and a symbol of identity. Around the world, the specialty coffee sector is witnessing unprecedented growth, transforming the industry and reshaping global trade patterns. In its latest Future of Trade Agri Series report, the DMCC Coffee Centre emphasizes that this boom in specialty coffee is creating new opportunities but also deep challenges for producers, roasters, and supply chains.

From a simple drink to a global culture

Over the past decade, consumer behavior has shifted dramatically. Younger generations, particularly millennials and Gen Z, are no longer satisfied with a standard cup of coffee. They are seeking quality, transparency, and stories behind their brew. Today’s consumers want to know where their beans come from, how they were cultivated, and the social and environmental impact of the farms that produced them. This demand for authenticity and excellence has fueled explosive growth in the specialty coffee sector, which is expanding at a pace far faster than the commercial coffee market.

According to the report, demand for specialty coffee in Asia alone has surged by 30% over the past five years. Cities such as Shanghai, Tokyo, and Seoul have become leading destinations for coffee culture, rivaling long-established centers in Europe and North America. In the Middle East, Dubai has emerged as a hub for specialty coffee, where entrepreneurs, importers, and consumers converge in a market that views coffee as more than a drink—it is a lifestyle, a cultural statement, and a shared experience.

Yet behind this expansion lies a paradox. While specialty coffee commands premium prices in consumer markets, smallholder farmers—who account for about 80% of global production—struggle to secure a fair share of that value. The DMCC Coffee Centre report highlights the growing disconnect between international futures market pricing and the specialty coffee segment. Futures contracts may indicate falling prices, but specialty beans often continue to rise, placing roasters and consumers under pressure and leaving farmers in a vulnerable position.

Garfield Kerr, President of the Specialty Coffee Association and founder of Dubai’s “Mokha 1450,” describes the situation: “The gap between traditional pricing mechanisms and the real specialty market is destabilizing. We need systems that reward quality fairly and ensure that farmers share in the added value created by specialty coffee.”

Garfield Kerr, President of the Specialty Coffee Association (SCA) and founder of Mokha1450

The report also underscores the role of technology in supporting this sector. Tools such as blockchain and artificial intelligence are becoming essential for verifying sustainability claims and ensuring traceability from farm to cup. These innovations build consumer trust while giving farmers a platform to demonstrate the authenticity of their practices. With regulatory frameworks such as the European Union’s anti-deforestation law, transparency is no longer optional but a requirement for accessing major markets.

Meanwhile, emerging regions like the Gulf are helping shape new patterns of demand. In cities like Dubai, Riyadh, and Doha, specialty coffee has become integral to modern lifestyle and self-expression, placing the Middle East firmly on the global coffee map as both a consumer base and a trade hub.

Dubai’s role is especially significant. The DMCC Coffee Centre not only provides world-class infrastructure for storage, roasting, and packaging but also offers pay-as-you-go services that lower barriers for small producers in Africa and Latin America. By connecting them directly to international buyers, Dubai positions itself as a stabilizing force in a rapidly shifting specialty coffee economy.

Looking ahead, the future of specialty coffee appears both bright and complex. Growth projections estimate annual expansion of over 7% in the coming decade, signaling strong demand. Yet challenges remain. Farmers must invest in training, innovation, and resilience to maintain quality, while roasters and traders must navigate volatile pricing and rising logistics costs.

The DMCC Coffee Centre’s report concludes that the specialty coffee boom is not simply a trend but a structural transformation of the global coffee market. Success will depend on the industry’s ability to balance demand with sustainability, fairness, and transparency. If achieved, specialty coffee will not only be a product of distinction but also an economic and cultural cornerstone capable of redefining global trade—and reinforcing Dubai’s role as a hub at the heart of this transformation.

DMCC Coffee Centre: Supply Chain Pressures and Tariffs Threaten Global Coffee Trade

Dubai, 15 September 2025 ( Qahwa World) – Coffee, the world’s second most traded commodity after oil and a cultural staple for billions, is entering a critical stage in its global journey. The threats facing the industry are no longer confined to climate change alone. Increasingly, they include mounting supply chain disruptions and escalating tariffs that are reshaping the economics of one of the most vital agricultural products on earth. In its latest report, released as part of the Future of Trade Agri Series, the DMCC Coffee Centre warns that unless urgent measures are taken, the future of the global coffee trade may be defined by instability, rising costs, and deep uncertainty.

For decades, coffee has been regarded as a model commodity for international trade thanks to its durability and storability as green beans. But according to the report, this traditional advantage is no longer sufficient. Shipping costs have risen sharply amid ongoing global supply chain disruptions, compounded by geopolitical tensions across key trade corridors such as the Red Sea and the Panama Canal. Even a 1% increase in transport costs, the report notes, can result in months of accumulated price hikes for coffee worldwide. What was once a relatively resilient supply chain has become a fragile lifeline vulnerable to external shocks.

The situation has been further aggravated by protectionist trade policies. Most notably, the United States recently imposed tariffs of up to 50% on coffee imports from Brazil, the world’s largest exporter. While this may appear to offer short-term relief for American markets, it has shaken investor confidence and created uncertainty for Brazilian producers who rely heavily on exports. Many growers now face the prospect of cutting back production or seeking alternative markets, both of which come with risks of their own.

Mike Butler, Assistant Director for Coffee at DMCC, described the dilemma: “Large buyers often have the option of stockpiling coffee to protect themselves against price swings, but this strategy is not available to everyone. Smallholder farmers and specialty roasters remain the most exposed, as they lack the resources to hedge or hold inventories for long periods.”

The pricing system itself is also under strain. For decades, futures markets like the Intercontinental Exchange (ICE) provided reliable benchmarks for coffee. But the DMCC report highlights how these benchmarks are increasingly detached from reality. Futures contracts may show declines, while specialty coffee prices remain elevated, squeezing small and medium-sized roasters who cannot reconcile speculative market prices with real-world sourcing costs. Garfield Kerr, President of the Specialty Coffee Association and founder of Dubai’s “Mokha 1450,” summed it up: “The futures market has become more speculative and no longer reflects the actual value of high-quality coffee.”

Adding to this pressure is the rapid transformation of consumption patterns. Across Asia—in countries like China, Japan, and the Philippines—demand for coffee is accelerating, particularly among younger generations seeking premium quality and unique experiences. This growth, while promising, makes these markets especially vulnerable to global supply shocks. A shipping delay in Brazil or a tariff dispute in the U.S. can now ripple instantly into cafés and supermarkets in Beijing or Manila, underscoring the fragility of today’s interconnected coffee economy.

Amid these challenges, Dubai is positioning itself as a stabilizing hub. The DMCC Coffee Centre offers a pay-as-you-go model for storage, roasting, packaging, and logistics, lowering barriers for producers and small exporters to access global markets. Its geographic location at the crossroads of Africa, Asia, and Latin America allows Dubai to act as a natural bridge, absorbing shocks and keeping trade flows alive even in turbulent times. This strategic advantage, the report argues, could prove decisive as volatility becomes the new normal.

Still, the outlook remains precarious. Global production is expected to reach a record 178.7 million bags in the 2025/26 season. But without meaningful reforms, these volumes may not translate into market stability. Tariffs, freight costs, and speculative pricing continue to weigh heavily on the system, leaving more than 25 million smallholder farmers—who form the backbone of global coffee production—on the edge of economic survival.

The DMCC Coffee Centre’s report concludes with a stark choice. Either the industry embraces international cooperation, reforms outdated pricing mechanisms, and invests in supply chain infrastructure, or it risks plunging into prolonged volatility. Coffee, long celebrated as a symbol of connection and culture, could instead become a mirror of global trade’s fragility. But with decisive action, from fairer pricing models to transparent trade systems and collaborative investment, the industry has the tools to safeguard coffee’s future as a unifying global commodity.

DMCC Coffee Centre Warns: Climate Volatility Threatens the Future of Global Coffee

DUBAI – September 2025 – Qahwa World – Coffee is more than a beverage. It is a lifeline for over 25 million smallholder farmers, a $200 billion industry, and a cultural anchor with more than two billion cups consumed daily. Yet today, the global coffee sector faces one of the greatest challenges in its long history, according to the DMCC Coffee Centre, part of the Dubai Multi Commodities Centre (DMCC).

In its latest report, released under the Future of Trade Agri Commodities Series, the DMCC Coffee Centre published a special edition on coffee, warning that lands where coffee has thrived for centuries may no longer be suitable for cultivation in the coming decades.

According to the report, coffee’s vulnerability to climate change is stark. Unlike many other crops, coffee can only be cultivated in limited geographical zones, often at specific altitudes and within narrow temperature ranges. Any disruption in this balance — whether through droughts, frosts, or fungal diseases such as coffee leaf rust — can devastate entire harvests. Recent years have offered a preview of this future. In Vietnam, prolonged drought cut production by 20% and exports by 10% in the 2023/24 season. In Brazil, the world’s largest producer, one of the worst droughts in history pushed Arabica prices up by more than 80% in 2024. These are not isolated events but warning signals of a changing climate destabilizing a vital crop.

Research cited in the report projects that by 2050, half of today’s coffee-growing land may become unsuitable. Arabica, which accounts for 60–70% of global production and is prized for its quality, is the most at risk. Dependent on cooler climates with clearly defined wet and dry seasons, Arabica is highly sensitive to even modest increases in temperature. Robusta, known for its greater heat tolerance, may also face challenges under worsening climate conditions.

“The reality is that producers often have customers who have pre-booked volumes months in advance,” said Mike Butler, Associate Director of Coffee at DMCC. “If crops fail, they cannot deliver. This puts enormous pressure on farmers and traders, making climate volatility the new normal.”

Mike Butler, Associate Director of Coffee at DMCC

These pressures are already reshaping market dynamics. When Arabica prices surge, major brands increasingly turn to Robusta to fill the gap, often blending higher proportions into espresso and instant products. But as Garfield Kerr, President of the Specialty Coffee Association (SCA) and founder of Mokha1450 in Dubai, explains: “Specialty coffee consumers will notice the difference. While efforts are underway to develop specialty-grade Robusta, its flavor profile remains distinct.” This divergence could redefine what consumers drink, as well as where and how coffee is cultivated in the decades ahead.

Garfield Kerr, President of the Specialty Coffee Association (SCA) and founder of Mokha1450

The effects of climate change extend beyond farms to disrupt the global trade system. Shortages in Brazil or Vietnam ripple across supply chains, triggering price spikes and reshaping import decisions worldwide. Exchange-based pricing, once a reliable benchmark for roasters, is increasingly disconnected from the realities of specialty markets. Butler notes: “We are in a complex situation. Exchange pricing has become speculative and detached from the actual market, especially in premium segments.”

For smallholder farmers — who produce 80% of the world’s coffee — volatility is a fight for survival. Most lack the resources to withstand failed harvests or price shocks. When yields collapse, so too does income, jeopardizing education, healthcare, and food security for millions of families. The DMCC Coffee Centre report stresses the urgent need for investment in climate adaptation strategies that enable farmers to continue producing under increasingly hostile conditions.

Among the most promising solutions is agroforestry, where coffee is cultivated alongside trees and diverse crops to shield plants from heat, improve soil fertility, conserve water, and diversify incomes. Developing drought-resistant coffee varieties is another frontier. Kerr highlights Yemen as a potential leader, where farmers have for centuries produced resilient coffees in arid, high-temperature conditions. “I expect Yemen to become an industry leader in producing drought-resistant coffees,” he says, “because its farmers and agronomists already grow coffee in hotter climates with less water.”

The urgency of innovation extends beyond agriculture. International institutions and trade hubs must foster collaboration, data-sharing, and investment to support producers. The International Coffee Organization, in partnership with the International Trade Centre, has launched a Coffee Sustainability Support Database cataloguing more than 400 climate and sustainability initiatives worldwide. From training farmers in composting techniques to supporting cooperative-led climate projects, such efforts highlight the collective action required to build resilience.

Still, adaptation alone may not suffice without broader systemic change. Consumers increasingly demand proof that their coffee is produced sustainably and ethically, and regulators are responding with measures such as the European Union Deforestation Regulation. Compliance requires end-to-end traceability, raising costs but also creating opportunities for new technologies like blockchain and AI-powered monitoring to ensure that sustainability commitments are verifiable.

The DMCC Coffee Centre concludes that the global coffee sector stands at a crossroads. Climate change is already disrupting production, and risks are intensifying. While forecasts suggest that production could reach a record 178.7 million 60-kg bags in 2025/26, long-term threats loom over both supply and the livelihoods of millions of farmers. At the same time, solutions — from agroforestry to resilient varieties, from digital transparency to circular economy models — are emerging. The question is not whether the industry will change, but whether it can adapt quickly enough to safeguard coffee’s future.

For an industry that spans continents and cultures, the message is clear: without urgent action, climate volatility could reshape the coffee world beyond recognition. But through innovation, cooperation, and resilience, coffee can remain what it has always been — not just a drink, but a global connector, an economic pillar, and a cultural force.

Shocking Discovery: Just One Cup of Coffee May Reduce Donor Blood Quality

Dubai, September 8, 2025 (Qahwa World) – A groundbreaking study published in Haematologica has revealed that caffeine, the world’s most widely consumed stimulant, can significantly reduce the quality of stored donor blood, potentially limiting the benefits of transfusions for patients.

The research, based on data from more than 13,000 blood donors, examined caffeine levels and their impact on red blood cell function during storage. The results showed that blood taken from donors with high caffeine exposure was more fragile and less effective after transfusion. The cells demonstrated depleted energy reserves such as adenosine triphosphate, reduced levels of 2,3-bisphosphoglycerate, and increased oxidative stress markers, making them more prone to breakdown.

The study further revealed that not all donors were affected equally. Negative effects were especially pronounced among individuals carrying variants of the ADORA2b gene, which regulates how red blood cells adapt to low oxygen. When caffeine blocks this receptor, stored blood deteriorates faster, resulting in weaker clinical outcomes for transfusion recipients.

Laboratory experiments confirmed that caffeine’s harm operates on two fronts: first, by blocking ADORA2b signaling, and second, by directly inhibiting glucose-6-phosphate dehydrogenase, a key enzyme responsible for red cell antioxidant defenses. This dual mechanism leaves cells more vulnerable to oxidative stress and shortens their survival after transfusion.

The health implications are significant. With more than twelve million units of blood transfused annually in the United States alone, even small reductions in blood quality can have widespread consequences. Encouragingly, caffeine is a modifiable factor. Because of its short biological half-life, abstaining from coffee or caffeinated drinks for even a single day before donation may improve blood quality. Some European countries already advise donors to avoid caffeine, while in the United States and Italy it is sometimes encouraged to help raise blood pressure temporarily, easing the donation process.

Researchers, led by Professor Angelo D’Alessandro of the University of Colorado, emphasize that these findings highlight the need for a more personalized approach to transfusion medicine. In addition to blood type, factors such as lifestyle and genetic background should be considered to ensure the highest quality units are directed to patients most at risk, such as infants or individuals with severe anemia.

The paradox is striking: the same mechanisms that make caffeine harmful for stored blood may explain its appeal to athletes. A modest increase in oxidative stress can stimulate adaptation in the body, improving endurance. But inside blood banks, this effect translates into weaker units and reduced potential to save lives.

Roasted and Soluble Coffee Exports Decline in July 2025

Dubai, September 6, 2025 (Qahwa World) – The International Coffee Organization’s (ICO) August 2025 report has revealed a significant decline in exports of both roasted and soluble coffee in July, underscoring new challenges facing the global coffee sector as it navigates volatile prices, shifting demand, and rising production costs. The data highlights not only pressure on green coffee but also on finished products that reach consumers directly, raising concerns about structural changes in the industry.

According to the report, roasted coffee exports fell by a dramatic 63%, reaching only 30,000 bags compared to 81,000 bags in July 2024. This steep contraction marks one of the sharpest drops in recent years for a category that reflects direct consumer demand for value-added coffee products. Soluble coffee exports also registered a decline, albeit more modest, down 5% to 1.08 million bags from 1.13 million bags a year earlier. While less severe, the slowdown in soluble exports is significant because this category has long been considered one of the most resilient and widely consumed segments in global markets, particularly in emerging economies.

Analysts attribute the decline in roasted coffee exports to several interlinked factors. The most immediate is the surge in global coffee prices, with the ICO Composite Indicator Price (I-CIP) climbing by 14.6% in August to 297.05 US cents per pound, its highest level since 2024. Such historic price levels have curbed demand for high-cost roasted products, especially in advanced markets such as Europe and North America, where consumers are already grappling with inflation and higher living expenses. At the same time, exporters face mounting challenges from rising production and shipping costs. Energy, labor, and logistics expenses have all increased in recent months, eroding margins and forcing some companies to scale back international shipments in favor of local markets where conditions are more stable.

For soluble coffee, the 5% drop highlights a different dynamic. Traditionally, this segment has thrived in developing and price-sensitive markets due to its affordability and convenience. Yet even here, demand appears to be shifting. In mature markets, growth has slowed as consumers gravitate toward specialty coffee and fresh roasted options, reflecting a broader trend toward quality and experience rather than convenience alone. In competitive producing countries such as Vietnam and India, rising production capacity has intensified rivalry, putting pressure on exporters to maintain prices and market share. Younger generations in many countries are also seeking more diverse coffee experiences, leading to gradual erosion in the dominance of instant coffee.

The decline in both roasted and soluble exports has broader economic implications. It signals that pressure in the coffee sector is not limited to green coffee or raw supply but extends throughout the value chain. Combined with the ICO’s data showing global coffee stocks at their lowest level since April 2024, the contraction in finished product exports adds another layer of vulnerability to a market already characterized by price volatility and supply uncertainty. Experts warn that if these trends persist, the industry could face an extended period of turbulence, with higher prices for consumers and tighter margins for producers.

Still, opportunities remain in certain regions. Demand for soluble coffee continues to expand in parts of Africa and Asia, albeit at a slower pace, offering some relief for exporters. However, regulatory challenges such as the upcoming EU Deforestation Regulation (EUDR), set to take effect at the end of 2025, are expected to add new hurdles for suppliers attempting to maintain access to key European markets. For roasted coffee, niche segments such as specialty blends and locally branded products may offer pathways to sustain growth, but producers will need to adapt quickly to changing consumer preferences.

The ICO emphasized that roasted and soluble coffee exports should be monitored closely as indicators of global consumption trends. If the declines seen in July extend over the coming months, it could mark the beginning of a deeper shift in how coffee is traded and consumed worldwide. In that scenario, volume alone would no longer be the main metric of success; value-added innovation, consumer engagement, and adaptability to regulatory and market changes would become critical to survival. For now, the combined 63% plunge in roasted coffee exports and the 5% drop in soluble shipments serve as a stark reminder that the challenges facing the coffee sector go beyond farms and warehouses and reach all the way to the consumer’s cup.

Global Coffee Stocks Fall to Lowest Level Since April 2024

Dubai, September 4, 2025 (Qahwa World) – The International Coffee Organization’s (ICO) August 2025 report has revealed a sharp decline in global coffee stocks, falling to their lowest level since April 2024. The drop in inventories comes just weeks after prices reached a historic high, highlighting a fragile market caught between soaring demand and tightening supply.

According to the ICO, certified Arabica stocks held at the New York Exchange dropped 7.9% to 0.77 million bags, marking a 16-month low. Robusta inventories at the London Exchange also fell by 4.6%, standing at 1.13 million bags. The simultaneous reduction across both major coffee types signals a broad squeeze on available supply.

Why Stocks Are Falling

Analysts point to several reasons behind the decline:

  • Weaker export flows – Global green coffee exports fell for the sixth consecutive month in July 2025, tightening supplies into key markets.

  • Crop concerns – Brazil, the world’s top producer, reported larger bean sizes but weaker density, which reduced overall yield estimates.

  • Climate risks – A frost in Brazil earlier this year damaged an estimated half a million bags.

  • Regulatory pressure – European roasters have been stockpiling ahead of the EU Deforestation Regulation (EUDR) that comes into force at the end of 2025, drawing beans out of certified warehouses into private storage.

Connection to Soaring Prices

The fall in stocks coincided with a dramatic rise in prices. In August, the ICO Composite Indicator Price (I-CIP) climbed 14.6% to 297.05 US cents per pound, the highest since 2024. With inventories shrinking, the likelihood of further price volatility is increasing, especially if supply disruptions persist.

Regional Dynamics

  • South America posted the steepest decline, with exports down 18.5%, driven by a 28.6% fall in Brazil.

  • Asia & Oceania moved in the opposite direction, growing exports 22.7%, led by Vietnam (+29.4%) and Indonesia (+20.4%).

  • Africa also contributed positively, with exports rising 4.4%, thanks to strong performance in Uganda (+51.4%) and Ethiopia (+12.5%).

  • Mexico & Central America recorded moderate growth of 7.2%, helping to diversify global supply, though not enough to offset South America’s losses.

What It Means for the Market

Industry experts warn that the current drawdown in stocks leaves the coffee market more vulnerable to external shocks. Further weather events in Brazil or Vietnam could deepen the supply gap, while the EUDR may slow exports to Europe. Rising shipping and labor costs add another layer of pressure on the supply chain, feeding into higher costs for roasters and consumers alike.

Outlook

The ICO emphasized that stock levels will remain a critical indicator for the market in the coming months. Any further declines could trigger another round of price surges, prolonging uncertainty for producers, traders, and consumers. With prices already at historic highs and inventories at multi-year lows, coffee is entering one of its most volatile periods in recent memory

ICO: Coffee Prices Hit Historic Surge as Exports Decline

Dubai, September 3, 2025 (Qahwa World) – The International Coffee Organization (ICO) in its August 2025 report revealed unprecedented shifts in the global coffee market, with the ICO Composite Indicator Price (I-CIP) rising by 14.6% to 297.05 US cents per pound – its highest level since 2024 and 24.3% higher year-on-year. At the same time, the report highlighted that global green coffee exports continued to contract for the sixth consecutive month, underscoring the dual pressure of soaring prices and shrinking supplies.

Historic Price Surge
According to the ICO, all coffee groups recorded strong gains. Robusta led the surge with a 19.1% increase to 199.13 US cents per pound, while Colombian Milds, Brazilian Naturals, and Other Milds rose between 12% and 14%. Futures prices also jumped sharply, with New York contracts up 13.6% and London contracts up 18.2%, signaling broad-based upward momentum.

Market Drivers
The report identified multiple factors fueling the rally:

  • The United States’ 50% tariff on Brazilian coffee, slowing down commercialization.

  • Brazil’s government support through the Funcafé fund, allocating BRL 6.8 billion (USD 1.29 billion) to finance the 2025/26 harvest.

  • Reports of lower bean density in Brazil despite large screen size, reducing crop estimates.

  • European roasters stockpiling ahead of the EU’s Deforestation Regulation (EUDR) deadline in December 2025.

  • A minor frost in Brazil damaging up to half a million bags.

  • Roasters increasing long positions in futures markets to hedge against further price hikes.

Export Downturn
The ICO report also showed global green coffee exports reaching 10.3 million bags in July 2025, down 0.7% from July 2024. South America posted the steepest decline (-18.5%), driven by Brazil’s 28.6% fall in shipments.

Regional Contrasts

  • Asia & Oceania exports surged by 22.7%, led by Vietnam (+29.4%) and Indonesia (+20.4%).

  • Africa’s exports rose 4.4%, with Uganda (+51.4%) and Ethiopia (+12.5%) as key contributors.

  • Mexico & Central America posted a moderate increase of 7.2%.

Looking Ahead
The ICO emphasized that the combination of rising prices and falling exports places the global coffee market in a volatile phase. With the EUDR coming into effect by year-end and climate-related risks looming over major producers, coffee is set to remain one of the most vulnerable agricultural commodities to both economic and environmental shocks.

Roasted Arabica Coffee Contains Natural Compounds That Fight Diabetes

Dubai, September 3, 2025 (Qahwa World) – A new scientific study has revealed that roasted Arabica coffee beans contain natural compounds with powerful blood sugar–lowering effects, stronger than the widely used antidiabetic drug acarbose.

Researchers successfully identified three novel diterpene esters, named Caffaldehyde A, B, and C, which showed significant inhibition of the enzyme α-glucosidase, a key factor in blood sugar regulation. In addition, three more diterpenes with similar effects were discovered, reinforcing coffee’s role as a functional food with health benefits beyond basic nutrition.

Coffee as a Functional Food

Functional foods are those that contain biologically active compounds providing added benefits such as antioxidant protection, neuroprotection, lipid regulation, and blood sugar control. Coffee is not only one of the most consumed beverages worldwide but also one of the most economically valuable crops.

More than 70 diterpenes have been documented in coffee so far. Among them, kahweol and cafestol stand out for their anticancer and antidiabetic properties. However, roasted coffee remains chemically complex, making the discovery of new active compounds a challenging yet essential task.

Research Methodology

The research team employed advanced techniques combining Nuclear Magnetic Resonance (NMR) with Liquid Chromatography–Mass Spectrometry (LC-MS/MS). This innovative approach enabled faster detection of bioactive molecules while reducing solvent use, making the process more efficient and eco-friendly.

Findings

The diterpene extract was divided into 19 fractions. Fractions 9–13 exhibited the highest α-glucosidase inhibitory activity, leading to the discovery of three novel compounds – Caffaldehyde A, B, and C. These were structurally confirmed and shown to lower blood sugar effectively.

Additionally, three other compounds were identified: magaric acid, octadecenoic acid, and nonadecanoic acid, which also showed promising inhibitory activity.

Conclusion

This discovery demonstrates that roasted Arabica coffee beans are more than a daily beverage – they are a rich source of natural compounds with strong therapeutic potential. The identification of six novel compounds represents a significant step in understanding coffee’s health role and opens the door for developing innovative nutritional and medical approaches to diabetes management.

As coffee continues to hold its place as a cultural and economic staple, it also reveals itself as a functional food with the potential to support better public health and inspire further natural treatment research.

Nut Milks in Coffee: Healthier, But Do They Match Dairy’s Taste?

August 28, 2025 – (Qahwa World) – The coffee world has long been familiar with debates about dairy versus alternatives, but a groundbreaking study from South Korea has now provided the most detailed comparison yet of how nut-based milks perform in espresso drinks. The findings reveal that while cow’s milk remains the preferred choice for taste and texture, nut milks—particularly when roasted—offer unique health advantages and the potential for future innovation in coffee beverages.

Background: The Rise of Plant-Based Milks

Growing concerns over lactose intolerance, cholesterol, and the environmental footprint of dairy farming have fueled global demand for plant-based milk alternatives. Almond, cashew, hazelnut, and walnut milks have emerged as popular options, often promoted for their nutritional value and lower environmental impact. Yet little scientific research has explored how these nut milks behave when combined with coffee, particularly in terms of sensory appeal and chemical composition.

This new study, conducted by researchers at Dongguk University in Seoul and published in Scientific Reports, set out to fill that gap. The team prepared espresso-based beverages using roasted Brazilian arabica coffee and each of the four nut milks, in both roasted and unroasted forms, then compared them against traditional cow’s milk coffee.

The Science Behind Nut Milks in Coffee

The researchers examined multiple factors:

  • Fatty acid composition

  • Antioxidant activity

  • Volatile compounds (aroma contributors)

  • Particle size and viscosity

  • Color and browning index

  • Sensory evaluation by trained tasters

Roasting nuts before milk preparation had a profound impact. Oleic, linoleic, and linolenic acids—all beneficial unsaturated fatty acids linked to heart health—rose significantly in roasted nut milks. These drinks also exhibited higher antioxidant activity and polyphenol content, key markers associated with reduced oxidative stress in the body.

On the flip side, nut-based coffees tended to have larger particle sizes and higher viscosity compared to cow’s milk, factors that influenced mouthfeel and overall smoothness.

Volatile Compounds and Aroma Profiles

Gas chromatography identified 33 volatile compounds across the samples. Cow’s milk coffee stood out for floral and sweet notes such as furfuryl acetate and 5-methyl furfural, while nut milks contained more aldehydes and pyrroles, compounds characteristic of nutty aromas.

For example, almond milk coffee showed high levels of benzaldehyde, the chemical responsible for the distinct bitter-almond scent. Cashew and walnut-based versions contained other aldehydes linked to roasted and woody notes. These chemical profiles shaped the sensory outcomes, sometimes creating bitterness or lingering aftertastes that reduced preference scores.

Sensory Results: Dairy Still Dominates

Seventeen trained panelists evaluated all beverages for sweetness, bitterness, texture, nuttiness, and overall acceptance. Cow’s milk consistently ranked highest for sweetness, creaminess, and general preference.

Among the nut milks, cashew milk scored the highest, followed by almond and roasted hazelnut. Roasted walnut milk was the least favored. The study attributed the lower ratings of nut milks partly to aldehydes that impart undesirable flavors and to textural differences caused by larger particles.

Despite this, researchers stressed that nut milks still show strong promise:

“Nut-based milk coffee demonstrated potential as a health-promoting beverage owing to its high unsaturated fatty acid content and antioxidant effects,” the authors wrote.

Health and Sustainability Advantages

Nutritionally, nut milks have clear advantages. Compared with cow’s milk, they contained:

  • Lower levels of saturated fat

  • Higher levels of unsaturated fatty acids (linked to cardiovascular benefits)

  • Greater antioxidant activity (especially in roasted versions)

From an environmental perspective, the use of nuts in plant-based beverages reduces reliance on livestock farming, which is resource-intensive in terms of water, land, and greenhouse gas emissions.

The Road Ahead: Improving Flavor and Texture

While health benefits are evident, the researchers acknowledged that consumer acceptance remains limited by flavor and mouthfeel. They recommended further work to:

  • Control aldehyde production during processing to minimize off-flavors

  • Conduct additional physical experiments to refine texture and improve creaminess

  • Explore roasting parameters to optimize antioxidant release without compromising taste

These steps, they argue, could help close the sensory gap between nut milks and cow’s milk, paving the way for a new generation of plant-based coffee beverages that balance health, sustainability, and taste.

A Shift in the Coffee Industry?

The study’s findings come at a time when cafés worldwide are diversifying their menus with oat, soy, and nut milks to cater to vegan and health-conscious consumers. While dairy still dominates, particularly in espresso-based drinks, this research signals that the future of coffee could include more scientifically engineered plant-based options that rival dairy not only in nutrition but also in flavor.

For coffee lovers, that could mean healthier cappuccinos and lattes without sacrificing the sensory experience that makes café culture so irresistible.

Barista Terminology | Episode 14: Coffee Origins and Their Flavour Profiles

Qahwa World continues its “Barista Terminology” series, reaching today the fourteenth installment of this educational journey dedicated to enhancing the professional and cultural knowledge of baristas. In this episode, we examine some of the most prominent coffee-producing countries worldwide, highlighting their pivotal role in shaping the history of coffee and its global cultural and economic impact.

Coffee’s origin is more than just a label—it is the foundation of its identity. Soil, climate, altitude, and processing methods shape each region’s unique character. For baristas and enthusiasts alike, understanding coffee origins means understanding the story behind every cup.

  1. Ethiopia
  • Widely accepted as the birthplace of coffee.
  • Known for floral, fruity, and tea-like flavors.
  • Often features bright acidity and a light, elegant body.
  • Famous growing regions: Yirgacheffe, Sidama, Harrar.
  1. Yemen
  • The first country to cultivate and export coffee.
  • Produces earthy, winey, and spicy coffees with wild complexity.
  • Grown in terraced mountains with minimal irrigation.
  • Traditional dry processing preserves deep, rustic character.
  1. Brazil
  • The world’s largest coffee producer.
  • Known for chocolatey, nutty, and low-acid profiles.
  • Often used in espresso blends for its sweetness and heavy body.
  • Mechanized harvesting and large estates dominate production.
  1. Colombia
  • Offers balanced coffees with caramel, nut, and red fruit notes.
  • Known for clean cup quality and medium body.
  • Coffee is grown across various altitudes and microclimates.
  • A staple for many brewing styles.
  1. Kenya
  • Renowned for vibrant acidity and juicy, wine-like profiles.
  • Notes include blackcurrant, grapefruit, and floral tones.
  • Coffee auctions and grading systems support high quality.
  • Grown on volcanic soil at high elevations.
  1. Guatemala
  • Produces complex coffees with chocolate, spice, and berry notes.
  • Medium to full body and pronounced acidity.
  • Volcanic soils and diverse microclimates offer great variety.
  • Antigua and Huehuetenango are standout regions.
  1. Costa Rica
  • Known for clean, sweet, and bright coffees.
  • Common flavor notes: citrus, stone fruit, brown sugar.
  • Frequently uses honey and washed processes.
  • Strong environmental and quality controls.
  1. Panama
  • Globally recognized for the Geisha variety.
  • Offers floral, jasmine, bergamot, and delicate fruit notes.
  • High-altitude farms like Boquete and Volcán yield prized lots.
  • Among the most expensive coffees in the world.
  1. Indonesia
  • Notable regions: Sumatra, Java, Sulawesi.
  • Produces earthy, bold coffees with heavy body and low acidity.
  • Often processed using traditional wet-hulling.
  • Complex, deep profiles loved in dark roasts.
  1. Honduras
  • Emerging as a high-quality producer.
  • Known for sweet, balanced, sometimes tropical fruit-forward cups.
  • Great for both filter and espresso use.
  • Strong investment in cooperatives and traceability.

Related Stories:

Barista Terminology | Episode 13: Espresso Machine Components Explained

Barista Terminology | Episode 12: Brewing Equipment Maintenance & Hygiene

Barista Terminology | Episode 11: Milk-Based Coffee Drinks

Barista Terminology | Episode 10: Advanced Concepts

Barista Terminology | Episode 9: Sensory Evaluation

Barista Terminology | Episode 8: Customer Service Language in the Café

Barista Terminology | Episode 7: Water & Temperature Control

Barista Terminology | Episode 6: Grind & Extraction Variables

Barista Terminology | Episode 5: Milk Texturing & Latte Art

Barista Terminology | Episode 4: Brew Methods Explained

Barista Terminology | Episode 1: The Coffee Bean – From Seed to Roast

Barista Terminology | Episode 2: Barista Tools & Equipment

Barista Terminology | Episode 3: Espresso Basics


British Study: Hot Drinks Contain the Highest Levels of Microplastics

London – August 28, 2025 (Qahwa World) – A peer-reviewed study from the University of Birmingham has found that everyday hot beverages—especially tea and coffee—contain the highest concentrations of microplastics among popular drinks tested, raising fresh questions about packaging, preparation practices, and real-world exposure. The paper, published in Science of the Total Environment, analysed 155 widely available drinks sold in UK supermarkets and coffee shops and is the first to assess human exposure via total beverage intake rather than water alone.

Researchers reported microplastics in every sample. Hot tea recorded the highest average concentration at 60 ± 21 particles per litre, followed by hot coffee at 43 ± 14 particles per litre. By comparison, iced tea averaged 31 ± 7, iced coffee 37 ± 6, fruit juices 30 ± 11, energy drinks 25 ± 11, and soft drinks 17 ± 4 particles per litre. Detected particle sizes ranged from 10 to 157 μm. The study also found a statistically significant difference between hot and cold beverages, indicating that temperature enhances the leaching of microplastics from packaging into drinks.

Packaging emerged as a critical factor. The authors highlight that higher temperatures increase microplastic release from packaging and that plastic packaging contributes to the contamination observed in beverages. In hot coffee served in disposable paper cups with polypropylene (PP) caps, PP microplastics predominated—strong evidence that cup materials are a primary source. Similar packaging-linked patterns appeared for iced products sold in PET bottles.

Beyond quantifying contamination, the study models realistic exposure by combining laboratory results with a survey of UK adults’ daily drink consumption. The estimated daily intake via total beverage consumption averages 1.6–1.7 microplastic particles per kilogram of body weight per day for men and women, respectively—a materially higher figure than previous estimates based on water alone. The authors conclude that focusing exposure assessments solely on tap or bottled water underestimates total intake because other beverages contribute substantially.

Contextualising these results, the research team notes that prior work by the same group measured broadly similar microplastic levels in UK tap and bottled water, underscoring that the higher counts now seen in hot tea and coffee represent an additional exposure pathway. The paper also synthesises evidence from multiple countries showing packaging and handling as recurring factors—ranging from release from tea bags to particles in soft drinks—while emphasising the novelty of testing a broad range of hot and cold beverages from a single market and pairing those measurements with consumption data.

Mechanistically, the findings are consistent: heat accelerates the transfer of particles from polymer-lined cups and lids, while materials such as PP, PET, polystyrene, polyethylene, and others appear across drink categories, mirroring common packaging choices. The authors cite previous studies that similarly link high temperature to increased microplastic release and demonstrate that both container material and product format (for example, single-use cups or PET bottles) shape the polymer “fingerprint” detected in the drink.

Public-health implications, while still being delineated by the broader scientific community, are clear enough to prompt the study’s call for more comprehensive risk assessments and policy responses. The authors characterise this work as a critical step toward understanding real-life exposure and urge regulators and industry to consider the combined effects of packaging materials, preparation conditions, and consumption habits when setting guidelines to limit human exposure.

The Birmingham team underscores limitations that likely make their exposure estimates conservative. Analytical methods in this study quantified particles ≥10 μm; smaller microplastics and nanoplastics—potentially more bioavailable—were outside detection limits. Nevertheless, with microplastics present across all categories tested and highest in hot beverages integral to daily routines, the evidence base now more firmly indicates that the act of making and serving hot drinks in common packaging can materially influence what ends up in the cup.

For consumers and producers alike, the study’s takeaway is practical: materials and temperature matter. For policymakers, the message is systemic: exposure assessments built solely on drinking water do not reflect the way people actually consume liquids. As the authors conclude, more accurate, comprehensive, and realistic exposure studies are needed to support effective environmental and public-health interventions.

Source: University of Birmingham, “Synthetic microplastics in hot and cold beverages from the UK market: Comprehensive assessment of human exposure via total beverage intake,” Science of the Total Environment 996 (2025) 180188.