Global Coffee Exports Surge Amid Asian Growth and Latin American Decline

LONDON – Qahwa World

The latest report from the International Coffee Organization reveals profound shifts in the global trade landscape, as total coffee exports across all forms surged to 12.62 million bags in January, marking a 13.7% increase compared to the same month last year. This growth was primarily driven by an exceptional performance in the Robusta sector, which successfully offset a significant contraction in shipments from major producers in South America, reflecting a fundamental change in the global supply structure.

Data highlights a dominant performance by the Asia & Oceania region, which achieved a 54.4% growth in exports. Vietnam led this surge with 3.99 million bags exported—a 73.3% annual increase—as the country accelerated shipments to clear inventories ahead of national holidays. Africa also maintained a strong presence with 14.2% growth, notably led by Ethiopia, which saw a 51.5% jump in shipments, confirming the recovery of supply chains and the continent’s ability to capture new market shares.

You may Read: ICO February 2026 Report: Has the Inflationary Wave Receded?

In contrast, South America faced a different reality, with exports declining by 21.3%. This downturn was directly impacted by a drop in shipments from Brazil and Colombia, ranging between 19% and 22%, following unfavorable localized weather conditions. This trend extended to Mexico and Central America, which recorded a 4.2% decrease, with Honduras suffering a sharp 28.7% drop in shipments due to logistical challenges and seasonal labor shortages still hindering the pace of exports in that region.

By category, Robusta exports grew by a staggering 49.1% to reach 5.25 million bags, accounting for a larger share of the global green bean trade at 48.4%. Furthermore, the data reveals a strategic shift toward value addition in origin countries, as exports of roasted coffee jumped by 25.2%. This indicates a growing desire among producers to move beyond raw material exports toward local manufacturing to maximize economic returns amidst the rapid changes in the global coffee sector.

ICO February 2026 Report: Has the Inflationary Wave Receded?

LONDON – Qahwa World

The latest monthly report issued by the International Coffee Organization for February 2026 has revealed a dramatic shift that could redefine the global coffee market dynamics for years to come. After a prolonged period of scarcity and record-high prices that strained both suppliers and consumers, the report announced a sharp decline in price indicators. This shift is driven by a “tsunami” of anticipated supplies from Brazil and Vietnam, officially placing the market on the verge of a historic surplus that ends a three-year cycle of consecutive deficits.

  • Price Earthquake

In February, the Organization’s Composite Indicator Price (I-CIP) averaged 267.57 US cents/lb, representing a sharp 9.9% decrease compared to January. This decline is not merely a transient fluctuation but reflects massive selling pressure in global exchanges; the index opened the month at a peak of 289.47 cents and slid to 248.86 cents by month-end, the lowest level recorded since August 2025.

You may read: Global Coffee Market Roadmap—January 2026

None of the major categories were immune to this downward trend, with the Organization’s statistical analysis showing the following results:

  • Colombian Milds: Declined by 11.0% to settle at 330.89 cents.
  • Other Milds: Retracted by 11.7% to reach 321.35 cents.
  • Brazilian Naturals: Shrank by 10.2% to reach 308.62 cents.

Robustas: Proved most resilient, declining by only 6.6%. Experts attribute this to global roasters increasing the proportion of Robusta in their commercial blends as a strategic solution to reduce overall costs, creating sustainable demand that stabilized its price levels.

  • Brazilian and Vietnamese Winds

Organization analysts believe the fundamental reason behind this “price correction” lies in the optimistic forecasts from Brazil’s National Supply Company (CONAB), which raised expectations for the 2026/27 crop to 66.2 million bags, a massive 17.1% annual increase.

These forecasts were supported by a tangible improvement in weather conditions and regular, heavy rainfall in key growing regions such as Minas Gerais and Espírito Santo, as well as improved outlooks in the Central Highlands of Vietnam. These factors prompted major international financial institutions to predict a global surplus of up to 8.64 million bags, leading large investment funds to liquidate long positions and pivot toward selling. This explains the 20.7% shrinkage in the arbitrage between the London and New York futures markets.

  • Global Trade Map

Regarding exports, January 2026 saw the shipment of 10.85 million bags of green beans, a 12.7% increase over January 2025. However, behind this headline figure lie geographical disparities reflecting specific regional logistical and production challenges:

Asia & Oceania: The region achieved a staggering 51.8% growth, with Vietnam alone exporting 3.99 million bags in January, capitalizing on accelerated shipping ahead of the Lunar New Year (Tet) holiday.

Africa: Continued its recovery with 14.2% growth. Ethiopia stood out as a strategic player with a 51.5% increase in shipments, while Uganda grew by 11.2%, reflecting a significant improvement in the continent’s internal supply chains.

South America: Recorded a surprising 21.3% decline. The biggest shock was in Colombia, where production plummeted by 34.1% due to unfavorable localized weather fluctuations, negatively impacting the flow of premium Colombian Milds to global markets.

Mexico & Central America: Registered a slight 4.2% decrease, with Honduras suffering a sharp 28.7% drop in exports due to seasonal labor shortages and logistical hurdles.

Read Also: ICO Releases Global Coffee Market Report – December 2025

  • Stocks and Processed Coffee

For the first time in months, the International Coffee Organization report indicates a slight improvement in certified stocks. New York (ICE) stocks rose by 11.4% to 0.52 million bags, while London stocks increased by 3.1% to 0.76 million bags. This rise provides a relative “safety cushion” against sudden climatic or political shocks.

A notable phenomenon in the report was the export of “Roasted Coffee,” which jumped by 25.2%. This indicates a strategic shift in origin countries toward local processing to add value to their products rather than relying solely on raw bean exports. Meanwhile, soluble coffee exports grew at a steady pace of 1.9%.

  • The Retail Paradox

The report highlighted a crucial point affecting the real economy: despite the collapse of raw coffee prices in global exchanges, retail prices in the United States jumped by 18.3% year-on-year in January 2026. This persistent inflation, totaling 47% cumulatively over five years, is mainly due to rising logistics, energy, and labor costs in consuming countries. Additionally, accumulating consumer debt is beginning to weigh on purchasing power, which may threaten the expected 1.7% growth in global consumption.

  • Future Outlook

We are entering a phase of total “reset” in coffee market balances. The market is currently moving to narrow the global deficit to just 0.4 million bags this season, paving the way for the anticipated historic surplus next year. For investors, roasters, and consumers, the February 2026 report serves as the “final whistle” for the era of frantic speculation and chronic shortages, signaling the start of a price stability phase led by Brazilian production abundance and Vietnamese logistical efficiency.

Coffee Prices Drop on Brazil Weather and Rising Stocks

Dubai – Qahwa World

Coffee markets fell on Wednesday amid favorable weather forecasts in Brazil and rising inventories monitored by the Intercontinental Exchange (ICE).

May arabica futures (KCK26) were down 8.70 points (-2.94%), while May ICE robusta (RMK26) declined 137 points (-3.71%). Showers expected in key Brazilian coffee-growing regions supported the recent price drop.

ICE data shows that arabica inventories, which fell to a 1.75-year low of 396,513 bags in November, recovered to a five-month high of 564,626 bags on Tuesday. Robusta inventories also rose to a 3.5-month peak before falling slightly to 4,563 lots as of Wednesday.

You may like:Brazil’s Specialty Coffee Sector Gains Global Momentum

Coffee prices had partially retraced last week’s rally triggered by the Iran conflict and the closure of the Strait of Hormuz, which increased global shipping rates, fuel, and insurance costs.

Brazil’s exports also influenced the market. According to Cecafe, February green coffee shipments fell by 27% year-on-year, while the Trade Ministry reported a 17.4% decline to 142,000 metric tons. Conversely, recent rains in Minas Gerais—the country’s largest arabica-producing state—amounted to 14.9 mm last week, about 35% of the historical average, offering some support to crop expectations.

Earlier in February, coffee prices hit multi-month lows amid forecasts of a record Brazilian crop. Conab projected Brazil’s 2026 coffee output at 66.2 million bags, with arabica rising 23.2% to 44.1 million bags and robusta up 6.3% to 22.1 million bags. Global production for 2026/27 is expected to reach 180 million bags, according to Rabobank.

You may like:Coffee Markets Rise Amid Middle East Shipping Disruptions

Vietnam’s coffee exports further pressured robusta prices. The National Statistics Office reported a 14% year-on-year rise to 366,000 MT for January–February 2026, while 2025 exports jumped 17.5% to 1.58 million MT. Production in 2025/26 is forecast to reach 1.76 million MT, a four-year high.

Despite these factors, the International Coffee Organization (ICO) noted a slight 0.3% year-on-year decline in global coffee exports for the current marketing year. The USDA’s Foreign Agriculture Service projects 2025/26 global production at 178.848 million bags, with arabica down 4.7% to 95.515 million bags and robusta up 10.9% to 83.333 million bags. Brazil’s production is expected to fall 3.1% to 63 million bags, while Vietnam rises 6.2% to 30.8 million bags. Ending stocks are forecast to decline 5.4% to 20.148 million bags.

Analysts say the combination of Brazilian rainfall, rising ICE inventories, and record production in Vietnam is likely to maintain downward pressure on coffee prices in the near term.

Kaffa Oslo Wins Nordics Best Roaster 2026

Dubai – Qahwa World

Kaffa Oslo has been crowned the Nordics Best Roaster 2026, securing the top position in one of the most respected roasting competitions in the Nordic coffee industry. The announcement was made during the Nordic Coffee Fest, where leading roasteries from across the region competed in a peer-assessed event focused on sourcing and roasting excellence.

The competition evaluates roasters through two main categories: Mandatory Coffee, where all competitors roast the same green coffee provided by the organizers, and Sourced Coffee, in which each roastery presents a coffee it has sourced and roasted according to specific competition parameters. The roastery with the highest combined score across both categories is declared the champion.

You may read: Nordic Coffee Fest 2026: The Largest Coffee Event in Gothenburg

  • Winning coffee from Peru

Kaffa Oslo’s sourced coffee entry came from Peru’s Cajamarca region, produced by Familia Alarcon. The coffee was a Geisha variety, processed using a fully washed method and sourced through Collaborative Coffee Source AS. The reported green coffee price for the lot was 20 US dollars per kilogram.

  • Strong Nordic competition

The 2026 finals brought together some of the most recognized roasters in the Nordic region. Finalists included:

  1. Good Life Coffee Roasters
  2. Gringo Nordic Coffee Roasters
  3. Coffee Collective
  4. Solberg & Hansen
  5. Sensei
  6. Original Coffee
  7. Norange
  8. Muttley & Jack’s
  9. Te & Kaffi

The competition also presented awards for second place, third place, and the Public Choice Award, reflecting the high level of participation and public interest in the event.

  • Mandatory coffee from Colombia

For the Mandatory Coffee category, competitors roasted the same green coffee supplied through a collaboration with Caravela Coffee.

The coffee originated from Colombia, produced by the Las Orquídeas producer group, including farmers Gilma Cupaque and Nubia Yaneth Paz. It featured Colombia F6 and F8 varieties and was processed using the washed method.

The harvest took place between April and June 2025, and the beans were dried using sun and air drying on parabolic patios and raised beds.

  • Scientific study unveiled during the competition

Alongside the announcement of the final results, organizers revealed a research project conducted by CoffeeMind in collaboration with Nordic Coffee Fest.

The study, titled “Linking Sensory Descriptive Analysis and Judge Preferences in the Nordics Best Roaster Competition: A Consumer Science Approach,” analyzed how sensory characteristics influence judge preferences in competition coffees.

Researchers compared sensory descriptive analysis of selected coffees with judges’ scoring data from the Sourced Coffee category. Using statistical methods commonly applied in consumer science, the study examined how specific flavor attributes relate to preference among expert judges.

  • Understanding the drivers of preference

The analysis evaluated attributes such as acidity, sweetness, fruit notes, bitterness, and fermentation characteristics, linking them with the competition’s judging scores.

According to the researchers, combining sensory science with competition results provides a clearer understanding of why certain coffees perform better during professional evaluations.

Organizers say the initiative represents a new approach to studying coffee quality within roasting competitions, offering insights that may help roasters refine sourcing strategies and roasting profiles in future events.

FAO Welcomes UN Resolution Establishing International Coffee Day on October 1

Dubai – Qahwa World

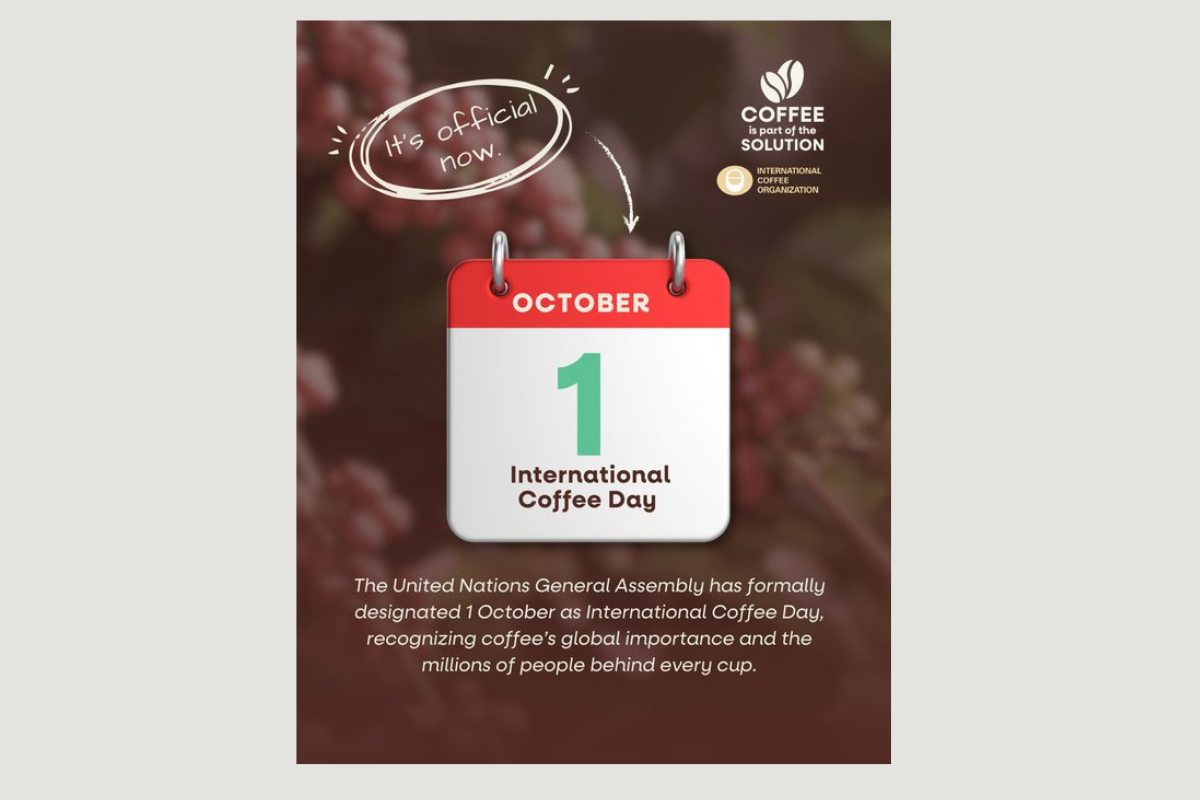
The Food and Agriculture Organization of the United Nations has welcomed a new resolution adopted by the United Nations General Assembly proclaiming October 1 as International Coffee Day, marking a significant step toward recognizing coffee’s global economic, social, and cultural importance.

The resolution, approved on 10 March 2026 in New York, highlights the historical and cultural role of coffee and its lasting influence on societies worldwide. It acknowledges that coffee has evolved from its origins into a globally traded agricultural commodity that sustains communities while also serving as a symbol of social interaction, cultural identity, and everyday tradition across generations.

You may Read: UN Officially Designates 1 October as International Coffee Day 

  • Coffee and global development

The United Nations resolution underscores the contribution of the coffee sector to several key global development priorities. Among them are ending hunger, reducing extreme poverty, empowering women, and promoting decent work and economic growth, all of which are central to the United Nations Sustainable Development Goals.

According to Qu Dongyu, coffee represents far more than a popular beverage.

“Coffee is more than a drink; it is a globally traded commodity—from beans to coffee service—that sustains the livelihoods of millions of farming households and connects rural communities to markets around the world,” he said. “Recognizing the value of the coffee sector will raise awareness of its socio-economic importance and strengthen its contribution to eradicating poverty.”

You may read: International Coffee Day: How It Started and Why the World Celebrates 

  • A sector supporting millions

Coffee remains one of the most widely consumed beverages worldwide. Global per-capita consumption has grown by about 1.2 percent annually over the past decade, reflecting steady demand across international markets.

The sector supports the livelihoods of around 25 million coffee farmers, while employment extends across the entire value chain—from cultivation and processing to trading, roasting, and retail. Altogether, the global coffee industry generates more than 200 billion dollars in annual revenue.

Coffee also ranks among the world’s most traded agricultural commodities. In 2024, global production surpassed 11 million tonnes, with approximately 8 million tonnes traded internationally. That same year, the estimated value of global coffee production reached nearly 25 billion dollars, while international trade in coffee beans totaled about 34 billion dollars.

Read also: International Coffee Day: A Beverage’s Journey from Yemen to the World 

  • Vital exports for developing economies

For many low-income countries, coffee exports remain a critical source of foreign currency earnings.

In 2024, coffee accounted for 27.9 percent of total merchandise exports in Ethiopia, 20.1 percent in Uganda, and 19.5 percent in Burundi. In both Ethiopia and Uganda, revenues from coffee exports exceeded national food import bills, while in Burundi they represented nearly one-fifth of the country’s food import costs.

During the same year, Brazil and Viet Nam were the world’s leading coffee exporters, while the European Union and the United States remained the largest import markets.

  • FAO’s role in strengthening the coffee sector

FAO works with coffee-producing countries through a range of initiatives designed to strengthen sustainability, productivity, and farmer livelihoods.

One of the organization’s priorities is helping producers adapt to the growing impacts of climate change. Through programs such as Farmer Field Schools, FAO supports pest management strategies and the conservation of traditional coffee systems, including projects in Panama. Additional initiatives promote agroforestry systems and climate-resilient coffee varieties in East Africa, while cooperative development programs are helping strengthen rural economies in countries such as Cuba.

You may like:Coffee Industry on International Coffee Day: Production, Consumption, and Future Challenges 

The organization is also assisting producers in responding to evolving market requirements. As international buyers increasingly demand traceability and compliance with sustainability standards, FAO is working with governments and producers in countries including Honduras, Guatemala, and Uganda to establish stronger traceability systems and align national policies with global frameworks. These efforts aim to mobilize investment benefiting more than 200,000 smallholder farmers.

Through its Investment Centre and initiatives such as the Hand-in-Hand Initiative, FAO is also supporting financing mechanisms that improve efficiency and increase farmer incomes. Projects in Brazil, Costa Rica, and Honduras, implemented with partners including the World Bank, are helping strengthen the long-term resilience of coffee farming systems. In El Salvador, FAO has supported the development of a comprehensive national coffee strategy.

  • A global platform for the coffee community

With the establishment of International Coffee Day under the UN system, FAO has been invited to coordinate the annual observance in collaboration with relevant organizations, particularly the International Coffee Organization.

The new international day is expected to serve as a global platform for dialogue, cooperation, and knowledge-sharing across the coffee value chain. By highlighting both the opportunities and the challenges facing producers, the initiative aims to strengthen international commitment to a sustainable, inclusive, and resilient coffee sector that contributes to rural development and global food security.


UN Officially Designates 1 October as International Coffee Day

Dubai – Qahwa World

The International Coffee Organization has announced what it described as “a historic moment for the global coffee community” after the United Nations General Assembly formally designated 1 October as International Coffee Day.

According to the announcement, the decision recognizes coffee’s profound importance to global economies, cultures, and livelihoods, highlighting the role the beverage plays across producing and consuming nations alike.

The milestone follows the adoption of Resolution A/80/L.44 by the United Nations General Assembly on 10 March 2026. The resolution, introduced by Brazil, received 150 votes in favor, with one vote against from the United States and one abstention from Canada.

United Nations Officially Declares 1 October International Coffee Day

Under the resolution, 1 October will now be officially recognized every year as International Coffee Day, and all countries, United Nations bodies, and relevant stakeholders are invited to organize activities that highlight the economic, social, and environmental significance of coffee.

The resolution also invites the Food and Agriculture Organization of the United Nations to lead the annual observance in cooperation with the International Coffee Organization.

  • Elevating an existing global celebration

International Coffee Day has already been observed globally on 1 October since 2015, when the initiative was first launched by the International Coffee Organization during Expo 2015 Milan.

The new United Nations designation elevates the observance to an official international day within the UN system, giving the coffee sector broader global recognition and strengthening the visibility of the millions of people who depend on coffee for their livelihoods.

United Nations Officially Declares 1 October International Coffee Day

In its statement, the International Coffee Organization noted that the decision reflects the collective efforts of its member countries, institutional partners, and international organizations, including the Food and Agriculture Organization, to raise awareness of the coffee sector’s importance.

  • Supporting farmers and sustainability

Coffee remains one of the world’s most widely traded agricultural commodities and supports millions of farmers, workers, traders, and communities across Africa, Asia, and Latin America.

The International Coffee Organization and the Food and Agriculture Organization see the UN recognition as an opportunity to strengthen global attention to the sector’s key challenges and opportunities, including sustainability, farmer livelihoods, and climate-related risks affecting coffee production.

Qu Dongyu welcomed the decision, stating that the new international day will help raise awareness of coffee’s socio-economic importance and reinforce its role in supporting efforts to reduce poverty worldwide.

United Nations Officially Declares 1 October International Coffee Day

For the global coffee community—from smallholder farmers to exporters, roasters, and consumers—the recognition marks a significant step toward greater international acknowledgment of the industry’s cultural and economic impact.

With the adoption of the UN resolution, International Coffee Day on 1 October is expected to gain even broader global participation, as governments, organizations, and coffee professionals organize events and initiatives celebrating the beverage and the people behind every cup.

Brazil’s Specialty Coffee Sector Gains Global Momentum

Dubai – Qahwa World

The United States Department of Agriculture (USDA) published a detailed report titled “Brewing Opportunity – Brazil’s Specialty Coffee Sector Shows Strong Potential,” examining the rapid development of Brazil’s specialty coffee industry and the opportunities and challenges shaping its future.

Brazil remains the largest coffee producer and exporter in the world, while also ranking as the second-largest coffee-consuming country. Historically, the nation exported its highest-quality beans while domestic consumption focused largely on lower-grade coffee. In recent years, however, this pattern has begun to shift. Brazilian consumers are increasingly developing a taste for specialty coffee, driving growth in both production and local demand.

According to the report, the expansion of the specialty segment is supported by several structural advantages. Brazil benefits from favorable climatic conditions that allow the cultivation of diverse coffee varieties across multiple regions. In addition, the country has developed a strong network of research institutions, cooperatives, and producer organizations that focus on improving quality, innovation, and technical expertise within the coffee sector.

At the same time, the domestic market for coffee continues to expand, with consumers showing greater interest in differentiated products and higher-quality beans.

You may read: Russia’s Imports of Brazilian Coffee Fall to Six-Month Low

Despite this progress, the report notes that Brazil’s specialty coffee sector still faces several structural challenges. Many producers struggle with limited access to rural credit, making it difficult to finance investments in equipment and infrastructure. Post-harvest processing facilities—such as washing stations, pulpers, sorting machines, and drying systems—also remain insufficient in some areas, limiting the ability of farmers to produce and market high-quality coffee.

Producers have also reported uneven access to technical assistance and a limited number of certified warehouses and exporters, which can reduce profitability and hinder broader participation in the specialty coffee market, particularly among small-scale farmers.

Although specialty coffee generally costs about 50 percent more than conventional coffee, the segment offers advantages beyond price. Buyers often establish longer-term relationships with producers, which can provide farmers with greater stability and security for future harvests.

  • Major Coffee-Producing Regions

Specialty coffee production in Brazil is concentrated mainly in high-altitude regions, where elevation and moderate temperatures contribute to denser beans and more complex flavor profiles.

You may read: Brazil Crop Expectations Pressure Global Coffee Prices

The state of Minas Gerais stands as Brazil’s leading producer of arabica and specialty coffees. Regions such as Sul de Minas, Cerrado Mineiro, Matas de Minas, and Mantiqueira de Minas form a well-organized production chain that includes farmers, cooperatives, exporters, warehouses, and research institutions. Minas Gerais alone produces around 24 million bags of coffee annually, representing nearly half of Brazil’s total coffee output.

Each sub-region offers distinctive characteristics. Cerrado Mineiro became the first coffee region in Brazil to receive Designation of Origin status, while Sul de Minas is known for its concentration of small farms and its large cooperative structure. Mantiqueira de Minas has gained international recognition for its high-altitude coffees, where significant temperature variation between day and night allows cherries to ripen slowly, resulting in sweeter and more aromatic beans.

In Espírito Santo, Brazil’s second-largest coffee-producing state, production is dominated by robusta—locally known as conilon—though high-altitude areas also produce quality arabica coffee. Regions such as Caparaó and Montanhas do Espírito Santo are known for small family farms and coffees with aromatic complexity and balanced acidity.

The state of São Paulo also contributes to the specialty segment through regions such as Alta Mogiana and Média Mogiana, where coffees typically display balanced acidity, strong aroma, and a creamy body.

You may read:Coffee Prices Rise as Brazilian Real Strength Sparks Short Covering

Other regions across Brazil contribute unique characteristics as well. Rondônia, located in the Amazon region, specializes in conilon production, while Paraná, historically a major coffee producer, continues to maintain output through small farms supported by cooperatives and research institutions. Meanwhile, Bahia, one of the country’s newer coffee regions, has gained attention for its use of advanced technology and mechanized farming systems, which support high productivity levels.

  • Quality Standards and Classification

Brazil follows internationally recognized quality standards for specialty coffee. The evaluation system used by the Specialty Coffee Association scores arabica coffees on a 100-point scale, with coffees scoring 80 points or higher classified as specialty grade.

Coffees are evaluated according to sensory characteristics such as aroma, flavor, acidity, body, sweetness, balance, uniformity, and aftertaste, while also being assessed for physical defects.

Brazil also uses national classification systems aligned with these international standards. The country’s official classification process evaluates cup quality using descriptors such as strictly soft, soft, and hard, among others.

In May 2025, the Brazil Specialty Coffee Association adopted a new evaluation protocol known as Coffee Value Assessment, designed to create a more standardized approach to assessing quality and to improve communication between producers and international buyers.

You may read:Brazil Rain and Vietnam Surplus Sink Coffee Futures

Brazilian producers may also use additional certification programs—such as organic or fair-trade certifications—to meet international market requirements, although these certifications do not automatically classify a coffee as specialty.

The quality of Brazilian robusta and conilon coffee has also improved in recent years, contributing to stronger demand and higher prices. Brazil is currently the second-largest producer of robusta coffee globally, behind Vietnam.

  • Challenges Affecting Growth

The report highlights genetics as another key factor in specialty coffee production. However, inconsistencies between international and national databases for coffee cultivars sometimes create challenges. Some varieties recognized internationally for exceptional quality are not officially registered for cultivation in Brazil, while many important Brazilian cultivars are absent from international quality catalogues.

These discrepancies can complicate certification and recognition processes for producers and may increase production costs or reduce profitability.

Specialty coffee production also requires significant investments in cultivation techniques and post-harvest infrastructure. Because these investments can be costly, the specialty coffee sector in Brazil remains concentrated among a relatively limited number of producers.

  • Growing Interest Among Brazilian Consumers

Although Brazil has long been a global coffee powerhouse, domestic appreciation for specialty coffee is relatively recent. Since the early 2000s, coffee culture has evolved significantly as consumers began exploring higher-quality beans, alternative brewing methods, and greater transparency regarding coffee origins.

You may read:India’s Quiet Coffee Superpower

Recent consumer surveys show that some Brazilians have reduced overall coffee consumption in response to rising prices. Nevertheless, demand for specialty coffee continues to grow. The report indicates that consumption of specialty coffee in Brazil has been increasing by about 15 percent per year, significantly faster than the growth of traditional coffee consumption.

Specialty coffee consumption in the country is estimated at around 70,000 tons annually, representing approximately five to ten percent of total coffee consumption.

Consumers interested in specialty coffee tend to seek differentiated beans, visit cafés that emphasize brewing quality, and show greater interest in sustainability practices and traceability.

  • Trade Trends and Export Markets

Brazilian export data does not track specialty coffee as a separate category. Instead, exporters often group it under “differentiated coffees,” which include beans certified for quality, sustainability, or other distinctive characteristics.

According to export data, Brazil shipped 8.1 million bags of differentiated coffees in 2025, representing about 20 percent of the country’s total coffee exports. Although export volumes declined compared with the previous year, revenues increased significantly to approximately 3.5 billion dollars, partly due to favorable exchange rates.

The United States remained the largest destination for Brazilian differentiated coffees, importing about 1.3 million bags, followed by Germany, Belgium, the Netherlands, and Italy. European markets often function as distribution hubs that supply specialty coffee to other regions.

  • Global Promotion and Future Outlook

Brazil is actively promoting its specialty coffee sector internationally through initiatives designed to strengthen its presence in global markets. One such program focuses on marketing Brazilian specialty coffees through trade fairs, branding campaigns, and partnerships with international buyers.

Priority markets include the United States, Japan, China, South Korea, the United Arab Emirates, France, and Australia, while processed coffee products such as roasted and ground coffee are being promoted in markets including Canada, Chile, China, and the United States.

The initiative is scheduled to run until 2027 and aims to expand Brazil’s leadership in the global specialty coffee sector.

The report concludes that rising international demand for traceable, sustainable, and high-quality coffee—combined with ongoing improvements in production and promotion—positions Brazil’s specialty coffee industry for continued growth in the years ahead.
Coffee Farmers in Central America Struggle to Survive Falling Prices

Dubai – Qahwa World

The Guardian published a lengthy report titled “‘Everyone feels like they are being scammed’: can Central America’s small coffee growers survive as global prices fall?”, which discussed the growing pressures facing coffee farmers in parts of Central America, particularly in El Salvador and Honduras. The report explores how climate instability, rising production costs, labour shortages and volatile global markets are reshaping coffee farming across the region.

According to the report, many small producers who have depended on coffee cultivation for generations are now confronting increasingly unpredictable conditions. Weather patterns that once followed a familiar seasonal rhythm have become less reliable, making it difficult for farmers to plan their harvest cycles and manage their farms effectively.

The report begins on a hillside in western El Salvador, where coffee farmer Oscar Leiva observes rainfall arriving in December, a month that traditionally marked the beginning of the dry season. During the latest harvest cycle, flowering occurred early and then stalled, followed by a period of intense heat. As a result, the remaining crop is uneven in quality and more expensive to produce than previous harvests.

You may like: Global Study Maps the “Carbon Footprint” of Latin American Coffee

For Leiva’s family, coffee is not simply a crop but a long-standing way of life. His mother, Esperanza Marinero, remembers when the rainy season arrived on time and harvests could be planned months ahead. Today, that certainty has disappeared. Farmers must make decisions about pruning, fertilising and hiring workers without reliable seasonal patterns, increasing the financial risks they face.

Coffee has historically played a major role in El Salvador’s economy. In the mid-1970s the country ranked among the world’s leading coffee producers, with harvests exceeding five million quintales, a unit equal to about 46 kilograms. Today, national production struggles to reach one million quintales.

The report notes that this decline reflects more than market cycles. Decades of land restructuring, climate shocks and rural migration have weakened the coffee sector and altered the agricultural landscape. Increasing climate volatility has disrupted flowering cycles, reduced yields and affected the quality of coffee, particularly for small farmers who lack financial reserves to absorb repeated losses.

Read also: Shock in the Coffee Market: Colombia’s Production Drops 36%

Cecibel Romero, a researcher focusing on coffee production, explained that the sector is experiencing overlapping challenges that extend beyond climate change alone. Rising temperatures, irregular rainfall and plant diseases such as coffee rust have exposed long-standing vulnerabilities in traditional production systems.

Romero noted that past production models often focused on maximising yields and implementing short-term solutions rather than building long-term resilience. After severe rust outbreaks in the early 2010s, many producers replanted their farms with varieties believed to be resistant. However, some of these varieties produced lower-quality beans or did not maintain their resistance over time.

As coffee’s economic importance declined in El Salvador, public support systems for the sector were also reduced. Agricultural services weakened, renovation programmes became fragmented and access to affordable credit narrowed. As a result, many producers have been left to cope with climate risks, disease outbreaks and market volatility largely on their own.

Read also:Coffee Markets Rise Amid Middle East Shipping Disruptions

Similar pressures are being felt in Honduras, the largest coffee producer in Central America. Although overall production remains higher than in El Salvador, farmers there are also dealing with rising costs and climate-related challenges.

Juan Luis Hernández, a forest engineer who has worked on environmental projects connected to the Honduran Coffee Institute, said adapting to changing conditions requires investment, time and labour. Measures such as managing shade trees, restoring soil health, protecting water sources and monitoring plant diseases all require resources that are not equally available to all farmers.

In the Honduran region of Copán, farmer Gerardo Vásquez manages an eight-hectare family farm while also advising other growers. Trained through the Honduran Coffee Institute, he works on soil analysis, selecting coffee varieties and developing agroforestry systems.

Even with this technical background, Vásquez says the economic reality of coffee farming remains difficult. Establishing one manzana of coffee — roughly 0.7 hectares — now costs about 200,000 lempiras over a period of three years.

Read also: Bridging the Gap: An Exclusive Dialogue with Vanusia Nogueira on the Global Coffee Crisis and the Path to 2026

Production costs have risen significantly in recent years. Fertiliser prices increased sharply after the pandemic, while labour shortages have pushed wages for harvest workers higher. When harvesting, processing and transport are included, farmers may spend more than 3,000 lempiras to produce a single quintal of parchment coffee.

Weather conditions can further complicate the process. Continuous rainfall makes drying coffee difficult, forcing some farmers to sell freshly picked cherries directly from the field at lower prices. Others depend on intermediaries who provide advance payments, which can limit farmers’ ability to negotiate prices later.

Climate change is also affecting where coffee can be grown successfully. Farms located below 1,000 metres above sea level are becoming more vulnerable to heat stress, pests and diseases. As a result, coffee cultivation has gradually moved to higher elevations over time.

However, relocating production to higher ground is not feasible for many smallholders, who may not have access to suitable land or the financial means to make such changes.

At Café San Rafael in Honduras, co-owner Carlos Guerra explained that the flowering cycle of coffee plants has become increasingly irregular. What once occurred within a predictable timeframe now happens in stages, extending the harvest period and raising labour costs.

Labour itself has become one of the most pressing challenges for producers. Coffee harvesting requires careful selection of ripe cherries, a process that cannot easily be mechanised. Younger workers are increasingly leaving rural areas, making it harder for farms to recruit enough labour during harvest season.

Farmers are experimenting with various adaptation strategies, including planting additional shade trees and improving soil management practices. While these measures can help protect coffee plants from heat stress, they may also reduce yields, creating a difficult balance between environmental resilience and economic viability.

Some farms attempt to offset these challenges by focusing on higher-value markets. At Café San Rafael, careful management of fermentation and drying processes helps maintain coffee quality even when harvest conditions are uneven. Operating a roastery also allows the business to manage fluctuations in supply.

However, many small farmers do not have access to such opportunities. Entering specialty coffee markets often requires certification, processing infrastructure and export connections that remain beyond the reach of numerous producers.

Emeric Seguin, director of sourcing and sustainability at a specialty coffee company working with producers in Central America, told the newspaper that mistrust is widespread within the supply chain. Farmers often feel undervalued, while buyers worry about inconsistent supply, leaving cooperatives caught between both sides.

Several initiatives are attempting to promote more resilient farming practices. In El Salvador, a coffee production school known as Renacer encourages ecological approaches that focus on soil health, shade restoration and long-term stability rather than maximising short-term yields.

Agronomist Sigfredo Corado explained that the goal is to reduce extreme fluctuations in harvests. While farms may not achieve exceptionally high yields in strong years, they are also less likely to experience severe drops in production.

Despite these efforts, the report notes that global market conditions could add further pressure. Rabobank has predicted that increasing coffee surpluses in the coming seasons could push international prices lower, potentially making coffee production less viable for smallholders.

As profitability declines, some land previously used for shaded coffee is being converted to other crops or sold for development, gradually altering landscapes that have long been associated with coffee cultivation.

For farmers such as Oscar Leiva, planning for the next season remains unavoidable despite the uncertainty. Each harvest now requires decisions to be made without the reliable patterns that once guided coffee farming.

Across Central America, producers continue searching for ways to adapt to changing environmental and economic realities, while the long-term sustainability of smallholder coffee farming remains an open question.

Global Study Maps the “Carbon Footprint” of Latin American Coffee

Dubai – Qahwa World

A comprehensive international study released in March 2026 has revealed a sharp disparity in the carbon footprint of coffee production across five major Latin American nations. This landmark report establishes the first precise scientific baseline—using primary data collected directly from farms—to address climate change challenges within the global coffee sector.

The study, conducted by Conservation International in collaboration with the Sustainable Coffee Challenge and Meo Carbon Solutions, analyzed supply chains in Brazil, Colombia, Honduras, Mexico, and Peru. The findings provide a “wake-up call” for the industry, highlighting how specific farming practices, particularly fertilization and waste management, dictate environmental impact.

  • The Emission Gap: Colombia Leads while Mexico Sets a Benchmark

Detailed data shows that coffee production in Colombia generates the highest greenhouse gas emission intensity, averaging 5.59 kg of carbon dioxide equivalent (CO2-eq) per kilogram of green coffee. Honduras followed with 4.87 kg. In Brazil, the results varied by variety, with Arabica recording 3.22 kg compared to 2.51 kg for Robusta.

Conversely, Mexico emerged as the country with the lowest emissions in the study group, averaging just 1.46 kg. Experts attribute this lower footprint to specific traditional farming practices, including greater reliance on natural shade and organic soil health.

  • Fertilizers: The Primary Climate Culprit

According to the extensive technical report, the most significant “hotspot” for emissions in Latin American coffee is fertilizer and nutrient application. In Colombia and Brazil, fertilization accounts for approximately 60% of the total carbon footprint. This is primarily due to the heavy use of nitrogen-based inputs, which release potent greenhouse gases when interacting with the soil.

In other regions, the drivers differ. In Peru, “crop residues” and unmanaged organic decomposition were identified as the primary sources of emissions. Meanwhile, in Honduras, the traditional wet processing of coffee cherries—specifically the management of wastewater at the farm level—contributes significantly to the national baseline.

  • A “Pre-Competitive” Global Alliance

The study is the result of an unprecedented “pre-competitive” alliance involving major global coffee brands, roasters, and suppliers. Giants such as Nestlé, Starbucks, and JDE Peet’s contributed by sharing primary data and technical oversight to harmonize carbon accounting standards across the industry.

This collaboration aims to empower stakeholders to direct investments toward “regenerative agriculture.” These practices focus on reducing chemical dependency, improving on-farm waste management, and enhancing the soil’s ability to sequester carbon rather than release it.

  • A Roadmap for Investors and Farmers

The report concludes with actionable recommendations, stressing that reducing the carbon footprint is no longer just an environmental goal but a commercial necessity. As international environmental regulations tighten, understanding these baselines is essential for maintaining global market access.

The findings confirm that transitioning to integrated nutrient management, improving water efficiency, and recycling coffee by-products into natural fertilizers are the most effective ways to bridge the carbon gap revealed in countries like Colombia and Honduras.

Coffee Markets Rise Amid Middle East Shipping Disruptions

Dubai – Qahwa World

Global coffee markets moved higher last week as escalating tensions in the Middle East disrupted key shipping routes and increased freight costs, while supply developments in major producing countries also influenced market sentiment.

Arabica coffee futures began the week at 279.90 US cents per pound and briefly approached the 290-cent level before easing slightly. The market maintained upward momentum through the week, posting marginally higher closes on Wednesday and Thursday. By Friday, prices opened 5.45 cents per pound higher than the previous day’s close, supported in part by reports that Brazil’s coffee exports fell 17.4% year-on-year in February.

You may like:Shock in the Coffee Market: Colombia’s Production Drops 36%

  • Shipping routes under pressure

Market activity during the period from March 2 to March 5 was shaped largely by geopolitical developments rather than major supply news from coffee-producing regions.

Military strikes involving the United States and Israel against Iran, followed by retaliatory actions, disrupted shipping activity through the Strait of Hormuz, a critical route for global trade. At the same time, shipping companies remain cautious about passing through the Red Sea amid concerns over possible attacks by Yemeni Houthi rebels.

These risks have forced some vessels to take longer routes around the Cape of Good Hope, significantly increasing transportation times as well as freight and insurance costs. The situation has added new uncertainty to global supply chains, including agricultural commodities such as coffee.

Read also: Kim Thompson: Coffee on the Edge of Disruption

  • Weather challenges in Colombia

At origin, coffee production conditions in Colombia remain difficult due to excessive rainfall. Persistent wet weather has affected flowering, maturation, and bean development in several regions, particularly in southern areas where limited sunshine has compounded the problem.

Producers and exporters are also facing economic pressure. The stronger Colombian peso, combined with the recent decline in the C-market price, is expected to reduce revenues compared with the previous year.

As a result, exporters have slowed sales, leading to lower export volumes and rising inventories while waiting for more favorable market conditions when possible.

  • Honduras harvest nearing completion

In Honduras, the harvest season has moved well beyond its peak, with more than 75% of the crop already collected. Harvesting has largely finished in lower-altitude regions, leaving mainly higher-elevation farms still gathering the remaining coffee.

Purchasing activity remains mixed. Exporters who secured contracts earlier at higher market prices are continuing to buy coffee cherries and parchment, while others with fewer forward commitments are delaying purchases.

Read this also; Oil Surge Could Brew Higher Coffee Prices

  • Currency markets react

Currency markets were also influenced by developments in the Middle East, with the US dollar strengthening following the weekend’s military strikes.

The GBP/USD and EUR/USD currency pairs initially dropped to 1.327 and 1.155, respectively, before recovering slightly to around 1.332 and 1.160 by Tuesday afternoon.

For the remainder of the week, both pairs traded mostly within a lower range compared with previous weeks as investors monitored geopolitical developments and their potential impact on global trade and energy markets.

  • Market outlook

While major supply-side news from coffee-producing countries remained limited during the week, traders continue to monitor shipping disruptions, weather conditions at origin, export flows, and currency movements. These factors are expected to remain key drivers of short-term price movements in global coffee markets.

Belarusian “Americano”: Lukashenko Proposes a National Version

Minsk – Qahwa World

In Belarus, an unusual initiative is under discussion: President Alexander Lukashenko has suggested creating a national version of the popular Americano coffee. The proposal could affect all fast-food establishments across the country.

The idea was announced during Lukashenko’s visit to the “Mak.by” chain, which positions itself as a Belarusian alternative to international fast-food brands. The president emphasized that it is important to build national traditions even in small details, such as the names of beverages. He proposed that, initially, the new name could be shown alongside the familiar one in parentheses, allowing customers to gradually adapt to the change.

You may read: “Candiano”: From a Simple Joke to a National Debate on Identity and More

Supporting domestic brands in the food service sector has become a priority for Belarusian authorities. Renaming the Americano could become part of a broader campaign to promote national products and strengthen Belarusian cultural identity. However, the initiative may spark debates among coffee lovers accustomed to international standards and names.

The exact name for the Belarusian version of the Americano has not yet been revealed. Nevertheless, the proposal has already prompted lively discussion among entrepreneurs and café visitors: some see it as a way to highlight Belarusian uniqueness, while others view it as an unnecessary formality.


Shock in the Coffee Market: Colombia’s Production Drops 36%

Dubai – Qahwa World

Coffee production in Colombia, the world’s largest producer of washed Arabica coffee, recorded a sharp drop in February 2026. Production reached 869,000 bags, with each bag weighing 60 kilograms, marking a decline of 36% compared with the same month last year. This decrease reflects a continuing negative trend that is putting pressure on the global coffee supply.

  • Noticeable Drop in Annual Production

When looking at the total production over the last 12 months, from March 2025 to February 2026, the total reached 12.72 million bags. This represents a decline of 14% compared with the previous cycle.

German Bahamon Jaramillo, the general manager of the National Coffee Federation (FNC), said that the current situation requires urgent action to protect the stability of the sector and maintain farm productivity, according to the Argentine newspaper Infobae.

You may like: Colombian Coffee Day Celebrated at Dubai Coffee Museum

The main recommendations include improving fertilization to restore plant strength and renewing coffee farms to ensure sustainable production in the medium term. There are also calls for direct support measures for farmers to help them deal with lower profits caused by reduced production.

  • Exports Also Decline

The drop in production has also affected exports. Coffee exports in February fell by 32%, reaching 807,000 bags.

During the beginning of the agricultural season, from October to February, total exports reached 5.06 million bags. This is a decline of 14% compared with the same period in the previous cycle.

  • Production Under Pressure

Experts say this decline shows how vulnerable coffee production is to climate changes and farm management problems. It also puts pressure on global prices and may increase the cost of coffee for consumers. At the same time, it makes it more difficult for small farmers to maintain sustainable businesses.

  • Main Reasons for the Decline

Several factors are behind the drop in production.

Climate changes:
Continuous heavy rain and thick cloud cover affected flowering and plant growth. This also led to the spread of diseases such as coffee leaf rust, although detection rates remain low thanks to resistant coffee varieties.

Read Also: Historic Colombian Coffee Harvests Face Labour Shortages

Farm management challenges:
Coffee plants are showing signs of exhaustion after several years of strong production. The 2024/2025 season recorded the highest production level in 30 years. In addition, higher costs for inputs such as fertilizers and labor have increased pressure on farmers.

Weak start to 2026:
The decline follows a 34% drop in January 2026, when production reached 893,000 bags, making the start of the year one of the weakest in recent years.

  • Suggested Actions

Experts suggest several steps to address the situation.

Short term:
Improve fertilization to strengthen plants and provide direct financial support for small farmers, who produce about 70% of the country’s coffee, to help offset income losses.

Medium term:
Renew coffee farms to ensure long-term sustainability and adopt varieties that are more resistant to climate conditions. Price-stabilization mechanisms are also recommended to reduce market volatility.

Long term:
Address climate change through global strategies. A report from the International Coffee Organization (ICO) and other groups expects that global coffee production could be affected by up to 50% by 2050 if adaptation measures are not taken.

  • Impact on Global Supply

Colombia represents about 10% to 12% of global Arabica production. Because of this, any decline in its output puts pressure on the global supply, especially when production also drops in countries like Vietnam or Indonesia during some periods.

However, some of this pressure may be eased by expectations of a record Brazilian crop in the 2026/2027 season, estimated at 66.2 million bags, an increase of 17.2%. This could push global production to around 180 million bags.

Still, climate volatility keeps supply fragile. As a result, major international buyers, including the United States and Europe, may look for temporary alternatives.

  • Price Movements

Arabica prices recently fell from record levels above $4 per pound in November 2025 to about $2.80 to $3.00 per pound today, mainly because of strong crop expectations in Brazil.

However, the decline in Colombian production has helped push prices up by about 2% to 5% in recent weeks. This increase is linked to concerns about global supply and geopolitical tensions, including shipping disruptions in the Strait of Hormuz.

The World Bank expects Arabica prices to fall by 13% to 15% during 2026 overall. But this outlook could change if production in Colombia continues to decline.

For consumers, coffee prices in the market may rise by about 5% to 10% in the short term, especially in Europe and the United States.