Burke Campbell – “European Simplification is Cosmetic. The Burden Exported to Honduras Has Not Changed”

Dubai – Ali Azakary | Qahwa World

On May 4, the European Commission published its “simplification” package for the Deforestation Regulation. Some saw it as genuine relief. Others called it cosmetic.

Qahwa World continues its interview series with industry experts. After Dr. Steffen Schwarz from Germany and Kim Thompson from Dubai, our third guest is Burke Campbell.

Burke is a Canadian of Cree-Métis heritage who left the Alberta oil sands to work in coffee farms in Honduras. His journey connects resource extraction, economic sovereignty, and sustainable development. From his personal awakening to the parallel between Indigenous communities in Canada and coffee farmers in Honduras, through his pioneering work connecting Yemen’s ancient coffee heritage to modern markets, Burke’s story is one of resilience, vision, and an uncompromising pursuit of justice.

Here is what he said.

  • What is your overall take on the EU simplification decision? Does it truly reduce the burden, or is it mostly cosmetic?

Burke Campbell: Cosmetic. The real problem is who pays the documentation tax, and the May package left that architecture in place.

The Commission missed its own statutory April 30 deadline by four days, then released four instruments on May 4. They did not reopen the regulation. They cleaned up the paperwork around it.

The 75 percent compliance cost reduction announced by Commissioner Roswall was largely legislated on December 18, 2025, when the Council and Parliament shifted the due diligence filing burden away from EU traders and onto whoever first places the product on the market. The May package recycles that and adds a few line items. Soluble coffee in. Leather out.

Read the line the Commission used about its own simplified regime. The Commission itself admits that the SME and primary operator route covers close to one hundred percent of farmers and foresters in the EU. Brussels has functionally exempted itself from a regulation it is still asking a Honduran cooperative, an Ethiopian farmer, and a Ugandan smallholder to comply with. They simplified the part of the regulation that touched them. The rest stands.

I write this from Copán Ruinas, Honduras. An Alliance Bioversity and CIAT estimate places around 85 percent of producers in this country in the at-risk category for EU market exclusion, and more than half of our coffee leaves through European ports. The May package did nothing for them. Brussels reduced the burden it was carrying. The burden Brussels exported is unchanged.

  • Who benefits the most from this simplification?

Burke Campbell: Big companies. Not small producers, and not low-risk exporting countries.

Small producers do not benefit. Outside the EU they do not get the simplified declaration relief that European primary operators receive. They build the polygons themselves and pay every line of the cost.

Low-risk exporting countries get a label, not relief. A Vietnamese exporter still owes geolocation. A Colombian cooperative still owes geolocation. The “low-risk” classification means simplified due diligence. You skip the formal risk assessment step. The polygon is still required. The compliance vendor still gets paid. The country gets a sticker on the file.

Look at where the money actually lands. All of it north.

The compliance technology sector. The Mannheim platform that Goldman Sachs bought into for 120 million dollars in 2024 runs the books for more than 1,300 customers. The two billion euros in residual annual compliance cost the Commission says is left in the system after simplification is structurally allocated to this sector. Goldman bought in early so it could collect.

The big trader-roasters. They have already absorbed the cost. The downstream operator architecture means smaller importers behind them just collect reference numbers, not run their own due diligence. The supply chain runs through the platforms the big traders own. The moat is real.

The European farmer and forester. Through the small and micro primary operator route they receive a one-time simplified declaration, a postal address instead of a polygon, and in many cases a national database the member state authority will pre-fill for them.

Who pays. Smallholder cooperatives in Honduras, Ethiopia, Uganda, Colombia, Indonesia, Peru. Mid-size specialty importers in Europe without proprietary platforms. The two billion does not stay in the countries that grew the coffee. It moves north.

  • Soluble coffee is now fully covered, after being excluded before. How do you see this affecting coffee traders and roasters worldwide?

Burke Campbell: The loophole was real. If you processed non-compliant green coffee outside the EU and brought the finished instant in as an extract, you had not technically placed deforestation-linked coffee on the market. Closing it on the law’s own terms was correct.

For green coffee traders the change is administrative. The major traders already polygon-trace the green beans they handle. They add a line to their books for soluble extracts and concentrates. The systems exist. The marginal cost is low. They will absorb it.

For roasters the picture splits. A specialty roaster importing green coffee and roasting it in Hamburg or Milan was never in the soluble category. Their position is unchanged. The companies whose position changes are the integrated roaster-processors. Their soluble lines now sit inside the same chain of custody architecture as their green portfolio. Mass balance accounting gets harder under EUDR rules. Each component has to be deforestation-free and individually polygon-mapped. You cannot blend a non-compliant lot into a compliant one and call the result compliant. The whole batch has to be clean.

For origin processors the change is structural. Vietnam exports about 3.3 million bags of soluble and roasted in green bean equivalent, with 60 percent bound for Europe. Nestlé is putting another 75 million dollars into its Dong Nai plant. Trung Nguyen 75 million into Đắk Lắk. Highlands Coffee 20 million into Bà Rịa-Vũng Tàu. Food Empire 80 million into a freeze-dry facility in Bình Định. Those facilities will absorb plot-level traceability cost on top of green bean traceability cost. The shipper exporting unprocessed green to Hamburg now carries a lighter compliance load than the country that processes its own beans before they leave.

That is the deeper point. The regulation now taxes origin processing. Vertical integration. Value retained in producing countries. The pathway out of green bean dependence is processing at origin. The Commission has just made that pathway more expensive than green bean export.

  • Is the global coffee supply chain truly ready for the December 30, 2026 deadline? If not, which part of the industry will take the biggest hit?

Burke Campbell: No.

One thing first about the premise. The “except small producers” exemption you mentioned is an EU internal rule. A primary operator inside an EU member state, classified small or micro, can submit a one-time declaration through a cooperative, use a postal address instead of a polygon, and in many cases have the member state authority pre-fill the document from a national database that already exists. None of this is on offer to a small producer in Vietnam, India, Colombia, Honduras, Ethiopia, or anywhere else outside the Union. The exemption is for European small producers. Foreign smallholders in low-risk countries still build the polygons themselves and pay every line of the cost.

That single clause is the asymmetry.

The deadline is locked. December 30, 2026 for large and medium operators. June 30, 2027 for most micro and small operators outside timber. The Commission’s own information system was on limited operability from February 16 until mid-April because it could not handle the submissions it was designed to receive. It reopens in stages from June. Six months of integration time for several hundred thousand operators globally.

The polygon is the regulation’s central instrument. Once you have drawn it, your land is recorded in the EU’s traceability system, attached to every shipment that originates there.

Biggest hits, in order. African and Central American smallholder cooperatives without national traceability infrastructure. Ethiopia has approximately four million smallholders, mostly half-hectare plots, mostly shade grown, mostly unmapped. Honduras has, by Alliance Bioversity and CIAT’s estimate, around 85 percent of producers in the at-risk category, and more than half of its coffee export revenue going to Europe. Uganda has spent $9.15 million on its national register and will probably make the deadline. Then mid-size European specialty importers without proprietary platforms. Then Vietnamese and Indian instant processors, newly in scope after the soluble inclusion.

Effectively immune. The major traders with proprietary infrastructure. Nestlé, JDE Peet’s, NKG, Volcafe, Sucafina, ECOM, Olam, Louis Dreyfus, Touton, Lavazza, illycaffè. The Italian leather lobby that got leather pulled from the list. The carve-outs go to lobbies that can write back. The architecture stays where there is no lobby on the other side.

The supply chain is not ready. The architecture decides who gets to be ready.

They built a green wall. The farmers it claims to protect have been on the other side of green walls for 400 years. The trick is not to climb over. The trick is to stop accepting that the wall is the only door.

Qahwa World – Episode Four tomorrow with John Seroney from Kenya.

Read the related stories:

Kim Thompson: Sustainability Rules Must Not Punish the Producers Who Need Market Access Most

Dr. Steffen Schwarz: EUDR Simplification Remains an Administrative Monster

EUDR Simplification: Six Voices from the Coffee Industry Speak

European Commission Simplifies Deforestation Regulation.. What’s New?


World Coffee Research releases 2025 annual report


Qahwa World – Dubai |
May 14, 2026 |
7 min read |
Source: WCR Annual Report 2025

Executive Summary

  • World Coffee Research released its 2025 annual report covering January 1 to December 31, 2025
  • Innova Global Coffee Breeding Network named a TIME Best Invention of 2025
  • Network expands to include robusta coffee with six partner countries producing 64% of global robusta
  • 11 countries now in Innova network, producing 40% of world’s coffee supply
  • WCR aims to reduce breeding timeline from 30 years to 8 years using genetic markers
  • 10-year IMLVT trial results: Up to half of arabica land could become unsuitable by 2050 due to climate change
  • $4.96 million in industry contributions; $9.85 million total financial position
  • Seed system expansions in Peru, Uganda, Guatemala, Honduras to produce millions of new trees annually
  • WCR helped secure $175 million in U.S. funding for agricultural R&D including coffee

World Coffee Research (WCR) announced the release of its 2025 annual report on December 31, 2025, detailing the expansion of its TIME-recognized Innova Global Coffee Breeding Network into robusta coffee, new data showing that half of current arabica land could become unsuitable by 2050, and seed system expansions across four producing countries.

The report, which covers the period between January 1, 2025 and December 31, 2025, confirmed that WCR’s Innova network has expanded to include Coffea canephora (robusta) breeding, adding Vietnam and Ghana as new national partners. Six countries now participate in robusta breeding: Vietnam, Ghana, India, Indonesia, Rwanda, and Uganda, which together produce 64 percent of the world’s robusta supply. Overall, 11 countries make up the Innova network, producing 40 percent of global coffee supply.

An independent panel of global breeding experts commissioned by WCR’s board of directors reviewed the organization’s breeding programs in early 2025 and described the approach as a “radical step forward” that sets a new bar for coffee breeding worldwide. The Innova network was subsequently named a TIME Best Invention of 2025. The robusta breeding program combines multiple genetic groups, including a collection provided by French research institute CIRAD. Propagation began in 2025, and starting in 2027 each robusta partner will receive 1,000 unique new trees from WCR.

The report detailed that WCR is working to reduce coffee breeding timelines from the traditional 30 years to just 8 years. In 2025, the organization initiated a collaboration with Cenicafe, one of the world’s leading national coffee research institutions, and the U.S. Department of Agriculture Tropical Agricultural Research Station (USDA TARS) in Puerto Rico to develop low-cost genetic markers for Coffee Leaf Rust (CLR), the world’s most economically devastating coffee disease. In 2026, WCR will expand this work to cover Coffee Berry Disease (CBD), Coffee Fruit Rot (CFR), and Coffee Berry Borer (CBB). Once validated between 2025 and 2028, these markers will be publicly released through scholarly publication.

According to the report, 10-year results from the International Multilocation Variety Trial (IMLVT), launched in 2015 with 31 arabica varieties shared by 11 breeding programs, confirmed that coffee leaf rust resistance depends on both genetics and environment. A 2015 study by WCR and CIAT that guided site selection for the trial network identified that up to half of today’s arabica land could become unsuitable for coffee production by 2050. The IMLVT has identified high-performing varieties with strong rust resistance and stable yields. In 2026, WCR will launch CafeClima, a free online platform integrating climate modeling with IMLVT variety performance data to help farmers make data-driven replanting decisions.

WCR installed 10,000 F1 hybrid plantlets across 10 trial sites in Peru, Guatemala, and Costa Rica, planted directly in farmers’ fields through member-led trials. The report also detailed seed system expansions across four countries. In Peru, 10 new arabica seed lots were installed with 8 cooperatives, targeting 15 seed lots by 2028 producing up to 6 million seeds annually. In Uganda, 11 mother gardens for disease-resistant robusta were installed or expanded with national coffee institute NaCORI, targeting over 40 mother gardens by 2028 producing 560,000 trees per year. In Guatemala and Honduras, 12 new seed lots will be installed in 2026, producing 5.4 million seeds annually starting in 2029.

The report highlighted advocacy wins including $175 million secured in FY26 “hard earmarks” for international agricultural R&D through coordinated advocacy by U.S. member companies, with a legal requirement that a portion support coffee research. A separate coalition mobilized $850,000 for Uganda’s coffee future from UNIDO, JDE Peet’s, Lavazza Foundation and The J.M. Smucker Co.

According to the financial section of the report, total contributions earned from the coffee industry in 2025 was $4,962,000. The total year-end financial position reached $9,852,000. Figures are pre-audit. WCR confirmed the commitment of its 194 member companies from 30 countries, with 59 additional companies and individuals providing financial support in 2025. WCR’s knowledge products, including the Coffee Varieties Catalog, Sensory Lexicon, and nursery manuals, were viewed 239,722 times in 195 countries during 2025. The organization also installed a small-batch processing facility at its research farm in El Salvador, custom-designed for breeding programs to process samples from thousands of individual trees.

Frequently Asked Questions

What is the Innova Global Coffee Breeding Network?

It is the most ambitious and globally coordinated coffee breeding program in history, bringing together 11 countries to transform coffee breeding and create enhanced genetics at an accelerated pace.

What recognition did WCR receive in 2025?

The Innova network was named a TIME Best Invention of 2025, and an expert panel described WCR’s breeding approach as a “radical step forward” for coffee.

How will climate change affect coffee production according to the report?

A 2015 study by WCR and CIAT that guided the IMLVT trial network found that up to half of today’s arabica land could become unsuitable by 2050.

Which countries are part of the Innova robusta breeding program?

Vietnam, Ghana, India, Indonesia, Rwanda, and Uganda — which together produce 64 percent of the world’s robusta.

How many member companies does WCR have?

194 member companies from 30 countries, with 59 additional companies and individuals providing financial support in 2025.

What is CafeClima?

A free online platform launching in 2026 that integrates climate modeling with variety performance data to help farmers make data-driven replanting decisions.

Source: World Coffee Research Annual Report 2025
Report period: January 1, 2025 – December 31, 2025
Author: Qahwa World – Dubai
Publication date: May 14, 2026


Mexico Coffee Production Forecast to Reach 4.1 Million Bags in 2026/2027

Author: Qahwa World – Dubai
Source: USDA Foreign Agricultural Service – Mexico City Office
Report Number: MX2026-0026
Date: May 14, 2026
Executive Summary

  • Mexico coffee production forecast at 4.1 million green bean equivalent bags for MY 2026/2027
  • Production expected to increase 1 percent year-over-year driven by robusta expansion
  • Mexican coffee consists of 85 percent arabica and 15 percent robusta
  • Chiapas, Veracruz, and Puebla account for more than 80 percent of national production
  • Domestic consumption projected to rise 1 percent to 3.2 million bags
  • United States remains primary destination for Mexican coffee exports
  • Soluble coffee covers approximately 60 percent of domestic consumption

The USDA Foreign Agricultural Service forecasts Mexico coffee production for marketing year 2026/2027 at 4.1 million green bean equivalent bags, a 1 percent increase from the previous year. This marginal growth is driven by sustained investment following two years of favorable market prices and the continued expansion of robusta production.

Mexican coffee production consists of 85 percent arabica and 15 percent robusta. The three main producing states are Chiapas, Veracruz, and Puebla, which together account for more than 80 percent of national output.

Production outlook by region

Chiapas is forecast to remain the top coffee-producing state by volume in MY 2026/2027. Puebla is expected to have the highest yields at 13 green bean equivalent bags per hectare, more than double the national average. This exceptional performance is due to favorable soil conditions, investments in leaf-rust resistant plants, and infrastructure near major cities. Veracruz ranks as the second highest yielding state.

Despite a decline from 2025 peaks, coffee prices in early 2026 continue to trend well above historical averages. According to the International Coffee Organization, arabica prices averaged 331 US cents per pound as of March 2026, which is 40 percent above the ten-year average.

This extended period of profitability has enabled producers in Chiapas, Veracruz, and Puebla to reinvest in farm management. Growers have increased plant density, input application, and quality control measures. The adoption of new varieties resistant to coffee leaf rust is forecast to continue growing the sector without expanding planted area.

Key insight: Following years of widespread coffee leaf rust outbreaks, Mexican producers have gradually transitioned toward replanting arabica rust-resistant varieties. These plants are currently in their early growth stages and have yet to fruit, but they are expected to lay the foundation for a more resilient and productive sector in the coming years.

Robusta expansion

Mexico is expanding robusta production due to its resilience against disease, ability to thrive in lower-altitude climates, and demand from large soluble coffee processors. According to industry contacts, large-scale processors have prioritized local sourcing. They provide robusta farmers with contract agreements and price stability. The main producer of robusta is Chiapas, followed by Veracruz, Puebla, and Oaxaca.

For MY 2025/2026, production is estimated at 4 million green bean equivalent bags, a 4 percent increase over the previous year. This growth is driven by recovery from heat waves that affected robusta fields in MY 2024/2025. Increased investment in both robusta and arabica management, enhanced pre- and post-harvest practices, and selective harvesting to secure higher quality and market premiums have also contributed.

Domestic consumption trends

Coffee consumption is forecast at 3.2 million green bean equivalent bags for MY 2026/2027, an increase of 1 percent from the previous year. This slight growth is attributed to expansion in retail coffee shops and chains, as well as changing consumption habits favoring premium coffee.

Convenience stores are increasing the availability of ready-to-drink coffee. Caffeine, a coffee company in northern Mexico, has entered a partnership with OXXO, the largest convenience store chain in Mexico. Caffeine produces, roasts, and supplies coffee for nearly all OXXO stores in Mexico and Colombia, ensuring high quality and fast coffee service across the chain network.

Mexico is also Starbucks’ largest market in Latin America and the Caribbean, and its seventh largest globally. With an expansion of approximately 70 new stores annually, the company plans to reach 1,000 stores in the country during 2026.

Major urban areas in Mexico are showing higher demand for high-quality, single-origin coffee. This has created new markets for premium coffee products such as capsules, cold brew, and specialty offerings. Microlots are growing in popularity to meet demand for unique sensory profiles and limited editions.

Online platforms in Mexico are increasing access to specialty coffee brands, single-origin beans, and subscription programs. This online channel enables small roasters to reach customers throughout the country, allowing customers to discover artisanal and responsibly sourced coffee products.

Despite growth in the premium sector, soluble coffee remains more practical and economical, covering approximately 60 percent of domestic consumption. Coffee tricycles, common in Mexico City and other cities, offer café de olla (roasted coffee prepared with cinnamon and sweetened), soluble coffee, and hot chocolate as an affordable and traditional alternative to coffee shops.

Export and import trends

Coffee exports for MY 2026/2027 are forecast at 3.4 million green bean equivalent bags, a decrease of 1 percent from the previous year. Gains in production are expected to satisfy domestic consumption, slightly reducing export volumes.

The United States remains the primary destination market for Mexican coffee in all forms. Exports to the United States reached 2.6 million green bean equivalent bags in 2025. Mexico primarily exports green bean and soluble coffee to the US market.

Coffee imports are forecast at 2.4 million green bean equivalent bags for MY 2026/2027, a decrease of 4 percent. This trend is driven by a forecasted rise in local robusta production, reducing the need for imported green beans. In 2025, the private sector announced various investment programs aimed at increasing coffee production capacity. As a result, Mexico is substituting soluble coffee imports with domestically manufactured products.

Government support programs

Mexico’s Secretariat of Agriculture and Rural Development operates several coffee-specific producer support programs. Production for Wellbeing provides direct financial support of 388 US dollars per producer per year. In 2026, a total of 181,364 producers participated, covering an area of 216,306 hectares.

Fertilizers for Wellbeing delivered 53,542 tons of fertilizer to 151,253 producers in 2026, benefiting an area of 165,984 hectares. This initiative seeks to enhance soil fertility and boost productivity among coffee growers and is expected to expand in scope for 2026.

Café Bienestar, managed by the Secretariat of Wellbeing, aims to distribute affordable coffee through the country network of Bienestar stores. The program buys coffee from producers in Chiapas, Oaxaca, Puebla, Veracruz, and Guerrero and processes it. This program is estimated to represent 3 to 4 percent of the total soluble coffee market.

Frequently Asked Questions

How much coffee will Mexico produce in 2026/2027?
The USDA forecasts Mexico coffee production at 4.1 million green bean equivalent bags for MY 2026/2027, a 1 percent increase from the previous year.

Which states produce the most coffee in Mexico?
Chiapas, Veracruz, and Puebla are the three main coffee-producing states, together accounting for more than 80 percent of national production. Chiapas remains the top producer by volume.

What is the breakdown between arabica and robusta in Mexico?
Mexican coffee production consists of 85 percent arabica and 15 percent robusta. Robusta production is expanding due to its disease resistance and demand from soluble coffee processors.

How is coffee leaf rust affecting Mexican production?
Following years of widespread coffee leaf rust outbreaks, producers have gradually transitioned to replanting arabica rust-resistant varieties. These plants are in early growth stages and are expected to create a more resilient sector.

What is the coffee consumption trend in Mexico?
Domestic consumption is forecast at 3.2 million bags, a 1 percent increase. Soluble coffee covers approximately 60 percent of consumption, while premium and specialty coffee segments are growing rapidly.

Who is the primary buyer of Mexican coffee?
The United States remains the primary destination market for Mexican coffee exports, receiving 2.6 million green bean equivalent bags in 2025.


Author: Qahwa World – Dubai
Source: USDA Foreign Agricultural Service – Mexico City Office
Report Number: MX2026-0026
Date: May 14, 2026

Nuova Simonelli Technicians Competition Returns for 2026  

Author: Qahwa World – Dubai
Source: Industry announcement
Date: May 14, 2026
Executive Summary

  • The Nuova Simonelli Technicians Competition is back after its first edition in France
  • The 2026 edition expands to new international stages in Paris, London, and the Middle East
  • The competition begins with an online technical quiz that selects 8 finalists
  • Finalists then face hands-on practical challenges on espresso machines
  • Judges evaluate speed, precision, machine knowledge, and safety practices
  • The event celebrates technicians who work behind the scenes in the coffee industry

The Nuova Simonelli Technicians Competition is returning in 2026. After its first edition in France, the event is now expanding to new international markets including Paris, London, and the Middle East.

The competition focuses on espresso machine technicians. These professionals typically work behind the scenes. Yet they play a vital role in coffee quality, equipment reliability, and cafe performance.

Origins of the competition

The competition first launched in France. Organizers created it to showcase the skills, experience, and professionalism of coffee machine technicians. These workers often remain unseen by customers. Nevertheless, they maintain the equipment that baristas rely on every day.

Nuova Simonelli, the Italian espresso machine manufacturer, organizes the event. The company aims to highlight the strategic importance of technicians in delivering quality service and reliable products.

What sets this competition apart

The Nuova Simonelli Technicians Competition stands out for its hands-on, practical approach. It tests real-world skills that technicians use daily.

The competition begins with an online technical quiz. From this stage, organizers select eight technicians who qualify for the final round.

In the final stage, participants face practical challenges on espresso machines. These include simulated malfunctions, adjustments, and real technical interventions. The tasks mirror everyday work scenarios in coffee shops and service centers.

Speed, precision, machine knowledge, and operational efficiency all go under evaluation. Technical judges assess performance based on workplace safety, organization, technical expertise, and the ability to maintain excellent coffee quality.

Expansion to new markets in 2026

In the coming weeks, the competition will launch new international stages. The confirmed locations include Paris, London, and the Middle East.

This expansion confirms the global nature of the initiative. Nuova Simonelli aims to create real opportunities for exchange, professional growth, and knowledge sharing across key international markets.

Industry context: Coffee machine technicians play a critical role across the entire supply chain. Their work ensures operational continuity, consistent quality, and customer satisfaction in cafes worldwide.

Celebrating the technicians

Through this initiative, Nuova Simonelli celebrates the crucial role technicians play. They provide baristas with reliable, high-performing, and long-lasting equipment. Their work supports operational continuity, consistent quality, and end-customer satisfaction.

The event is more than just a competition. Organizers describe it as a platform for training, networking, and showcasing technical expertise.

How to participate

Technicians ready to join the next editions of the competition can apply through dedicated registration pages. Separate application links are available for the Dubai and United Kingdom editions.

Frequently Asked Questions

What is the Nuova Simonelli Technicians Competition?
It is an international competition for espresso machine technicians. Participants demonstrate their skills in diagnosing and repairing coffee equipment under timed conditions.

Where will the competition take place in 2026?
The competition will take place in Paris, London, and the Middle East. Specific venues and dates are available through the official registration pages.

How does the competition work?
Participants first complete an online technical quiz. The top eight scorers advance to a final round of hands-on practical challenges on espresso machines.

What skills are tested?
Judges evaluate speed, precision, machine knowledge, operational efficiency, workplace safety, organization, and the ability to maintain coffee quality.

Who can participate?
The competition is open to espresso machine technicians. Interested candidates should apply through the official registration pages for their region.

Why is this competition important?
Technicians play a crucial but often invisible role in the coffee industry. They ensure equipment remains reliable and performs well, which directly affects coffee quality and customer satisfaction.


Author: Qahwa World – Dubai
Source: Industry announcement
Date: May 14, 2026

South Korea Tightens Regulations on Decaffeinated Coffee

Dubai – Qahwa World

South Korea’s Ministry of Food and Drug Safety has announced stricter regulations for decaffeinated coffee products, stating that products will only be allowed to carry the “decaffeinated” label if they contain no more than 0.1% residual caffeine in the coffee beans.

The new labeling standards are set to take effect on January 1, 2028.

Under the current rules, at least 90% of the caffeine must be removed from coffee for it to be classified as decaffeinated. However, existing regulations do not specify the final amount of caffeine that may remain in the product. The term “decaffeinated” also does not necessarily mean that the coffee is completely caffeine-free, which can lead to consumer misunderstanding.

The ministry explained that some decaffeinated coffee products may still contain relatively high levels of residual caffeine, especially when made from naturally high-caffeine coffee beans. This, officials said, conflicts with consumer expectations that decaffeinated coffee should contain little to no caffeine.

To reduce confusion, the updated standards will focus on the amount of caffeine remaining in the beans, aligning South Korea’s regulations more closely with international standards, including those used in the United States.

In a related move, the ministry also strengthened labeling requirements for alcoholic beverages amid a rise in collaborative products featuring alcohol brands packaged in designs resembling ordinary food products.

Ukrainian Authorities Uncover Large-Scale Counterfeit Coffee Operation Near Kyiv

Author: Qahwa World – Dubai
Source: Korrespondent.net
Date: May 14, 2026Authorities recently uncovered a counterfeit coffee operation in Kyiv, Ukraine in 2026.

Executive Summary

  • Ukrainian authorities discovered an illegal coffee production facility in the Kyiv region
    Counterfeit products appeared under internationally known brand names
    Suspects allegedly continued using the brand illegally after their contract ended in 2021
    The fake coffee underwent no quality or safety controls, which posed consumer risks
    Authorities conducted 22 searches and seized assets worth nearly UAH 20 million
    The investigation remains ongoing under Criminal Code Article 229 for trademark violation
    A similar operation emerged in July 2025 with an organizer and five accomplices

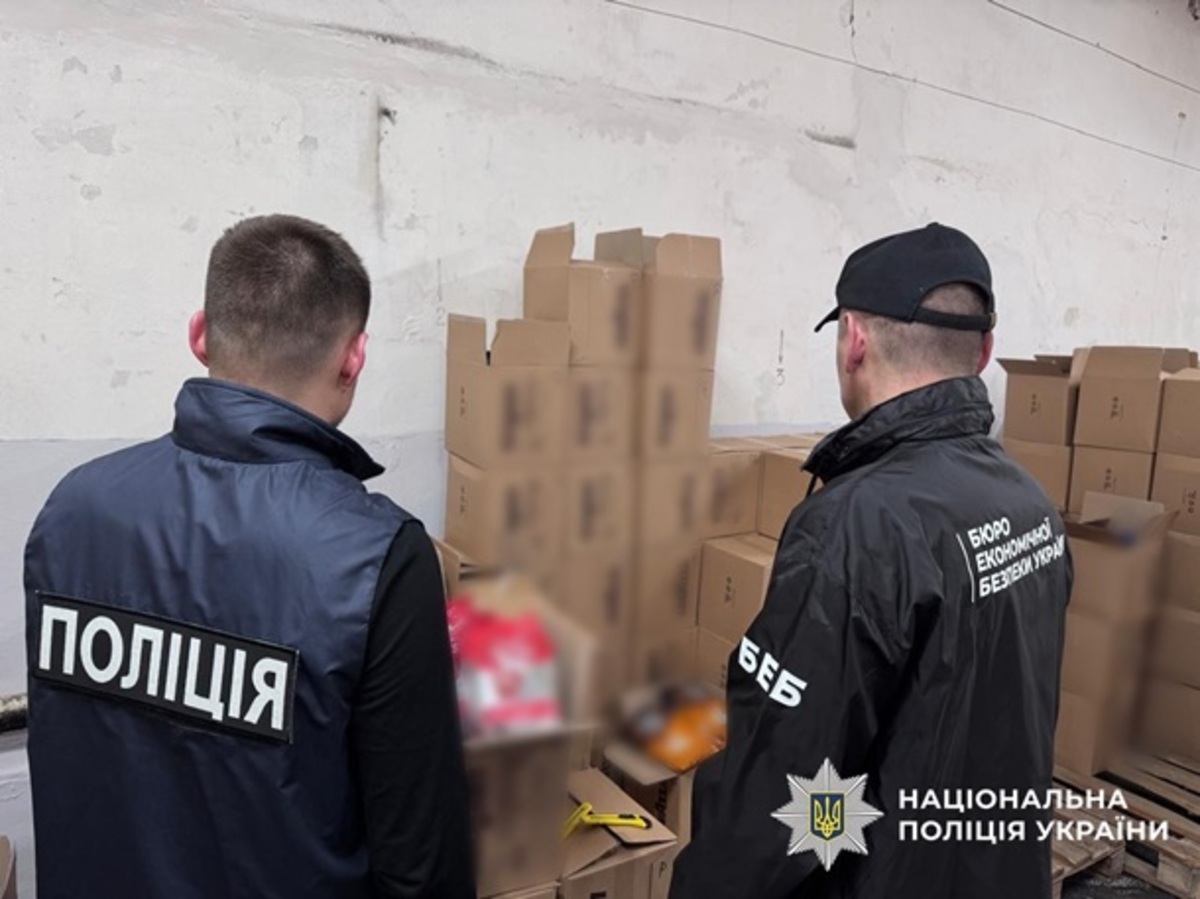
The Bureau of Economic Security of Ukraine uncovered a large-scale underground operation near Kyiv. This facility produced counterfeit coffee products under internationally known brand names.

Investigators discovered illegal production facilities inside warehouse premises. Workers roasted, packaged, and labeled coffee at these locations. They used trademarks of major global coffee brands without permission.

  • How the counterfeit scheme operated

The scheme involved individuals registered under fictitious businesses. These entities processed payments and supported the distribution network. Therefore, authorities had to trace multiple financial transactions.

Suspects had previously cooperated officially with the trademark owner. However, they allegedly continued using the brand illegally after their contract ended in 2021. As a result, the company lost significant revenue.

Social media platforms and messaging applications helped promote the counterfeit products. Postal and courier delivery services distributed orders across Ukraine. Consequently, the fake coffee reached many unsuspecting customers.

  • Consumer safety risks

The fake coffee products underwent no quality or safety controls. Therefore, they may have posed serious health risks to consumers. Authorities warn buyers to remain vigilant.

Detectives conducted 22 searches during the investigation. They seized industrial production equipment, packaging materials, and printing supplies. In addition, they confiscated thousands of finished coffee packages, raw coffee materials, vehicles, cash, and financial documentation.

The seized assets hold an estimated value of nearly 20 million Ukrainian hryvnia.

  • Legal proceedings

The pre-trial investigation remains ongoing. Authorities filed the case under Part 3 of Article 229 of the Criminal Code of Ukraine. This article covers the illegal use of trademarks that causes particularly large financial damages.

  • Growing challenge of counterfeit food products

This case highlights a growing challenge for the coffee industry. Counterfeit food and beverage products threaten both consumers and legitimate coffee companies. Rising coffee prices continue to increase pressure across global supply chains. Therefore, counterfeit operations may become more common.

In July 2025, authorities announced suspicions against an organizer and five alleged accomplices. Those individuals operated another underground coffee manufacturing network in the Kyiv region. They also used internationally recognized brand names illegally.

Context: The Bureau of Economic Security of Ukraine continues to investigate illegal trademark violations in the food and beverage sector. Consumers should purchase coffee products only from authorized retailers.

Frequently Asked Questions

Where did authorities discover the counterfeit coffee operation?

The illegal production facility operated in the Kyiv region of Ukraine. Workers roasted, packaged, and labeled fake coffee inside warehouse premises.

Which brands did the operation counterfeit?

The operation used internationally known coffee brand trademarks. However, authorities have not publicly disclosed specific brand names due to the ongoing investigation.

How long did the illegal operation continue?

Suspects had an official contract with the trademark owner that ended in 2021. After that, they allegedly continued using the brand illegally.

What is the value of the seized assets?

Authorities seized assets worth nearly 20 million Ukrainian hryvnia. These include industrial equipment, packaging materials, finished coffee products, vehicles, and cash.

Are the counterfeit products dangerous?

Yes. The fake coffee underwent no quality or safety controls, so it may pose health risks to consumers.

Is this the only such case in Ukraine?

No. In July 2025, authorities announced suspicions against an organizer and five accomplices in another underground coffee manufacturing network in the same region.

Author: Qahwa World – Dubai
Source: Korrespondent.net
Date: May 14, 2026
Reference: Bureau of Economic Security of Ukraine, Criminal Code of Ukraine Article 229

Coffee Prices Supported by Shrinking ICE Inventories as Supply Tightens

Author: Qahwa World – Dubai. This article reviews ICE coffee inventories and coffee prices projections for 2026.

Executive Summary

  • July arabica coffee gained 0.21%, while July robusta rose 2.24% to a seven-week high
  • ICE robusta inventories fell to a two-year low of 3,642 lots
  • ICE arabica stocks dropped to a 2.5-month low of 471,831 bags
  • Brazil April green coffee exports declined 1.3% year-over-year to 2.76 million bags
  • Vietnam January-April coffee exports surged 15.8% to 810,000 metric tons
  • Global coffee surplus projected to reach 10 million bags in 2026, largest in six years

Coffee futures settled higher in Wednesday trading as shrinking exchange inventories continued to provide market support, with robusta prices climbing to their highest level in nearly two months.

July arabica coffee on the New York exchange rose 0.60 points, or 0.21 percent, while July robusta coffee on the London exchange advanced 78 points, or 2.24 percent, reaching a seven-week peak.

Tightening stocks on the Intercontinental Exchange remained the primary bullish factor for the market. Robusta inventories fell to a two-year low of 3,642 lots on Wednesday, while arabica stocks dropped to a two-and-a-half-month low of 471,831 bags earlier in the week.

Reduced shipments from Brazil also provided price support. The country’s April green coffee exports declined 1.3 percent compared to the same period last year, totaling 2.76 million bags, according to industry data.

Disruptions in key shipping routes have raised concerns over global coffee supply chains, contributing to higher costs for freight, insurance, fertilizers, and fuel for importers and roasters.

On the bearish side, rising shipments from Vietnam, the world’s largest robusta producer, continued to weigh on the market. Vietnamese coffee exports during the first four months of 2026 increased 15.8 percent year-over-year to 810,000 metric tons. The country’s total coffee exports for 2025 also rose 17.5 percent to 1.58 million metric tons.

Supply outlook: Vietnam coffee production for the 2025/2026 season is projected to increase 6 percent to 1.76 million metric tons (29.4 million bags), which would mark a four-year high for the Southeast Asian producer.

Expectations of a larger Brazilian harvest are also placing downward pressure on prices. Recent projections indicate Brazil 2026/2027 coffee harvest could rise 12 percent year-over-year to 71.4 million bags.

Several trading firms have issued forecasts pointing to record production levels. A major commodities brokerage projected Brazil 2026/2027 crop at 75.9 million bags, while another trading firm raised its estimate to a record 75.3 million bags.

The global coffee surplus in 2026 could expand to 10 million bags, compared with 1.8 million bags in 2025, which would represent the largest surplus in six years, according to industry analysts.

Global coffee exports for the current October-September marketing year slipped 0.3 percent year-over-year to 138.66 million bags, based on data from the International Coffee Organization.

Looking further ahead, the United States Department of Agriculture Foreign Agricultural Service projects that global coffee production in 2025/2026 will rise 2 percent year-over-year to a record 178.85 million bags. The agency forecasts arabica production to decline 4.7 percent to 95.52 million bags, while robusta production is expected to increase 10.9 percent to 83.33 million bags.

Brazil production for 2025/2026 is forecast to fall 3.1 percent to 63 million bags, while Vietnam output is projected to rise 6.2 percent to a four-year high of 30.8 million bags.

The USDA also expects ending stocks for the 2025/2026 season to decline 5.4 percent to 20.15 million bags, down from 21.31 million bags in the previous season.

Frequently Asked Questions

Why did coffee prices rise recently?
Coffee prices moved higher primarily due to shrinking ICE inventories. Arabica stocks fell to a 2.5-month low, while robusta inventories dropped to a two-year low, tightening available supply.

How did Brazil coffee exports perform in April?
Brazil April green coffee exports declined 1.3 percent year-over-year to 2.76 million bags, providing some support to coffee prices.

What is happening with Vietnam coffee exports?
Vietnam coffee exports surged 15.8 percent in the first four months of 2026 to 810,000 metric tons, which has weighed on prices due to increased supply from the world largest robusta producer.

What is the global coffee surplus forecast for 2026?
The global coffee surplus in 2026 could expand to 10 million bags, up from 1.8 million bags in 2025, marking the largest surplus in six years.

What does the USDA forecast for global coffee production?
The USDA projects global coffee production will reach a record 178.85 million bags in 2025/2026, a 2 percent increase year-over-year, with robusta driving the growth.

How are Strait of Hormuz disruptions affecting coffee prices?
Disruptions in the Strait of Hormuz have raised concerns over global coffee supply chains, increasing shipping, insurance, fertilizer, and fuel costs for importers and roasters, which supports higher coffee prices.


Kim Thompson: Sustainability Rules Must Not Punish the Producers Who Need Market Access Most

Dubai – Ali Azakary | Qahwa World

On May 4, the European Commission published its “simplification” package for the Deforestation Regulation. Some saw it as genuine relief. Others called it cosmetic.

Qahwa World continues its interview series with industry experts. After Dr. Steffen Schwarz from Germany, our second guest is Kim Thompson, Co-Founder of RAW Coffee Company in Dubai. Kim is one of the pioneers of specialty coffee in Dubai, with real contributions to supporting smallholder farmers, especially in several producing and low-income countries.

Here is what she said.

  • What is your overall take on the EU simplification decision? Does it truly reduce the burden, or is it mostly cosmetic?

Kim Thompson: Our overall take is that the simplification helps, but only around the edges. It reduces some paperwork and gives smaller primary operators a more realistic route in, but it does not remove the biggest pressure point: traceability back to farm level.

The EU says the package could reduce annual compliance costs by around 75 percent, but geolocation, legality checks, and responsibility still sit heavily in the supply chain.

Our view is simple: the intention is right, but implementation has to be practical, fair, and producer focused. Traceability is important. Protecting forests is important. But if compliance becomes a paperwork race won only by the biggest players, then the coffee industry has not solved the problem. It has just moved the burden further down the chain.

  • Who benefits the most from this simplification in your opinion?

Kim Thompson: The biggest winners are not necessarily the smaller farmers and cooperative groups who are our direct trade partners. The real advantage goes to larger organizations and companies, and to origins that already have digital traceability systems, mapped farms, organized exporters, and strong documentation.

Low-risk countries get some relief on risk assessment, but they still need geolocation data, so it is not a free pass.

  • Soluble coffee is now fully covered, after being excluded before. How do you see this affecting coffee traders and roasters worldwide?

Kim Thompson: Logically, it makes sense. If green coffee is covered, soluble coffee should not sit outside the system. Otherwise, the industry risks moving deforestation exposure into a different product category rather than solving it.

But this will affect traders, instant coffee manufacturers, private label suppliers, and roasters using soluble ingredients, because they now need the same confidence in origin data and documentation.

  • Is the global coffee supply chain truly ready for the December 30, 2026 deadline? If not, which part of the industry will take the biggest hit?

Kim Thompson: Is the global coffee supply chain ready by December 30, 2026? Honestly, no. Not even close.

Larger companies are much closer. The vulnerable part is the smallholder end: farmers, collectors, cooperatives, and exporters in fragmented supply chains where coffee changes hands many times before export.

These people may be producing responsibly, but if they cannot prove it in the format the EU wants, they risk being excluded. That is the real concern for us: sustainability rules must not end up punishing the very producers who need market access the most.

Qahwa World – Episode Three tomorrow with Burke Campbell from Honduras.

Read the related stories:

Dr. Steffen Schwarz: EUDR Simplification Remains an Administrative Monster

EUDR Simplification: Six Voices from the Coffee Industry Speak

European Commission Simplifies Deforestation Regulation.. What’s New?

USDA Announces Second Tranche of Food for Peace Funding for Seven Countrie

Executive Summary

  • USDA announces second tranche of Food for Peace Title II Program funding
  • Applications accepted from 7 countries: DRC, El Salvador, Ethiopia, Guatemala, Haiti, Kenya, Rwanda
  • Program transferred to USDA administration on February 3, 2026
  • Focus on delivering US-grown commodities to global food assistance programs
  • Application deadline: June 12, 2026 at 5:00 PM EDT

The U.S. Department of Agriculture’s Foreign Agricultural Service today announced a second tranche of funding for the Food for Peace, Title II Program. Under a competitive Notice of Funding Opportunity, USDA will accept applications from the Democratic Republic of Congo, El Salvador, Ethiopia, Guatemala, Haiti, Kenya and Rwanda.

USDA announced on February 3, 2026, that pursuant to a temporary interagency agreement, it would administer the Food for Peace, Title II Program. The move transferred management of the historic food assistance program from the U.S. Agency for International Development to USDA.

Context: Food for Peace joins USDA’s existing portfolio of international food assistance programs, including the McGovern-Dole International Food for Education and Child Nutrition Program and Food for Progress.

“USDA is working to return Food for Peace to its core functions,” said Michelle Bekkering, Deputy Under Secretary for Trade and Foreign Agricultural Affairs. “This funding will more responsibly deliver lifesaving food assistance with high-quality American commodities, helping American farmers and producers at home and people in need across the world.”

Eligible Countries for Funding

  • Democratic Republic of Congo
  • El Salvador
  • Ethiopia
  • Guatemala
  • Haiti
  • Kenya
  • Rwanda

Food for Peace joins USDA’s portfolio of longstanding food assistance programs, alongside the McGovern-Dole International Food for Education and Child Nutrition Program and Food for Progress.

The Food for Peace NOFO on Grants.gov describes this funding in detail. Eligible applicants include public or private organizations, including intergovernmental organizations and other multilateral organizations.

Application deadline: 5:00 p.m. Eastern Daylight Time on June 12, 2026.

Frequently Asked Questions

What is the Food for Peace Title II Program?
Food for Peace is a historic U.S. government food assistance program that provides emergency and development food aid to countries facing hunger and food insecurity. Title II specifically covers the donation of U.S.-grown commodities.

Which countries are eligible for this funding?
The seven eligible countries are: Democratic Republic of Congo, El Salvador, Ethiopia, Guatemala, Haiti, Kenya, and Rwanda.

When was USDA given authority over Food for Peace?
USDA announced the temporary interagency agreement on February 3, 2026, transferring administration of the program from USAID to USDA.

What is the application deadline?
Applications must be submitted by 5:00 p.m. Eastern Daylight Time on June 12, 2026.

Where can I find the full NOFO?
The complete Notice of Funding Opportunity is available on Grants.gov.

Who is eligible to apply?
Public or private organizations, including intergovernmental organizations and other multilateral organizations, are eligible to apply.


USDA Report: India’s Coffee Sector Faces Climate Challenges and Historic Trade Opportunities

Executive Summary

  • India MY 2026/27 coffee production forecast at 6.14 million 60-kg bags
  • Arabica yields expected to decline 8% due to excessive rainfall followed by extended dry spell
  • Farmgate prices for Arabica down 16%, Robusta down 11% since October 2025
  • New free trade agreements with UK and EFTA countries offer zero tariffs on Indian coffee exports
  • Domestic consumption projected at 1.58 million bags, driven by soluble coffee demand
  • India aims to reach 900,000 metric tons production by 2047

1. Overview: India’s Position in Global Coffee Market

India ranks as the world’s seventh-largest coffee producer, after Brazil, Vietnam, Colombia, Indonesia, Ethiopia, and Uganda. Approximately 95 percent of India’s coffee production is exported, with green coffee accounting for about 59 percent of total exports and instant (soluble) coffee making up the remaining 41 percent.

According to the USDA Foreign Agricultural Service report from the New Delhi office, India’s coffee sector is at a critical juncture. The country faces climate-related production challenges while simultaneously gaining unprecedented access to European markets through newly ratified free trade agreements.

Key Insight: India’s coffee production comprises approximately one-third Arabica and two-thirds Robusta, with Robusta accounting for over 75% of total output due to its greater resilience to weather variability.

2. Production Forecast: MY 2026/27

FAS Mumbai forecasts India’s MY 2026/27 coffee production at approximately 368,400 metric tons, or about 6.14 million 60-kilogram bags, comprising 1.56 million 60-kg bags of Arabica (93,600 metric tons) and 4.58 million 60-kg bags of Robusta (274,800 metric tons).

📊 Figure 1: India Production Trend
Source: USDA/FAS (Chart data described below)
Figure 1: India coffee production has grown at a CAGR of 2.05% between MY 2021/22 and MY 2024/25

Production Data Table

Table 1: India Coffee Production Forecast (1000 60-kg bags)
Category MY 2024/25 (Actual) MY 2025/26 (Estimate) MY 2026/27 (Forecast)
Arabica Production 1,762 1,730 1,560
Robusta Production 4,297 4,700 4,580
Total Production 6,059 6,430 6,140

3. Climate Challenges: The Threat to Arabica

The India Meteorological Department’s first long-range outlook for the 2026 southwest monsoon indicates below-normal rainfall at about 92 percent of the long-period average, with a 66 percent probability of below-normal to deficit conditions.

Arabica output is expected to decline due to below-normal monsoon rainfall combined with unusually high temperatures, which may adversely affect flowering and fruit set. In contrast, Robusta production is projected to remain relatively strong, reflecting its greater resilience to weather variability.

Rainfall Data for Coffee Growing Regions

Table 2: Rainfall Statistics for Karnataka and Kerala (January – April 2026)
State/District Winter (Jan-Feb) Departure Pre-Monsoon (Mar-Apr) Departure
Chikmagalur (Karnataka) Large Excess (+244%) Normal (-17%)
Kodagu (Karnataka) Large Excess (+177%) Normal (-7%)
Wayanad (Kerala) Large Excess (+235%) Deficit (-48%)
Travancore (Kerala) Excess (+48%) Deficit (-53%)

The data reveals a stark pattern: excessive winter rainfall (January-February) followed by deficit pre-monsoon rains (March-April). This extreme weather variability – from flooding to drought within weeks – is precisely the type of climate shock that most damages coffee flowering and fruit set, particularly for the more sensitive Arabica variety.

4. Yield Projections

For MY 2026/27, Arabica yields are projected to decline by eight percent year-on-year to 452 kilograms per hectare, while Robusta yields are expected to fall marginally by two percent to 1,239 kilograms per hectare, although still above the three-year average.

Table 3: Coffee Yield Comparison (kg per hectare)
Coffee Type MY 2026/27 Forecast 3-Year Average (2022-2024) Change
Arabica 452 475 -8%
Robusta 1,239 1,156 +7% (above average)
Why Robusta Outperforms: Robusta yields remain about 2.3 times higher than Arabica, reflecting its greater resilience and productivity. Arabica is more sensitive to altitude, pest, and climate variability, requiring more precise growing conditions.

5. Price Dynamics: Decline from Record Highs

Farmgate prices for Arabica and Robusta have declined by 16 percent and 11 percent respectively since October 2025. Despite this change, prices remain at a premium to other origins, though further moderation is expected. The decline in prices is being driven by expectations of higher output in key producing countries and elevated domestic stock levels.

📊 Figure 2: Farmgate Raw Coffee Prices in Karnataka
Exchange rate: Rupees 92.99 per US dollar (as of April 20, 2026)
Source: Coffee Board of India
Figure 2: Indian coffee prices have moderated but still trade at premium to competing origins

6. Export Outlook: Trade Agreements Transform Market Access

Post forecasts that MY 2026/27 coffee exports will rise by three percent to 6.22 million bags (373,140 metric tons), driven by higher exportable surplus and strong demand for soluble coffee exports.

New Free Trade Agreements

Table 4: New Trade Agreements Benefiting Indian Coffee Exports
Agreement Partner Countries Benefit for Coffee Effective Date
India-UK CETA United Kingdom Zero duty on roast, ground, and instant coffee Recently concluded
India-EFTA TEPA Switzerland, Norway, Iceland Zero percent duty on all coffee exports October 1, 2025

The United Kingdom currently accounts for 1.7 percent of India’s coffee exports, while the EFTA countries (Switzerland, Norway, Iceland) offer new zero-tariff access. Europe has emerged as a more stable trading partner with increased inquiries. Italy remains the top destination, using almost 60 percent of imported Indian coffee domestically while 40 percent is processed for private label manufacturers for re-exports.

Export Destinations

📊 Figure 3: Coffee Export Share by Country (percentage)
Italy leads, followed by Germany, Russia, Belgium, and UAE
Source: Trade Data Monitor, LLC
Figure 3: Indian coffee exported to more than 125 countries, with 61% of shipments from Mangalore port

7. Export Challenges: Premium Prices and Freight Costs

Despite positive momentum, several challenges exist. Indian coffee prices are significantly higher than competing origins from Vietnam and Indonesia. High premiums could pose challenges to exports despite recent prices being lower than last year.

Freight costs to the Middle East have surged dramatically, from $700-$1,200 per 20-foot container in January/February to $1,500-$2,800, with occasional short-term spikes higher due to war risk surcharges, insurance costs, and vessel rerouting. Trade data indicates that about 11-12 percent of India’s total coffee exports in green bean equivalent go to the Middle East, the second-largest regional market after Europe (44-45 percent).

8. Domestic Consumption: A Growing Market

Post forecasts MY 2026/27 domestic consumption at 1.58 million 60-kilogram bags (94,800 metric tons), supported by rising demand for soluble coffee. Household consumption of soluble coffee is expected to account for a significantly larger share of domestic consumption, rising to around 73 percent next year.

India’s per capita coffee consumption remains at 0.04 kilograms, well below the global average of 1.3 kilograms, indicating significant growth potential.

Table 5: Domestic Consumption Breakdown (1000 60-kg bags)
Category MY 2024/25 MY 2025/26 MY 2026/27 Forecast
Roast & Ground Domestic 330 415 420
Soluble Domestic 820 1,160 1,160
Total Domestic Consumption 1,150 1,575 1,580

9. Long-Term Vision: India 2047

The Coffee Board of India has set an ambitious long-term target of increasing national coffee production to 900,000 metric tons by 2047, through a combination of productivity gains, area expansion, and value-chain improvements. This includes replanting old and low-yielding bushes with high-yielding, climate-resilient varieties, promoting better agronomic practices (irrigation, pruning, soil health), and expanding cultivation into non-traditional regions.

📊 Figure 4: Monthly Coffee Exports by Volume (October-September)
5-year average vs 2024/25 vs 2025/26
Source: Trade Data Monitor, LLC
Figure 4: Exports in MY 2025/26 (October-January) were 26% higher than the previous year

10. Imports: Filling the Gap

Post forecasts MY 2026/27 imports at 1.39 million 60-kilogram bags (83,400 metric tons). Imports are expected to be four percent higher than last year as the use of Indian coffee in soluble coffee re-exports remains limited due to domestic beans trading at a premium, necessitating higher reliance on imported beans for processing and value addition.

Green beans account for approximately 94 percent of total imports and are primarily sourced from Indonesia, Kenya, Vietnam, Uganda, and Brazil for processing and re-export.

Table 6: India Import Tariff on Coffee Products
HS Code Product Description Standard Rate
0901.11 Coffee not roasted, not decaffeinated 100%
0901.12 Coffee not roasted, decaffeinated 100%
0901.21 Coffee roasted, not decaffeinated 100%
2101.11.20 Instant coffee not flavored 30%

11. Key Challenges Facing Indian Coffee Sector

  • Climate Variability: Excessive rainfall followed by extended dry spells during critical flowering stage
  • Fertilizer Costs: Persistent shortages and rising input costs across the value chain
  • Labor Availability: Coffee production is labor intensive, with nearly 70% of production cost attributable to labor
  • Premium Pricing: Indian coffee prices significantly higher than competing origins from Vietnam and Indonesia
  • Freight Disruptions: Surging shipping costs to Middle East due to geopolitical tensions

12. Opportunities

  • Free Trade Agreements: Zero tariff access to UK, Switzerland, Norway, and Iceland
  • Growing Domestic Market: India’s coffee market projected to grow at 8.9% CAGR by 2028
  • Soluble Coffee Demand: Double-digit growth in domestic soluble coffee consumption
  • Specialty Coffee: Estate branded coffees commanding prices comparable to export levels
  • Youth Demographic: Expanding urban coffee culture and younger consumers driving growth

Frequently Asked Questions

How much coffee will India produce in 2026/27?

According to the USDA FAS report, India is forecast to produce 6.14 million 60-kilogram bags (approximately 368,400 metric tons) in MY 2026/27, comprising 1.56 million bags of Arabica and 4.58 million bags of Robusta.

Why is Arabica production expected to decline?

Arabica yields are projected to decline 8% due to excessive rainfall in January and February 2026 followed by an extended dry spell during the critical flowering and fruiting stage. Arabica is more temperature-sensitive and has higher water requirements compared to Robusta.

What are the new trade agreements benefiting Indian coffee?

The India-UK Comprehensive Economic and Trade Agreement (CETA) offers duty-free access for roast, ground, and instant coffee to the United Kingdom. The India-EFTA Trade and Economic Partnership Agreement (TEPA), effective October 1, 2025, provides zero percent duty on all coffee exports to Switzerland, Norway, and Iceland.

How have coffee prices changed in India?

Farmgate prices for Arabica have declined by 16 percent and Robusta by 11 percent since October 2025. Despite this decline, Indian coffee prices remain at a premium to other origins, though further moderation is expected.

What is India’s long-term coffee production target?

The Coffee Board of India has set an ambitious target of increasing national coffee production to 900,000 metric tons by 2047 through productivity gains, area expansion, replanting with high-yielding varieties, and value-chain improvements.

Who are the main buyers of Indian coffee?

Italy remains the major buyer, followed by Germany, Russia, Belgium, and the United Arab Emirates. Indian coffee is now exported to more than 125 countries, with approximately 61 percent of shipments originating from the Mangalore port in Karnataka.


Strong Dollar Weighs on Coffee Prices

Dubai – Qahwa World

Coffee futures closed lower on Tuesday as a stronger U.S. dollar pressured commodity markets. This is a clear example of how a Strong Dollar Weighs on Coffee Prices. July arabica coffee contracts (KCN26) fell 0.76%, while July robusta futures (RMN26) declined 0.63%.

Losses were limited by tightening certified coffee inventories. ICE arabica stocks dropped to a 2.5-month low of 471,831 bags, while robusta inventories fell to a two-year low of 3,664 lots.

The ongoing closure of the Strait of Hormuz continued to disrupt global coffee trade flows, increasing shipping, insurance, fuel, and fertilizer costs for importers and roasters.

Brazil’s weaker export performance also supported prices. Cecafe reported that Brazil’s March green coffee exports declined 10% year-on-year to 2.65 million bags, while the country’s Trade Ministry said total March coffee exports fell 31% to 151,000 metric tons.

Meanwhile, rising supplies from Vietnam weighed on robusta prices. Vietnam’s coffee exports during January–April 2026 increased 15.8% year-on-year to 810,000 metric tons, according to the National Statistics Office. The country’s 2025/26 coffee production is expected to rise 6% to a four-year high of 1.76 million metric tons.

Expectations of a larger Brazilian crop also added bearish pressure. Recent forecasts from the Coffee Trading Academy, Marex Group, Sucafina, and StoneX all point to strong production in Brazil’s 2026/27 season, with estimates ranging from 71.4 million to 75.9 million bags.

StoneX also expects the global coffee surplus to expand to 10 million bags in 2026, compared with 1.8 million bags in 2025.

The USDA’s Foreign Agricultural Service forecasts global coffee production in 2025/26 will reach a record 178.848 million bags, driven by stronger robusta output, while global ending stocks are projected to decline 5.4% to 20.148 million bags.

Dr. Steffen Schwarz: EUDR Simplification Remains an Administrative Monster

Dubai – Ali Al Zakry | Qahwa World

On May 4, the European Commission published its “simplification” package for the Deforestation Regulation. Some saw it as genuine relief. Others called it cosmetic. Dr Steffen Schwarz described the EUDR as an administrative monster.

Qahwa World opened this file from the beginning. We spoke to six experts from four continents. We published a preliminary investigation summarizing their views. Now we publish the full episodes, one expert per episode, with complete, unedited answers.

Our first guest is Dr. Steffen Schwarz, an applied coffee science expert from Germany and co-founder of Applied Coffee Science. He describes the simplified regulation as “still an administrative monster for many small actors.”

Here is the full interview.

  • What is your overall take on the EU simplification decision? Does it truly reduce the burden, or is it mostly cosmetic?

Dr. Steffen Schwarz: My overall view is that the simplification helps at the margins, but it does not solve the core problem. The EUDR remains an administrative monster for many small actors in the coffee chain.

The intention is absolutely right. Nobody in coffee can seriously argue against forest protection. The question is whether the instrument is proportionate and intelligent enough. At the moment, I fear that it mainly simplifies the system for those who already have the structures to deal with it: large importers, large exporters, certification bodies, and companies with compliance departments.

For small roasters, small importers, and direct trade relationships, the fundamental burden remains. Coffee is not only a bulk commodity. Many of the most valuable coffees in Europe come from small farms, old varieties, rare cultivars, agroforestry systems, and micro-lots. These coffees may be fully deforestation-free, but proving that in the required administrative format can become disproportionately expensive.

So yes, simplification is welcome. But if the system still makes it easier to import large, standardized volumes than small, diverse, direct-trade lots, then we have not fixed the real problem.

  • Who benefits the most from this simplification?

The biggest beneficiaries will probably be large companies and low-risk exporting countries with organized documentation systems. They can spread compliance costs over large volumes and integrate the EUDR into existing legal, digital, and certification structures.

Small producers may benefit on paper, especially where simplified declarations or reduced obligations apply. But many smallholders outside the EU will still feel the pressure indirectly. The legal obligation may sit with the European operator, but the demand for geolocation data, legality evidence, and traceability will travel upstream to the farm level.

That is where the danger lies. A small farmer who grows coffee under shade, preserves old varieties, and has never cleared forest may still be excluded if the paperwork is too difficult or too expensive. The system may not intentionally discriminate against smallholders, but its practical effect could do exactly that.

In my view, the real winners are those who can industrialize compliance. The potential losers are those whose strength lies in quality, diversity, and relationship-based trade rather than administrative capacity.

  • Soluble coffee is now fully covered, after being excluded before. How do you see this affecting coffee traders and roasters worldwide?

Dr. Steffen Schwarz: From a regulatory logic, including soluble coffee makes sense. If the aim is to prevent deforestation-linked coffee from entering the European market, then it would be inconsistent to regulate green and roasted coffee but leave soluble coffee outside.

However, soluble coffee is often based on complex, high-volume, multi-origin supply chains. It may involve large blends, several processing stages, and coffee from many farms, regions, or countries. That makes traceability more complicated.

For large soluble coffee manufacturers, this will create additional compliance work, but they are generally better equipped to manage it. For traders supplying the soluble industry, the pressure will increase significantly. They will need cleaner documentation, stronger segregation, and better origin data.

The risk is that soluble coffee supply chains will become more consolidated. Suppliers who cannot provide the required documentation may simply be removed from the chain. Again, the coffee may not necessarily become better or more sustainable. It may simply become easier to document.

Is the global coffee supply chain ready for the December 30, 2026 deadline? If not, which part of the industry will take the biggest hit?

Dr. Steffen Schwarz: No, not fully. Some parts of the industry are ready, especially larger exporters, organized cooperatives, multinational traders, and companies already working with detailed traceability systems. But the global coffee sector as a whole is not ready.

The biggest hit will be taken by small producers, small exporters, small importers, and independent roasters working with direct-trade lots. These actors often have the most transparent human relationships, but not always the administrative infrastructure required by the EUDR.

Geolocation is a good example. In theory, it is a powerful tool. In practice, collecting, verifying, storing, and transmitting accurate plot-level data across thousands of small farms is a major challenge. Keeping the December 2026 deadline means that many supply chains will have to make fast decisions.

The easiest decision will often be to reduce complexity: fewer origins, fewer small suppliers, fewer micro-lots, fewer experimental coffees.

That is my main concern. Europe may end up protecting itself legally, while weakening some of the most meaningful forms of sustainable coffee trade.

The EUDR asks the right moral question: should Europe consume coffee linked to deforestation? Clearly, no. But the next question is just as important: can Europe protect forests without pushing small farmers, old varieties, direct trade, and coffee diversity out of the market?

At present, I am not convinced that we have achieved that balance.

Qahwa World – Episode Two tomorrow with Kim Thompson, Co-Founder of RAW Coffee Company in Dubai.

Read Related stories:

EUDR Simplification: Six Voices from the Coffee Industry Speak

European Commission Simplifies Deforestation Regulation.. What’s New?