Vietnam Targets 31 Million Coffee Bags in 2025/2026 as Farmers Expand Output and Processing Surges

Vietnam forecasts a record 31 million coffee bags in 2025/2026, with robusta dominating production. Exports and domestic consumption rise, while prices and processing investment reshape the sector.

The Vietnam Coffee Annual Report 2025/2026, published by the U.S. Department of Agriculture on May 19, 2025, projects a notable recovery in Vietnam’s coffee sector, with total production expected to reach 31 million 60-kg bags of green bean equivalent. This marks a strong rebound from the previous year’s 29 million bags and reflects both improved weather and stronger farmer investment driven by record prices. Robusta continues to account for the vast majority of production, at an estimated 30 million bags, while arabica holds steady at 1 million bags.

The Central Highlands — including Dak Lak, Lam Dong, Dak Nong, Gia Lai, and Kon Tum — remain the core of Vietnam’s coffee industry, producing over 90% of the country’s output. The combination of volcanic soil, high elevation, and distinct wet-dry seasons creates optimal conditions for robusta cultivation. Despite some local media reports about farmers switching to higher-value crops like durian, official data shows the coffee area expanding, with 730,000 hectares planted in 2024, 92% of which is harvestable.

Farmer investments have been bolstered by global coffee prices that more than doubled over the past year. Domestic robusta prices reached approximately VND 125,000 per kilogram in early 2025 — a 130% increase over 2024 — while average export prices hit $5,630 per ton, up 143% year-on-year. Many producers, anticipating further gains, have been withholding stocks, which caused a 23% drop in exports during the first half of 2024/2025 despite strong global demand. Exporters have shifted toward a just-in-time model, moving away from large-scale stockpiling as capital costs rise.

Vietnam’s coffee exports are expected to rebound to 27 million bags in 2025/2026, up from an estimated 25.8 million in the current year. This includes 23.7 million bags of green coffee and 3.3 million bags of processed products, such as roasted and soluble coffee. Processed coffee continues to gain market share, rising from 8.8% of exports in 2022 to 9.6% in 2024, fueled by growing demand in Asia. Countries like the Philippines, China, and Indonesia are paying higher prices than Europe, with the Philippines paying $4,424/ton, compared to Germany’s $3,390 or Italy’s $3,260.

Soluble and roasted coffee exports are gaining momentum, supported by major factory investments. Nestlé recently invested nearly $75 million to expand its Dong Nai facility — producing for over 35 global markets — bringing its total Vietnam investment to nearly $1 billion. Local companies are also scaling up: Trung Nguyen is building a $75 million processing plant in Dak Lak, and Highlands Coffee opened a new $20 million facility with a processing capacity of 75,000 tons per year.

Domestic consumption is also growing fast. Forecasts for 2025/2026 suggest 4.9 million bags will be consumed locally, up from 4 million this year. This growth is driven by a rising middle class, recovering tourism, and a boom in café culture. Vietnam now has over 500,000 cafés, from traditional street vendors to modern coffee chains. Takeaway and home-brewed coffee are also gaining popularity among younger consumers.

Meanwhile, Vietnam is preparing for the EU Deforestation Regulation (EUDR), which takes effect in 2026. With 41% of exports destined for the EU, compliance is critical. Two Vietnamese companies have already met the requirements — including Simexco Daklak with its traceability system. The Ministry of Agriculture and Environment is building regional monitoring systems covering 136,000 hectares, developing a national coffee database to support certifications like Rainforest Alliance, 4C, and Fair Trade.

While weather conditions in early 2025 were favorable — with higher rainfall than 2024 — concerns remain about drought risks in April and May. Nonetheless, the overall forecast suggests stable and improving growing conditions. Vietnam’s top research institution, WASI, continues to supply 4–5 million coffee seedlings per year for new and replanted farms, aiming to raise productivity and climate resilience.

Despite the high prices, coffee yield improvements remain critical. Robusta yields are forecast at 2.90 metric tons per hectare, slightly up from 2.73 in 2024. Arabica yields remain modest and will require stronger investment and varietal development. The Ministry’s specialty coffee development plan aims to expand specialty coffee to 19,000 hectares by 2030, signaling future diversification in quality segments.

Vietnam’s coffee imports are projected to decline slightly to 800,000 bags in 2025/2026 due to higher domestic supply, but sustained demand for arabica beans and processing inputs will keep import levels stable.

As Vietnam enters the 2025/2026 marketing year, it does so with strong fundamentals: record prices, recovering export flows, fast-growing domestic demand, and a strategic shift toward higher-value products and traceable supply chains. However, exporters must remain agile amid price volatility and regulatory pressure, especially as Europe and Asia demand more than just beans — they want quality, transparency, and resilience.
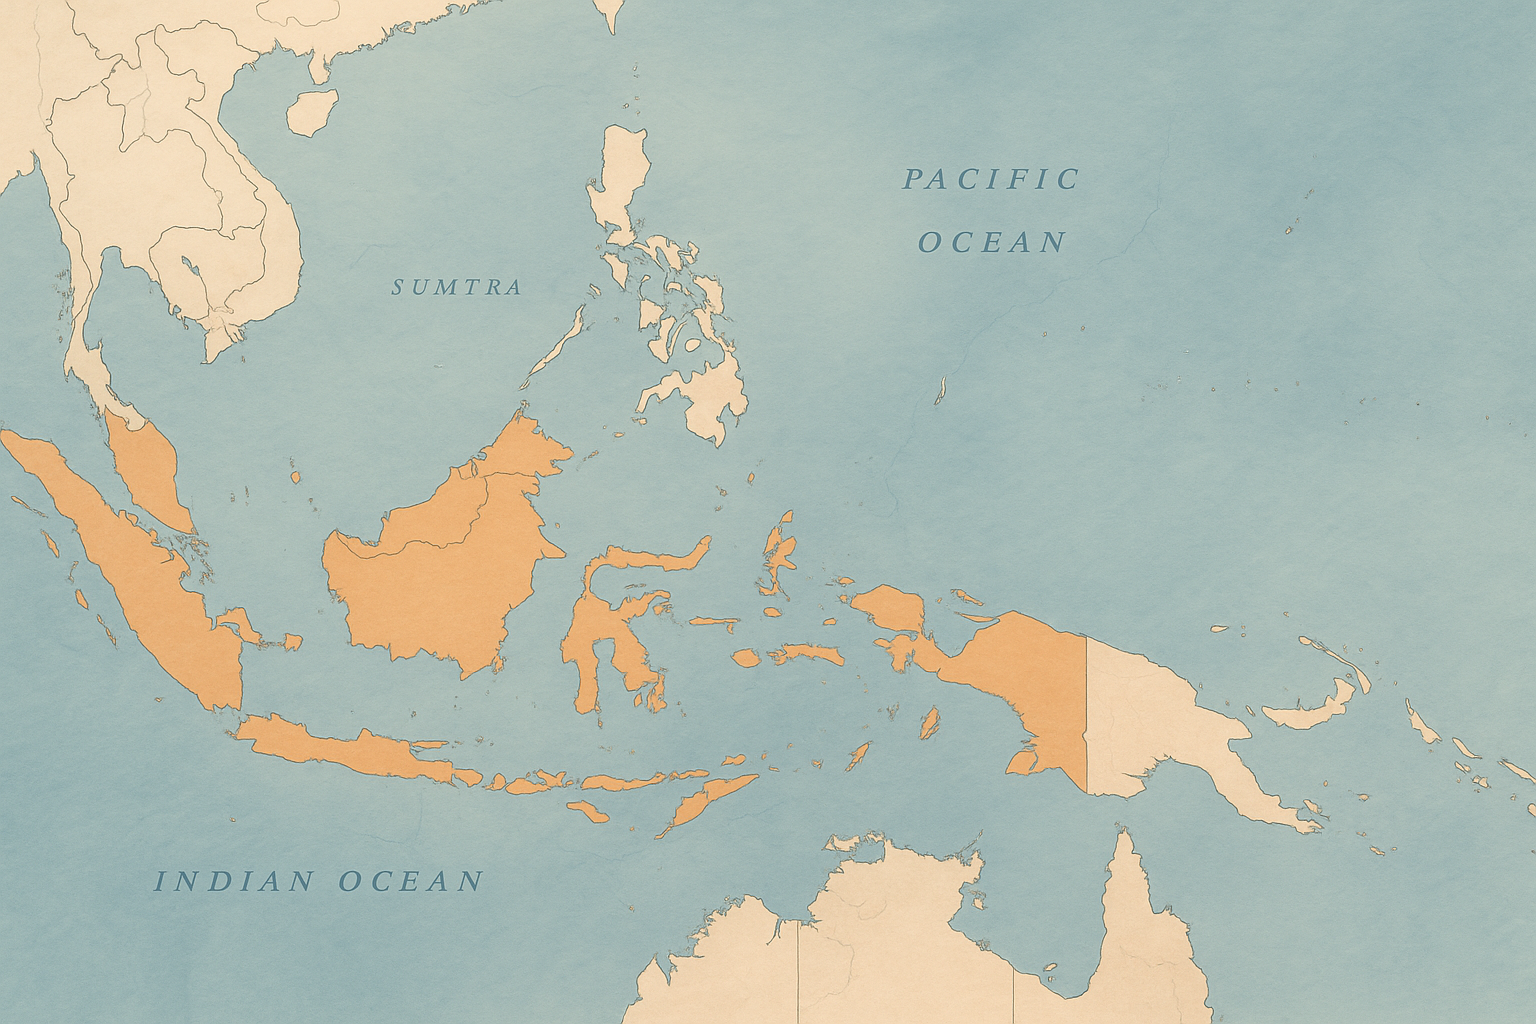
Indonesia’s Coffee Sector Eyes Modest Growth in 2025/2026 as Weather Improves and Inputs Rise

Indonesia projects 5% growth in coffee production for 2025/2026, reaching 11.3 million bags. Robusta dominates output, exports rise 7%, but domestic consumption slows amid weak spending.

According to the Coffee Annual Report – Indonesia 2025/2026, published by the U.S. Department of Agriculture on May 19, 2025, Indonesia’s coffee production is forecast to reach 11.3 million 60-kg bags, marking a 5% increase over the previous year. This growth is attributed to favorable weather during the flowering season and improved farm inputs. However, despite higher production and a 7% rise in exports, domestic consumption remains sluggish due to weak middle-class spending.

Indonesia’s total planted area remains unchanged at 1.2 million hectares, as no major expansion or replanting initiatives have been introduced in recent years. Smallholder plantations—typically between one and two hectares—continue to dominate the sector, accounting for 98% of total area. Larger estates, managed by private and state-owned companies, are located primarily in Sulawesi, Sumatra, and East Java.

The island of Sumatra remains the heart of Indonesia’s coffee belt, producing 70–75% of the country’s total output, with the majority being robusta from provinces like South Sumatra, Lampung, and Bengkulu. Arabica production is centered in North Sumatra, as well as high-altitude zones in Java, Sulawesi, and Papua.

In 2025/2026, robusta production is expected to increase by 500,000 bags, reaching 9.8 million bags, driven by improved rainfall and increased fertilizer use. Farmers in Jambi and South Sumatra began harvesting in late April 2025, with peak harvest expected between June and July. Meanwhile, arabica production is projected to reach 1.45 million bags, showing a slight increase. Arabica is harvested twice annually—in April/May and again in September/October.

Improved margins from rising prices over the past two years have motivated smallholders to rejuvenate neglected plots and adopt better farm practices. In regions like Lampung, fertilizers and pesticides are often accessed on credit through village-level aggregators. Family labor is commonly used, with rotational harvesting labor helping reduce overall costs.

Despite this, yields—especially for robusta—remain below one ton per hectare, constrained by inconsistent seed quality and a limited supply of improved planting material. Local government support for better seedlings and training programs remains geographically limited.

Domestic consumption in 2025/2026 is forecast at 4.81 million bags, up slightly by just 10,000 bags. While roasteries and processors continue to show demand, many were pressured by rising input costs and subdued consumer purchasing power during 2024/2025. Lower- to mid-grade coffee products are expected to perform better, particularly among working-class and Gen Z consumers in urban areas. Street vendors and hawkers selling affordable coffee maintain steady sales, while high-end cafés remain popular with younger and higher-income demographics.

Ready-to-drink (RTD) coffee sales continue to grow—albeit at a slower pace. In 2025, RTD volume is projected to increase by 3%, the slowest rate since the pandemic. These products, often priced more accessibly than those at branded coffee chains, have become increasingly popular in convenience stores and vending machines.

On the trade front, green bean exports are forecast to increase to 6.5 million bags, up from 6.1 million last year. The growth comes from improved availability following the production rebound. However, uncertainty surrounds shipments to the United States, which had resumed during a temporary tariff pause but may face disruption after July 2025. Exporters are bracing for the expiration of a 90-day suspension on a reciprocal 32% tariff, and are actively redirecting shipments to alternative destinations such as ASEAN countries, Japan, the EU, and the Middle East.

In 2024/2025, exports to the U.S. reached 726,000 bags, a 23% increase over the prior year. The EU remained the top buyer, driven by demand from Belgium and Germany, with over 1.4 million bags shipped between March 2024 and February 2025—double the volume from the previous year. However, the upcoming EU Deforestation Regulation (EUDR) poses new compliance challenges. Exporters are now preparing to meet stricter traceability and sustainability requirements, including the need to provide due diligence statements certifying that coffee is deforestation-free.

Green bean imports, mostly of robusta from Vietnam and arabica from Brazil, are projected to fall to 400,000 bags in 2025/2026 as local availability improves. During the 2024 period, imports from Vietnam dropped to 490,000 bags, while Brazilian imports stood at 180,000 bags.

As for pricing, domestic bean prices have soared. Robusta spot prices in Lampung exceeded IDR 222,000/kg in early 2025, up sharply from IDR 55,000–70,000/kg the year before. Arabica spot prices in Medan surpassed IDR 213,000/kg in April and May. This price spike is tied to global market trends and lower stocks in late 2024, when many farmers held back supplies in anticipation of continued increases.

Despite these high prices, the use of high-yield, disease-resistant seedlings remains limited, and yield gaps persist across regions. Heavy rains and strong winds during cherry development continue to pose risks, especially for arabica grown in highland areas. However, weather during the flowering season was favorable, particularly from October to November 2024, boosting optimism for the current cycle.

As the Indonesian coffee sector moves into the 2025/2026 cycle, modest production gains, a resilient robusta base, and improved inputs set a stable foundation. But policy uncertainty, export redirection, price volatility, and looming EU regulations demand adaptive strategies. Strengthening farmer support programs, modernizing planting systems, and expanding traceability infrastructure will be key to sustaining momentum in the seasons ahead.

Brazil Heads Toward a Historic Coffee Revenue Season Despite Arabica Decline and Slowing Exports

  • Brazil forecasts 65 million bags of coffee in 2025/2026. Robusta expands while arabica falls. Revenue hits all-time high amid supply bottlenecks and global price surges.

The “Coffee Annual Report – Brazil 2025/2026,” published by the U.S. Department of Agriculture on May 15, 2025, indicates that Brazil, the world’s largest coffee producer, is set for a season with an estimated 65 million 60-kg bags of green coffee. This figure reflects relative stability in overall output compared to the previous year, but it conceals sharp contrasts between arabica and robusta performance. Arabica is expected to decline by 6.4% due to heat stress, drought, and its biennial cycle, while robusta continues to expand rapidly—up 15%—driven by improved weather and greater investment in irrigation and mechanization.

Key arabica-producing states like Minas Gerais and São Paulo experienced severe climatic stress during flowering. Minas Gerais endured over 200 days without rain, reducing blossom intensity and bean density, while São Paulo also reported dry weather at a critical phase. In contrast, states like Espírito Santo and Bahia benefited from more regular rainfall and improved irrigation systems, allowing them to sustain arabica yields and significantly boost robusta production. Espírito Santo alone now produces about 70% of Brazil’s robusta output, and Bahia is expected to increase its volume by 11%. Meanwhile, Rondônia reported delays in cherry maturation, but quality remains stable due to late but intense rains.

Despite the overall production rebound, coffee exports are forecast to decline by 5.6% to 41.75 million bags in the upcoming marketing year, affected by reduced availability, port congestion, and the return of strong competition from Vietnam and Indonesia. However, Brazil is capitalizing on favorable tariff structures, particularly in the United States, where Brazilian robusta enjoys a much lower duty than imports from some Asian countries. This opens new opportunities for robusta exports even as arabica shipments face mounting pressure.

Coffee prices have reached record highs in Brazil. In February 2025, arabica was priced at BRL 2,769.45 per 60-kg bag, while robusta reached BRL 2,102.12 in January. These price surges, driven by global supply disruptions and strong demand, have pushed the total value of Brazil’s coffee sector to BRL 126.7 billion—up 57% from last year and the highest in history. Arabica represents 71% of this revenue, while robusta contributes 29%.

Domestic coffee consumption in Brazil reached 22.28 million bags during the current season, showing a slight increase. However, per capita consumption declined to 5.01 kg due to population growth. The sharp rise in roasted coffee prices prompted some consumers to switch to instant coffee, which grew by 6% in the first quarter of 2025.

Soluble coffee exports also performed well. Spray-dried coffee accounted for 71.5% of the category, while freeze-dried shipments rose 19%. Premium coffee exports grew by 31%, particularly to the United States, Germany, Belgium, the Netherlands, and Japan.

Nonetheless, port infrastructure remains a major bottleneck. It is estimated that around 638,000 bags could not be exported due to port delays, resulting in losses exceeding BRL 1.5 billion. Brazil’s ports suffer from insufficient berth space and cannot accommodate large vessels, forcing the government to invest nearly USD 800 million in infrastructure upgrades in 2025.

To support growers, the government maintained minimum guaranteed prices at BRL 662.04 for arabica and BRL 498.79 for robusta. In addition, the National Coffee Fund (FUNCAFE) allocated BRL 6.88 billion to finance production, marketing, and weather damage recovery. Starting in 2026, Brazil will implement a broad tax reform that simplifies VAT and exempts basic food items, including coffee.

On the sustainability front, Brazil continues to strengthen its environmental and social compliance. According to the report, 97% of producers follow ESG-aligned practices, and the national digital traceability platform “Cafés do Brasil” is helping exporters meet the requirements of new EU regulations on deforestation-free supply chains.

While arabica faces a difficult season due to climatic instability, robusta is emerging as a strategic pillar for Brazil’s coffee future. With record-breaking revenues, growing export diversification, and strengthened sustainability credentials, Brazil remains a global coffee powerhouse—though continued improvements in infrastructure and support for smallholders will be critical to sustaining this momentum.

Strong Coffee Outlook for Nicaragua in 2025/2026 Amid High Prices and Ongoing Challenges

  • Nicaragua expects a strong coffee harvest of 2.58 million bags in 2025/2026, supported by high prices and improved rainfall, despite persistent credit, labor, and export challenges.

Nicaragua is preparing for a strong coffee season in 2025/2026, with total production forecast at 2.58 million 60-kg bags, matching historical averages. The optimism among producers is driven by higher international prices—averaging above $280 per bag in early 2025—which have encouraged farmers to invest in fertilizers and field maintenance. Expectations for a more balanced rainy season under ENSO-neutral conditions are also contributing to a positive outlook. However, structural issues such as limited access to long-term credit, severe labor shortages, and export bottlenecks continue to cloud the sector’s long-term performance.

The previous marketing year, 2024/2025, marked a recovery for Nicaraguan coffee production, which rose to 2.56 million bags following a 10% drop the year before due to El Niño weather disruptions. While the second half of 2024 brought favorable rainfall and supported flowering, extended rains into December and January complicated the harvest and drying process. These delays, coupled with a compressed ripening period across different altitudes, worsened labor shortages and drove up wages. Many pickers demanded double their usual pay, leading to higher production costs and, in some regions, compromised bean quality.

Adding to the uncertainty, one of Nicaragua’s largest exporters filed for bankruptcy just before the 2024 harvest, causing disruptions in the supply chain and reducing market confidence. At the same time, a sharp price surge in late 2024 created liquidity issues for buyers and delayed shipments, particularly as Central American ports struggled with congestion and slow processing.

Despite these obstacles, coffee producers remain hopeful. Nicaraguan coffee continues to be in strong global demand, praised for its smooth and consistent flavor. Many cooperatives and exporters are certified under programs such as Rainforest Alliance and Fair Trade, allowing them to fetch above-average market prices. With such demand and premium positioning, farmers are more willing to invest in crop maintenance.

The total planted area for 2025/2026 is expected to remain at 143,000 hectares, with 141,000 hectares harvested. However, continued outbound migration over the last five years has reduced the available workforce, especially in rural areas, limiting the ability to expand or renew plantations. Since the coffee leaf rust outbreak in 2013, farmers have replanted approximately 20,000 hectares—about 14% of the total arabica area—but this pace is still below the ideal renewal rate. Experts recommend renewing at least 5% of coffee land annually to maintain long-term productivity, but most farms only replant when older trees die or become infected.

Arabica coffee dominates Nicaragua’s production, making up over 95% of output. The most common variety remains Caturra, followed by Bourbon, Paca, Catuai, Catimore, Maragogype, and Pacamara. Meanwhile, robusta production has remained stagnant, contributing about 160,000 bags annually. With the 2023 closure of Mercon, a major promoter of robusta in Nicaragua, some farmers have abandoned expansion plans in lower-altitude regions where robusta is suitable. Today, only about 7,000 hectares are planted with robusta, mostly in the Southern Caribbean Coast near Nueva Guinea.

Nicaragua’s average yield for arabica coffee is projected to remain at 18 bags per hectare for the upcoming season, assuming consistent rainfall and good farming practices. This matches the improved yield seen in 2024/2025 after the El Niño-driven decline the year before. Ongoing efforts from international projects like MOCCA, led by the USDA and World Coffee Research, have improved seed quality, certified nurseries, and expanded access to higher-yielding varieties like Marsellesa, Parainema, and IH Café 90. However, limited financing remains a major barrier to widespread adoption of these innovations.

Within the local market, per capita coffee consumption is forecast to remain at 1.5 kilograms in 2025/2026. However, a growing trend is emerging, especially among young consumers in urban areas, who are increasingly choosing high-quality roasted coffee. This has led to a boom in coffee shops in cities like Managua, offering everything from espresso to cold brew. While this shift reflects a modernization of coffee culture, broader consumption growth is held back by economic pressures, rising food costs, and continued emigration.

On the export front, Nicaragua is expected to ship 2.42 million bags in 2025/2026, a modest recovery after a 15% drop in 2023/2024. The United States remains Nicaragua’s top market, accounting for about 50% of all exports, particularly high-quality arabica beans favored by specialty roasters and cafés. The European Union is the second-largest destination, taking in around 30% of exports, especially organic and certified coffees which remain in strong demand.

However, global market uncertainty, weather concerns in Brazil and Vietnam, and supply chain stress are driving prices up, creating both opportunities and challenges for Nicaraguan exporters. High prices improve margins but also increase volatility, and delays at regional ports may continue to affect shipments in the coming season.

Nicaragua’s coffee sector, which employs more than 330,000 people across the value chain, remains one of the country’s most vital economic engines. Still, the road ahead will require coordinated efforts to overcome financial constraints, modernize infrastructure, and stabilize labor supply if producers are to maintain their position in the highly competitive global coffee market.

Colombia’s Coffee Output to Drop 5.3% in 2025/26 as Heavy Rains and High Prices Stall Growth

Colombia’s coffee production is forecast to fall by 5.3% in 2025/2026 due to heavy rains and record-high prices. Exports and domestic supply face new challenges.

Colombia, the third-largest coffee producer in the world, is expected to face a significant setback in the 2025/2026 marketing year as production is forecast to drop by 5.3%, reaching just 12.5 million 60-kg bags of green bean equivalent. The decrease, outlined in the USDA Coffee Annual Report for May 2025, is attributed to excessive rainfall that disrupted flowering, along with a sustained period of high coffee prices that has discouraged producers from investing in renovation and replanting. This downturn comes shortly after a modest recovery in the previous year, which had been driven by favorable El Niño conditions.

While El Niño raised temperatures and improved soil moisture, boosting production by 3.5% to 13.2 million bags in 2024/2025, that momentum was short-lived. In early 2025, heavy rains interrupted the flowering phase of coffee trees, setting the stage for a weaker harvest starting in October. Although the La Niña phenomenon is currently weakening and is expected to shift to neutral by late 2025, the damage to flowering has already impacted production forecasts for the start of the new season.

Despite strong prices—reaching COP 3.12 million per 125-kg bag by February 2025, a 70% increase since January 2024—producers are not reinvesting as expected. Higher domestic prices, while beneficial in the short term, have not offset the rising cost of production caused by wage increases and labor shortages, especially in rural coffee-growing areas. Even as fertilizer prices ease, overall profitability remains squeezed, prompting many growers to delay farm renovations.

A key strength in Colombia’s coffee sector lies in its specialty segment. Around 40% of national output qualifies as specialty-grade coffee certified by programs like Rainforest Alliance, Fairtrade, and Bird Friendly. These certifications allow smallholders—who produce 60% of the country’s coffee on plots under 5 hectares—to receive premium prices that help them stay afloat in challenging market conditions. Colombia has also made significant progress in upgrading its farms, with 87% of coffee-growing areas now planted with rust-resistant varieties, and average tree density reaching a record 5,340 trees per hectare. In late 2024, Colombia’s coffee research center Cenicafe introduced a new variety, Castillo 2.0, which is more resistant to disease and climate stress. However, it remains too early to gauge adoption among farmers.

Coffee exports are expected to fall to 11.8 million bags in 2025/2026—a 4.1% decline—primarily due to the drop in production. The United States remains Colombia’s top export market, absorbing over 40% of shipments, followed by the European Union, Canada, and Japan. Notably, exports to the U.S. are growing again after five years of decline, despite the recent imposition of a 10% tariff under Executive Order 14257. Analysts do not expect the tariff to have a major impact, as competing producers face similar conditions. In a bid to boost retail presence, Procafecol, which owns the Juan Valdez brand, has partnered with Green Coffee Company Holdings to expand roasted coffee sales in supermarkets and institutional outlets across North America.

Domestically, coffee consumption is projected to remain unchanged at 2.2 million bags through 2026. Although Colombia’s economy is expected to grow by 2.6% in 2025 and inflation is forecast to ease to 4.1%, high coffee prices are suppressing consumption growth. Soluble and low-cost blends still dominate local preferences, and with per capita consumption at just 3.08 kg, Colombia trails behind other Latin American coffee producers where annual consumption exceeds 6 kg per person. Fedecafe continues its efforts to shift this dynamic through its long-running national campaign “Busca el Triángulo de la Calidad – Café de Colombia,” which certifies products made from 100% Colombian beans. As of this year, over 850 brands carry the trademark triangle.

To meet internal demand amid falling production, coffee imports are set to rise by 34% to 1.5 million bags. These imports, mainly from Brazil, Peru, and Ecuador, are used for soluble and lower-cost blends. The bulk of imports—around 70%—are unroasted green beans, while soluble coffee accounts for 28.5%, and roasted products make up the remaining fraction.

Compliance with EU Deforestation Law

A major concern for Colombia’s coffee exporters is the European Union’s Regulation 2023/1115, which mandates deforestation-free sourcing for coffee and other commodities. With over 20% of Colombia’s coffee exports destined for Europe, compliance is critical. The deadline is December 30, 2025 for large companies and June 2026 for smallholders. To prepare producers, Fedecafe has launched a national traceability platform and is offering legal and technical training to help farms meet the new standards.

Ending stocks for the upcoming season are forecast to decline slightly to 458,000 bags. Meanwhile, Colombia’s Coffee Price Stabilization Fund—intended to compensate growers when prices fall below production costs—has not yet been triggered due to persistently strong market rates. The fund currently holds approximately COP 370 billion (about $95 million USD) in reserve. If triggered, it could help stabilize income for smallholders in future downturns.

Colombia’s coffee sector remains a complex mix of resilience and vulnerability. The country’s leadership in specialty coffee and its export partnerships continue to open global opportunities. However, producers face mounting uncertainty driven by erratic weather, labor shortages, global tariffs, and regulatory shifts. As the 2025/2026 season approaches, the industry must strike a balance between short-term gains and long-term sustainability.

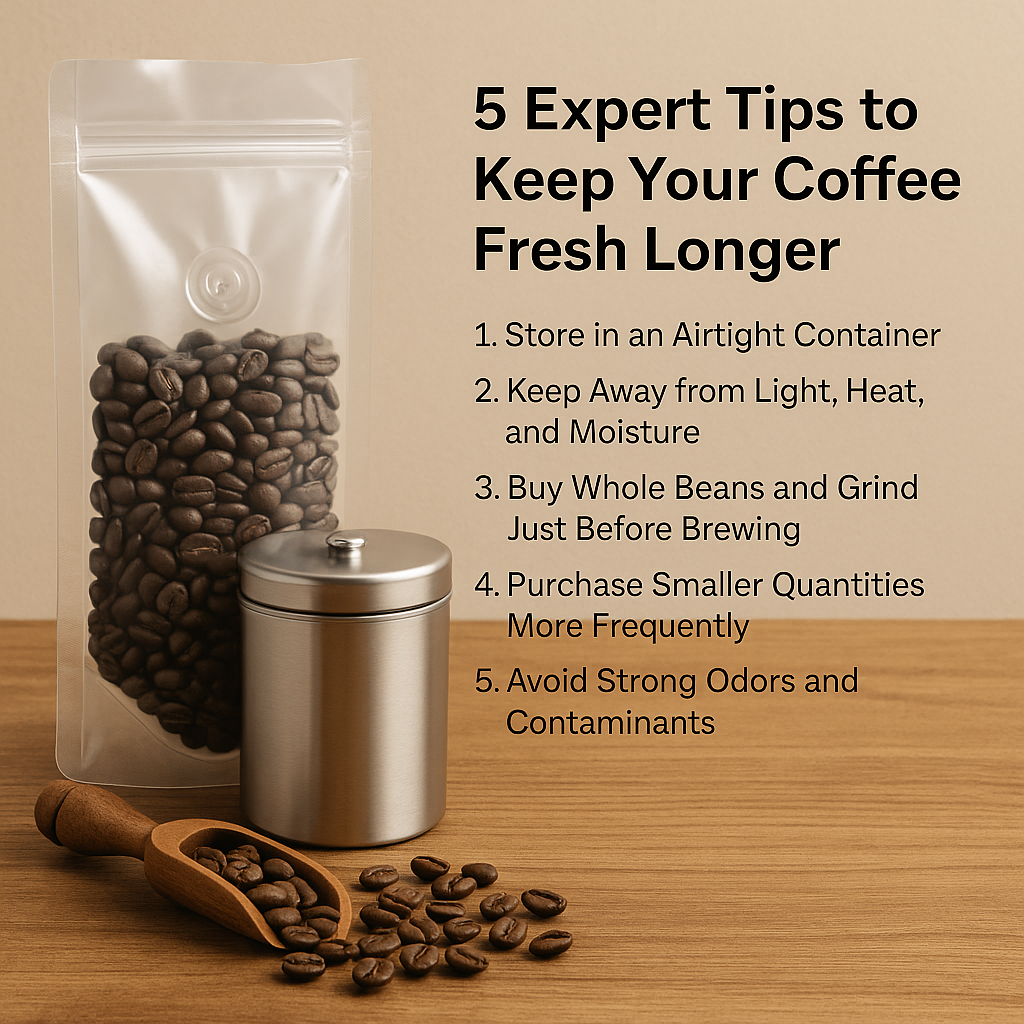
5 Expert Tips to Keep Your Coffee Fresh Longer

Extend the life of your coffee with these barista-approved storage techniques. Learn five essential ways to keep your beans fresh, aromatic, and flavorful.

Keeping your coffee fresh is the key to a consistently exceptional cup. Whether you’re a home brewer or a seasoned enthusiast, understanding how to store your beans properly can make all the difference. As a senior barista and coffee expert, I’ve tested countless storage methods—and these are the top five proven ways to preserve the flavor, aroma, and vibrancy of your coffee.

1. Store in an Airtight Container

Oxygen is coffee’s biggest enemy. Once exposed to air, beans quickly lose their aromatic oils and flavor. Use a sealed container with a one-way valve to store your coffee. Press out the air if your bag has a resealable top, or use a vacuum-sealed stainless steel or ceramic canister to keep oxygen out and freshness in.

2. Keep Away from Light, Heat, and Moisture

Coffee should never be stored in the fridge or freezer. Cold environments introduce unwanted moisture, while surrounding foods may affect your coffee’s taste. Instead, store your beans in a cool, dry, and dark place—like a pantry or cupboard—away from heat sources and direct sunlight.

3. Buy Whole Beans and Grind Just Before Brewing

Pre-ground coffee loses its freshness faster due to increased surface exposure. Whole beans stay fresher much longer, especially when stored properly. For the best cup, grind only the amount you need right before brewing to lock in flavor and adjust the grind size to your brewing method.

4. Purchase Smaller Quantities More Frequently

While buying in bulk might seem economical, it often leads to stale beans. For peak freshness, buy just enough coffee to last 2–3 weeks. Choose roasters that print roast dates on their bags, and avoid brands that only list expiry dates.

5. Avoid Strong Odors and Contaminants

Coffee is porous and can easily absorb odors from its environment. Store your beans away from spices, cleaning products, or any items with strong scents. Always use a clean, odor-neutral container made of non-porous material like glass or metal.

Final Note from the Barista:

Great coffee begins long before it hits your cup. How you store it matters just as much as how you brew it. These simple practices will help you get the most out of every bean, preserve your coffee’s natural qualities, and enhance your daily ritual.

Coffee Prices Drop Sharply as Global Supply Improves and Demand Concerns Mount

Global coffee prices fell sharply on Friday, driven by signs of improving supply across major producing regions and growing concerns about weakening global demand. July arabica coffee futures (KCN25) dropped by -9.35 cents (-2.49%), while July ICE robusta coffee (RMN25) declined -106 USD (-2.13%), with robusta hitting a five-week low.

Market analysts attribute the retreat to stronger-than-expected harvest progress in Brazil and rising global inventories, which have eased concerns about tight supply that dominated earlier this year.

Brazil Coffee Sales Near Completion

One of the main bearish drivers this week was a report from Safras & Mercado, which confirmed that Brazil’s 2024/25 coffee crop sales were 97% complete as of May 13, exceeding last year’s pace of 94% for the same period. This signals strong producer participation and readiness to sell, easing pressure on supply pipelines.

Brazil remains the world’s largest coffee producer, and any change in its output or export behavior significantly impacts global pricing trends.

Inventories Surge in Both Arabica and Robusta

Coffee inventory levels monitored by the Intercontinental Exchange (ICE) continue to rise, reinforcing bearish sentiment. Robusta inventories climbed to a 7.5-month high, reaching 4,890 lots, while arabica inventories rose to 851,169 bags, marking a three-month peak.

These stock builds suggest supply is outpacing current demand, especially as key consumer-facing companies issue warnings about the effect of tariffs on their coffee costs.

Demand Pressured by Import Tariffs and Consumer Sentiment

Major global importers such as Starbucks, Hershey, and Mondelez International have raised concerns over the U.S. baseline 10% import tariff, which is expected to increase consumer prices and potentially suppress sales volumes.

As inflationary pressure persists, especially in developed markets, coffee consumption growth may stagnate—particularly in the premium and specialty segments where price elasticity is higher.

USDA, Conab, and Safras Raise Production Estimates

Fresh production forecasts have only added to the pressure. Brazil’s official crop forecasting agency Conab revised its estimate for 2025 coffee production to 55.7 million bags, up from 51.81 million in January. Safras & Mercado also raised its Brazil production outlook to 65.51 million bags for 2025/26, compared to the earlier 62.45 million bags estimate.

Meanwhile, the USDA has forecast that Honduras, Central America’s top coffee grower, will increase production by 5.1% year-on-year, reaching 5.8 million bags in the 2025/26 cycle.

Arabica Prices Find Temporary Support from Weather and Exports

Despite the broader bearish outlook, some short-term support for arabica prices came from lower-than-average rainfall in Minas Gerais, Brazil’s key arabica-producing region. Somar Meteorologia reported that only 0.8 mm of rain fell in the week ending May 10—just 16% of the historical average, potentially affecting bean development.

In parallel, Cecafé, Brazil’s coffee exporters council, revealed that April green coffee exports declined by -28% year-over-year to 3.05 million bags. Cumulative exports for the January–April period also dropped -15.5% y/y, signaling possible shipping delays or logistical challenges.

Vietnam Robusta Output Remains a Concern

The robusta segment, although weakened this week, is still underpinned by structural tightness. Vietnam, the world’s largest robusta producer, has faced weather-related production issues. The Vietnam Coffee and Cocoa Association recently revised its 2024/25 crop forecast down to 26.5 million bags, a sharp drop from the prior 28 million estimate.

Earlier data from the Vietnam General Statistics Office showed that 2024 exports dropped -17.1% y/y to 1.35 million metric tons, while 2025 exports from January through April also fell -9.8% y/y, totaling 663,000 MT. These figures point to continued output stress due to prolonged drought conditions.

Mixed Signals from USDA’s Global Coffee Outlook

The USDA’s biannual report, issued in December, painted a mixed picture for the global coffee outlook:

  • 2024/25 world coffee production is forecast to increase +4.0% to 174.86 million bags, with arabica up 1.5% and robusta up 7.5%.

  • However, ending stocks are expected to drop -6.6% to 20.87 million bags, marking the lowest level in 25 years, which could still pose upside risk if demand strengthens unexpectedly.

The USDA also expects Brazil’s inventories to decline -26% y/y to 1.2 million bags by the end of the 2024/25 season, further complicating the supply-demand picture.

Volcafe Predicts Deficit in Arabica for 5th Straight Year

Adding to the complexity, coffee trader Volcafe slashed its 2025/26 forecast for Brazil arabica output by 11 million bags, down to 34.4 million bags, citing drought-related damage. The firm predicts a global arabica deficit of -8.5 million bags, the fifth consecutive year of shortfall, which could provide long-term bullish momentum if demand recovers.

Conclusion

Coffee prices are currently in retreat, as improving supply conditions in Brazil and rising global inventories weigh on market sentiment. However, persistent structural concerns—especially in the robusta segment due to Vietnam’s drought—and the long-term arabica deficit predicted by Volcafe hint that this bearish phase may not last.

Market participants are closely watching upcoming harvest reports, export volumes, and global economic data to gauge where prices may head next. For now, however, the coffee market is leaning toward oversupply, which is translating into pressure on futures contracts.

Cocoa Prices Surge to Multi-Month Highs on West African Weather Concerns and Supply Woes

Cocoa futures soared on Friday, driven by worsening weather conditions in West Africa and mounting fears over global supply. July ICE New York cocoa closed up by +6.25%, hitting a 3.25-month high, while July ICE London cocoa gained +5.24%, reaching a 3-month peak.

Drought Persists in Ghana and Ivory Coast Despite Rainfall

According to the African Flood and Drought Monitor, more than one-third of Ghana and Ivory Coast, the world’s two largest cocoa producers, remains under drought stress despite recent rains. This prolonged dry weather continues to threaten yields, particularly for the current mid-crop harvest in Ivory Coast.

Mid-Crop Quality Issues Raise Alarm Among Processors

Concerns over bean quality are also fueling the rally. Ivory Coast cocoa processors report that 5% to 6% of beans in each truckload are substandard—far higher than the typical 1% defect rate during the main harvest. Several shipments have been rejected, adding further strain to the supply chain.

Analysts at Rabobank link the drop in quality to delayed rainfall, which stunted pod development. The Ivory Coast’s mid-crop harvest, which runs from April to September, is estimated at 400,000 metric tons, a 9% decline from last year’s 440,000 MT.

Export Pace Slows in Ivory Coast

Although exports from Ivory Coast between October 1 and May 11 rose +11.4% year-over-year to 1.56 million metric tons (MMT), the pace has slowed significantly compared to the +35% surge recorded in December. This deceleration adds to concerns over future supply tightness.

Inventory Rebound May Cap Price Rally

On the other hand, cocoa inventories are rebounding. ICE-monitored cocoa stocks at U.S. ports reached 2.15 million bags on Friday—a 7.5-month high, after falling to a 21-year low in January. This inventory build could limit further price spikes in the short term.

Rising Costs Threaten Consumer Demand

Global chocolate demand is facing headwinds as cocoa prices continue to rise. Major confectionery companies are already warning of higher prices and reduced consumer spending:

  • Barry Callebaut AG, one of the world’s largest chocolate manufacturers, recently cut its full-year sales guidance, citing high cocoa prices and tariff uncertainty.

  • Hershey Co. reported a 14% decline in Q1 sales and forecasted an additional $15–$20 million in tariff-related costs in Q2, which could further raise chocolate prices.

  • Mondelez International also posted disappointing Q1 results and noted that consumers are cutting back on snack spending amid economic pressure and expensive cocoa products.

Demand Side Still Shows Resilience

Despite pricing concerns, Q1 cocoa grindings — a key indicator of global demand — outperformed expectations:

  • North America: -2.5% YoY to 110,278 MT (vs. -5% expected)

  • Europe: -3.7% YoY to 353,522 MT (vs. -5% expected)

  • Asia: -3.4% YoY to 213,898 MT (vs. -5% expected)

These smaller-than-expected declines suggest that global demand, while softening, remains relatively stable.

Ghana’s 2024/25 Forecast Cut Again

Cocoa prices also found support from Ghana, the second-largest producer globally, where the Ghana Cocoa Board (Cocobod) reduced its 2024/25 harvest forecast for the second time to 617,500 MT, down 5% from earlier estimates.

Global Deficit Reaches Historic Levels

The International Cocoa Organization (ICCO) reported in February that the 2023/24 global cocoa deficit reached -441,000 MT, marking the largest shortfall in over 60 years. Cocoa production dropped -13.1% YoY to 4.38 MMT, and the global stocks-to-grindings ratio fell to 27%, a 46-year low.

However, ICCO projects a turnaround in 2024/25, forecasting a global surplus of 142,000 MT — the first in four years — alongside a 7.8% increase in global production to 4.84 MMT.

Conclusion:
Cocoa markets are at a critical juncture. Weather-driven supply risks, mid-crop quality concerns, and slowing exports are driving prices higher, even as inventories rise and consumer demand shows signs of strain. With the global cocoa market experiencing its worst deficit in decades, the coming months will be crucial in determining whether a projected 2024/25 surplus can stabilize the market — or if further volatility lies ahead.

Rising Production and Exports Put Kenya Back on the Global Coffee Map

Dubai – Qahwa World

Kenya is witnessing a strong rebound in its coffee sector, with production forecast to grow by 13.3% in the 2025/26 marketing year, reaching 850,000 sixty-kilogram bags. This recovery is driven by high global prices, government reforms, and farmer support programs. Exports are also projected to rise by 10%, while domestic consumption is expected to increase by 6.9%. With these promising indicators, Kenya is reclaiming its place among the world’s top Arabica coffee producers.

According to the USDA’s Coffee Annual Report (May 2025), Kenya’s coffee production is forecast to increase from 750,000 bags in 2024/25 to 850,000 bags in 2025/26. Farmers have responded to favorable prices with improved agricultural practices—applying more fertilizer, controlling pests more effectively, and capitalizing on Arabica’s natural biennial production peak.

In February 2025, the Nairobi Coffee Exchange (NCE) recorded a historic high of $363 per 50-kg bag, up from $254 in October 2024. Although a slight price correction is expected in the second half of the year, prices remain favorable and have reinvigorated investment in farms.

Slight Expansion in Planted Area

While harvested area is expected to remain at 105,000 hectares, planted area will increase slightly as the Kenyan government rolls out its Coffee Expansion Program in both traditional and new growing regions across Central, Eastern, and Rift Valley Kenya. The program includes subsidized seedlings, supported by county-level grants and expanded production at the Coffee Research Institute to meet increased demand.

Urbanization Slows, Coffee Area Stabilizes

Between 2020 and 2024, coffee area declined from 112,000 to 105,000 hectares due to urban development, particularly around Nairobi, Kiambu, and Nyeri. However, this trend has slowed, thanks to a stagnating real estate market, offering the sector a chance to stabilize.

Marketing Reforms and Structural Overhaul

Roughly 80% of Kenya’s coffee is sold through producer cooperatives, while the remaining volume is marketed by private farms and estates. The Nairobi Coffee Exchange remains the country’s primary marketplace, handling over 90% of coffee sales.

Since 2023, Kenya has implemented significant reforms in marketing and regulation. The NCE is now under the Capital Markets Authority, which licenses brokers responsible for classification and auction procedures. There are currently 15 licensed brokers. Additionally, licensing of millers was decentralized to county governments.

A pending Coffee Bill in Parliament seeks to formalize these changes by creating a new Coffee Board of Kenya and an independent Coffee Research and Training Institute, to be funded through a coffee sales levy.

Exports Rising but Facing EU Deforestation Law

Coffee exports are expected to grow by 10% to 840,000 bags in 2025/26, up from 763,000 bags the previous year. Green beans dominate Kenya’s export portfolio, with major buyers including:

  • European Union: Over 57%

  • United States: 16.75%

  • South Korea: 5.16%

  • United Kingdom: 3.43%

  • Other emerging markets: China, Australia, India

However, the upcoming EU Deforestation Regulation, taking effect in January 2026, poses a potential challenge. In response, Kenya has formed a multi-agency committee to evaluate readiness and establish compliance mechanisms.

Domestic Consumption on the Rise

Domestic coffee consumption is projected to grow by 6.9%, reaching 62,000 bags in 2025/26. This growth is driven by the rapid expansion of coffee shops, particularly in Nairobi, and a 15% surge in tourism in 2024. Kenya’s coffee culture is evolving, with increasing demand for specialty brews and locally roasted varieties.

Despite this growth, soluble coffee consumption remains low due to the lack of local processing facilities. Kenya imports approximately 45,000 bags of instant coffee annually.

Stock Levels and Imports

Ending stocks are expected to increase to 86,000 bags in 2025/26, reflecting higher production. For 2024/25, stock estimates have been revised downward to 63,000 bags due to higher exports and tighter output.

Conclusion: Kenya’s Return to Coffee Leadership

With production, exports, and consumption all trending upward, Kenya is once again asserting itself on the global coffee stage. While challenges like EU environmental compliance lie ahead, the country’s proactive reforms and farmer-focused strategies signal a new era of growth and global relevance for Kenyan coffee.

World of Coffee Heads to Bangkok in 2026: Asia’s Premier Coffee Event Expands to Thailand

The global coffee industry is gearing up for an exciting milestone as the Specialty Coffee Association (SCA) officially announced that Bangkok, Thailand will host the third edition of World of Coffee Asia from May 7–9, 2026. The announcement was made during a formal signing ceremony at World of Coffee Jakarta 2025, with the participation of Yannis Apostolopoulos, CEO of the SCA, Danny Shin, CEO of Exporum Inc., and Meechai Amornpathanakul, Chairman of the Barista Association of Thailand (BAT).

Following the inaugural Asian edition in Busan, South Korea (2024) and this year’s successful event in Jakarta, Indonesia (2025), the decision to host World of Coffee Asia 2026 in Bangkok reflects the region’s rising influence in the specialty coffee industry and the increasing global demand for engagement across Asian coffee markets.

A Strategic Move for Global Coffee Expansion

The upcoming World of Coffee Bangkok 2026 will take place at the Bangkok International Trade & Exhibition Centre (BITEC), one of Southeast Asia’s most prestigious and modern event venues. The event is expected to attract thousands of stakeholders from across the specialty coffee value chain — including farmers, producers, exporters, importers, roasters, equipment manufacturers, baristas, and café owners.

“Thailand’s specialty coffee community has grown in remarkable ways over the past decade,” said Yannis Apostolopoulos, CEO of the SCA. “Bringing World of Coffee to Bangkok is part of our ongoing mission to support sustainable, inclusive trade and education across the global coffee sector. With Thailand’s deep-rooted coffee culture and Bangkok’s accessibility as a regional hub, we’re proud to offer an event that reflects both heritage and innovation.”

Thailand’s Specialty Coffee Industry in the Global Spotlight

Thailand has emerged as a dual force in the global coffee landscape — both as a producing origin and as a vibrant consumer market. Highland regions such as Chiang Mai, Chiang Rai, and Nan are now internationally recognized for producing high-quality Arabica beans, while southern provinces like Chumphon are key in Robusta cultivation.

At the same time, Thailand’s domestic coffee scene has undergone a transformation. Bangkok, the country’s capital, is now home to a booming café culture, hosting hundreds of specialty coffee shops, micro-roasters, and barista training academies. The rise of local competitions, investment in education, and focus on traceability and quality have all contributed to Thailand’s increasing global recognition in specialty coffee circles.

“Each edition of World of Coffee Asia brings new momentum to the region,” said Danny Shin, CEO of Exporum Inc. “Bangkok is the perfect next chapter — a city with deep cultural roots, a progressive café scene, and a growing role in global coffee conversations. We are thrilled to work alongside SCA and BAT to deliver an event that both honors tradition and drives the future of coffee in Asia.”

Organized Collaboration and Local Empowerment

The Barista Association of Thailand (BAT) will serve as the local host and strategic partner, ensuring that the event highlights the richness of Thailand’s coffee identity and provides meaningful opportunities for local professionals and smallholder producers.

“Our goal is to bring the Thai coffee community into the global spotlight,” said Meechai Amornpathanakul, Chairman of BAT. “This is a chance for Thai baristas, farmers, and entrepreneurs to showcase their skills and coffees to an international audience. It’s also a chance for the world to discover the unique stories and flavors that define Thai coffee.”

What to Expect at World of Coffee Bangkok 2026

Attendees of World of Coffee Bangkok can expect a full program of exhibitions, workshops, and industry engagement. Key features include:

  • A large-scale international trade show featuring top coffee brands, roasters, importers, green coffee traders, and equipment manufacturers.

  • Cupping sessions and tasting rooms spotlighting coffees from Thailand, Southeast Asia, and around the world.

  • Educational workshops, lectures, and panel discussions hosted by global experts, covering topics from brewing science to sustainability and digital innovation.

  • Coffee competitions including latte art showcases, brewing contests, and barista championships.

  • Networking opportunities and business matchmaking for local producers and international buyers.

The event is designed to cater to both trade professionals and passionate consumers, bridging the gap between origin, market, and innovation.

A Milestone for Coffee in Southeast Asia

World of Coffee Bangkok 2026 marks a significant moment for Southeast Asia’s coffee landscape. It underscores the growing recognition of Asian coffee producers, the evolution of consumer markets across the region, and the shared commitment to sustainability, quality, and collaboration.

Registration details for exhibitors, sponsors, speakers, and attendees will be released in the coming months. As preparations begin, industry leaders from around the world are encouraged to mark their calendars and explore opportunities to participate in one of the most dynamic coffee events of the decade.

Discover why Bangkok is the next global destination for specialty coffee — join the journey at World of Coffee 2026.

Steffen Schwarz: A Silent Shift Towards Canephora is Redefining Europe’s Coffee Preferences

Dr. Steffen Schwarz, an expert in applied coffee science, believes that a gradual yet decisive transformation is underway in Europe’s coffee preferences. Canephora beans (commonly known as Robusta) are quietly gaining ground over Arabica, which has long dominated the continent’s coffee culture. Schwarz refers to this as a “silent shift,” driven not only by economic factors but by deeper changes in how quality, taste, and function are perceived.

Dr. Schwarz is a leading figure at Coffee Consulate, an independent training and research center based in Germany. The center offers scientifically grounded programs for the coffee industry, including flexible one-day workshops and comprehensive training for professionals in cafés, hotels, bakeries, roasteries, and farms. One of its most advanced offerings is the Coffeologist program, which consists of 12 one-day workshops covering the full coffee value chain—from bean to cup. This builds on the Coffee Connoisseur course, a six-day program focused on cultivation, processing, botanical principles, origin profiles, and professional tasting.

According to Schwarz, the European Coffee Report 2023/2024 confirms a slight decline in Arabica’s market share in EU and EFTA imports, now at 59.2%, while Canephora has risen above 40%—even surpassing Arabica in countries like Italy, Portugal, and Eastern Europe.

This shift, he says, is a response to climate challenges, production efficiency, and evolving consumer behavior. Canephora offers greater resilience, higher yields, and better adaptability for farmers in regions such as Southeast Asia and West Africa. In turn, Europe is adjusting its import dynamics to align with availability.

He also highlights that modern processing techniques—such as anaerobic fermentation and sugarcane washing—have improved the sensory profile of Canephora, bringing out notes of dark chocolate, spices, and red fruit, particularly in high-altitude or hybrid varieties.

Northern markets like Germany and Scandinavia are now integrating high-quality Canephora into blends and even offering it as single-origin coffee—something that was previously rare. This is partly due to younger consumers’ preferences for stronger, fuller-bodied coffee aligned with their tastes for cold brews and energy drinks.

Schwarz raises critical questions: Should Canephora be evaluated on its own terms rather than Arabica’s standards? Will European markets pay a fair premium for quality Canephora as producing countries invest in excellence? Or will it remain trapped in a commodity model focused on quantity?

He concludes that the future of coffee in Europe won’t be decided in cupping labs alone—it will depend on how cultural, economic, and scientific frameworks evolve to embrace this silent shift.

Baitna Café: A Remarkable Success Story Brewing in the Heart of Sharjah

Achieving notable success in the food and beverage industry within just six months is rare. In a city like Sharjah, where the café scene is vibrant and highly competitive, it’s even more impressive. Yet, Baitna Café has defied the odds — transforming from an ambitious idea into one of the most sought-after destinations for coffee lovers in the UAE.

The story begins with young entrepreneurs Hanan Al Haddad and Abduljawad Al Qaisi, who set out to build more than just a coffee shop. They envisioned a space that radiates warmth, community, and belonging. They chose a striking location — the 30th floor of Tabarak Tower in Al Mamzar — and named it Baitna, Arabic for “our home.” To bring their vision to life, they teamed up with internationally renowned barista and coffee expert Samson Kiaponga, who took the lead in crafting the café’s experience and training the team.

I had the chance to visit Baitna Café during its early soft opening. I saw ambition in the eyes of the founders, but also a clear sense of anxiety — understandable, considering the high costs and risks of launching such a project in a premium location. Yet beneath that concern was a powerful commitment to delivering something exceptional.

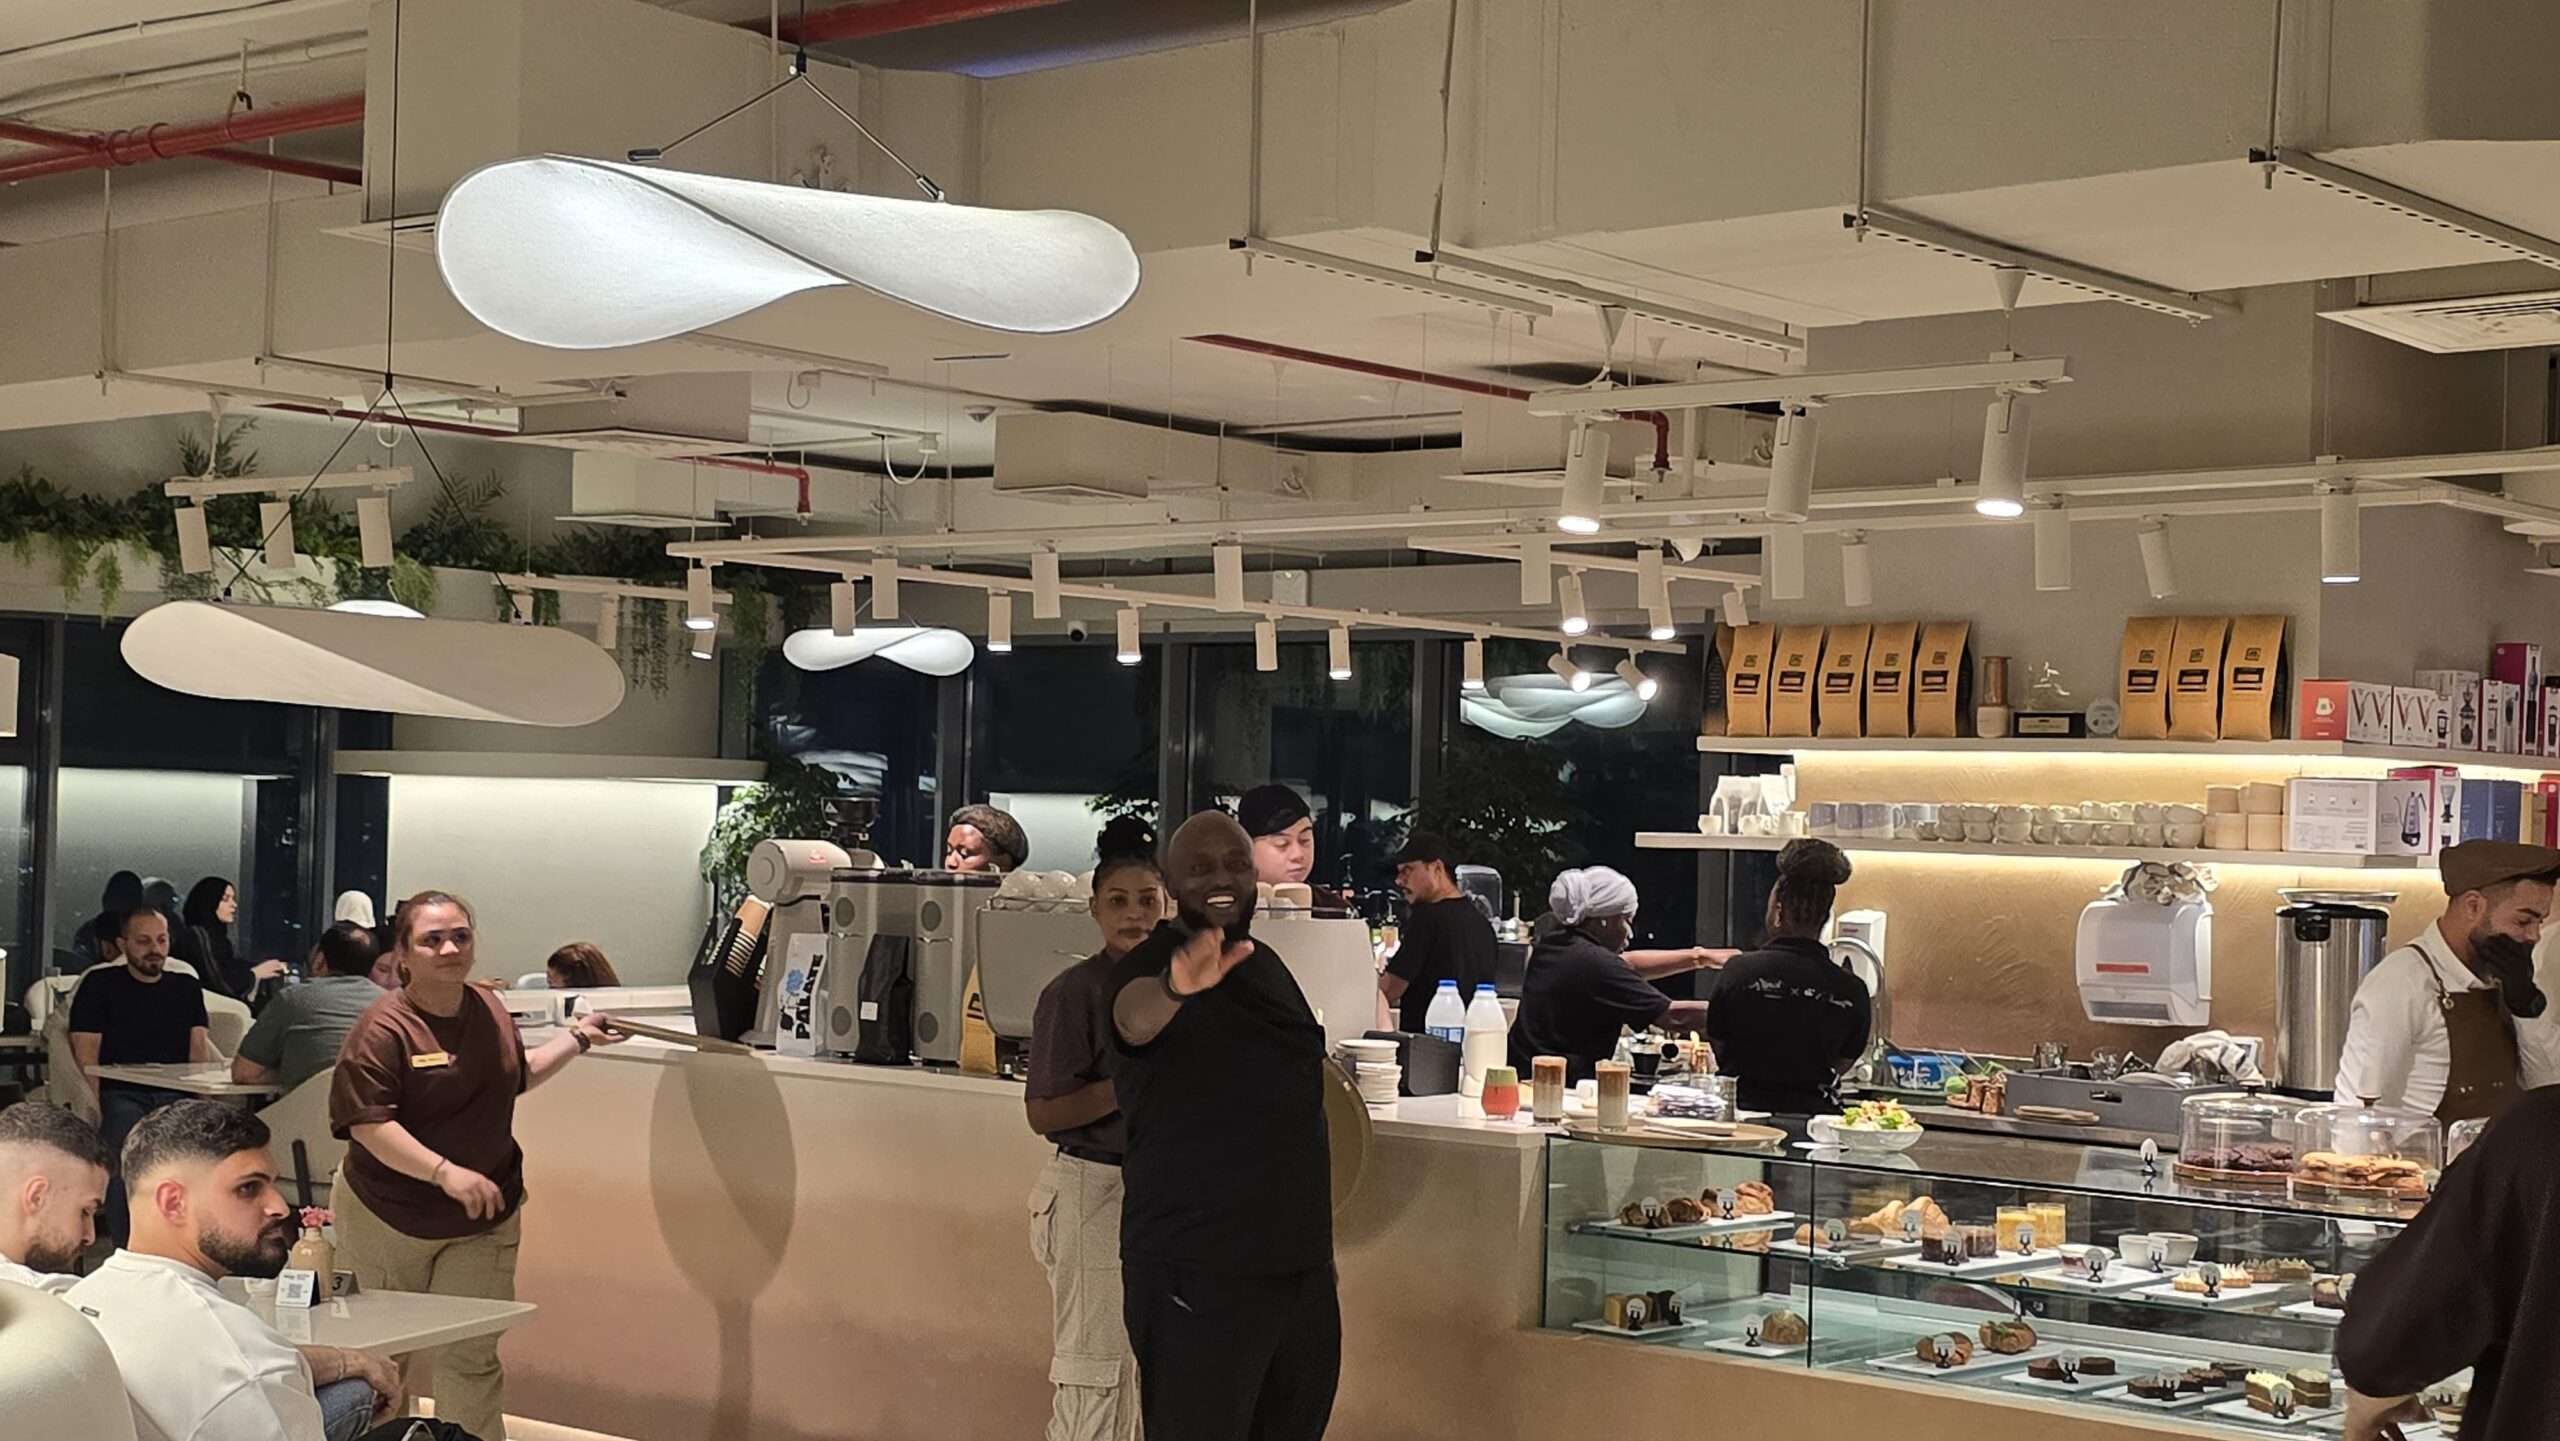
Several months later, I returned to the café, this time with two old friends from university. We were looking for a cozy, special place to enjoy an evening together. But what greeted us was a pleasant surprise: a long line at the entrance and a requirement for reservations. Despite its spacious layout — with a large indoor lounge and two outdoor terraces offering stunning views of Dubai and Sharjah — the café was full.

I worried we might not find a table or would have to leave, but that worry quickly turned to admiration. Seeing a local business thrive this quickly was heartwarming. Thankfully, Samson kindly found us a small table in the corner — more than enough to enjoy the atmosphere.

From that cozy spot, we watched the evening unfold: guests chatting over perfectly brewed drinks, the team moving swiftly yet professionally, and the glittering skyline stretching across the horizon. Despite the rush, the staff upheld the highest standards of quality, service, and hospitality.

I wasn’t able to speak with Hanan or Abduljawad that night, and even Samson was too busy to talk. But the reasons for the café’s success were clear in every detail:

  1. Product quality – carefully selected beans from Colombia and Ethiopia, plus creative, well-balanced signature drinks.

  2. Outstanding service – a well-trained, upbeat team that performs under pressure.

  3. Unforgettable location – breathtaking views and a serene atmosphere that elevates the coffee experience.

  4. Inspirational leadership – three passionate individuals who brought this vision to life with clarity and purpose.

Baitna Café is more than a coffee shop. It’s a complete experience, one that begins before you even step inside. From sunsets on the terrace to peaceful moments high above the city, from exceptional drinks to thoughtful design — every aspect has been crafted with intention.

In a market filled with lookalike concepts, Baitna Café stands apart by offering something deeply authentic. This is a space where coffee is respected, guests are valued, and each visit feels memorable.

This project proves a simple truth: when genuine passion meets professional execution, remarkable things happen — and they happen fast.

To Hanan, Abduljawad, Samson, and the entire Baitna Café team — congratulations. You haven’t just opened a café. You’ve created a home for coffee, one that floats high above the city and stays in the hearts of those who visit.